SACRAMENTO — A new report by the California Budget & Policy Center — Why Aren’t Corporations Paying Their Fair Share of Taxes? — finds corporations are paying less than half the amount in state taxes, as a share of their income, than they did just four decades ago. This is largely due to state policymakers’ decisions to cut tax rates and expand tax breaks for corporations.
Introduction
California’s corporate taxes raise revenue that helps pay for the public services and infrastructure that enable businesses to exist and to profit in local communities and statewide. Corporations depend on high-quality schools to produce a dedicated and educated workforce and to help attract qualified employees. Corporations, like individuals, also benefit from a range of public services such as those provided by fire departments and the state judicial system that protect corporations’ legal rights.
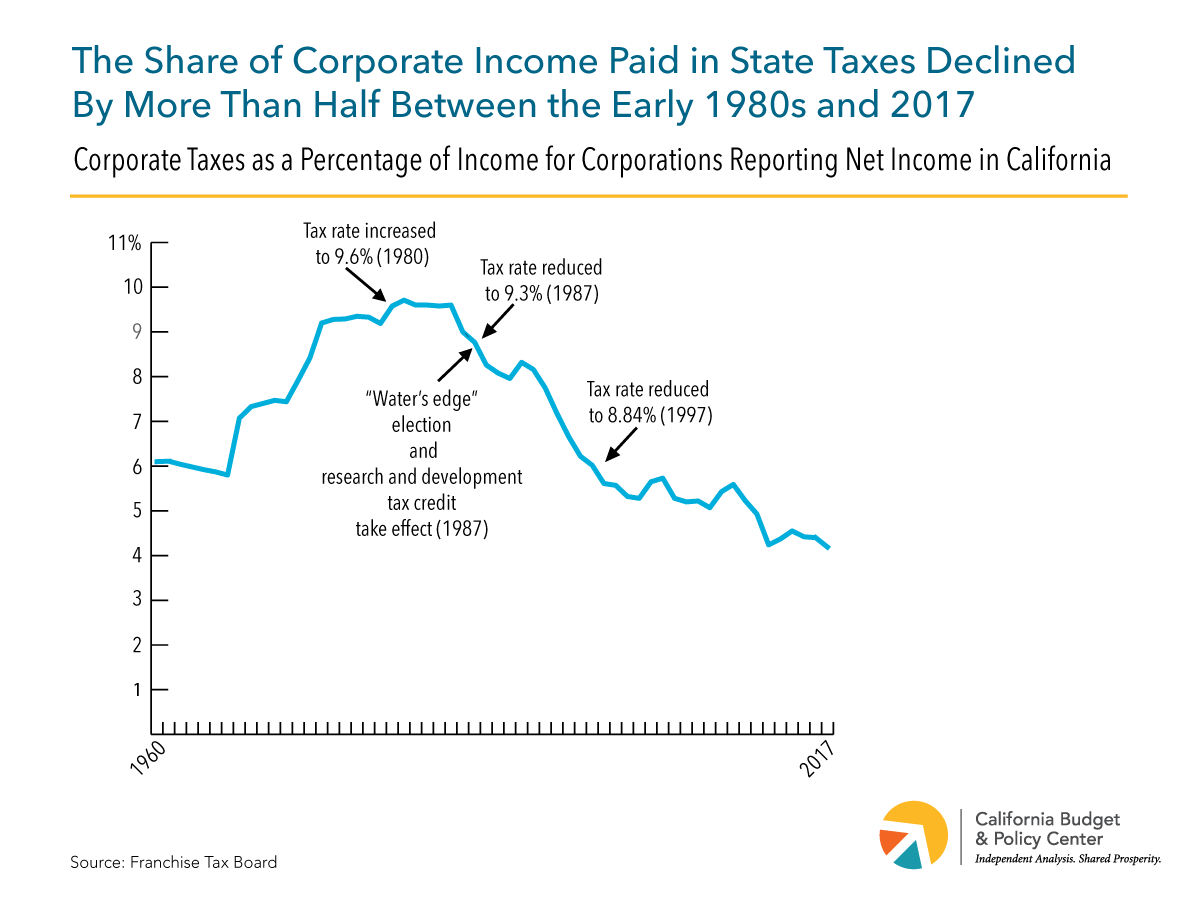
California cut the state corporate tax rate twice since the 1980s
Yet, profitable corporations are contributing less in taxes that support these public services, as a share of their California income, than a generation ago. This Issue Brief shows how far corporate taxes have fallen as a share of corporate profits in California, explains several reasons for the decline, and points to inequitable policies that provide larger benefits to corporations that are thriving than to small businesses and Californians who are struggling to live and work in the state. By examining and limiting corporate tax policies that benefit multinational corporations and big businesses, California policymakers have an opportunity to advance a more equitable tax structure, raise revenue for critical services, and achieve a vibrant state and economy that serves more people.
“
Unlike spending on programs that is deliberated during the
annual state budget cycle, policymakers do not scrutinize
most tax expenditures each year.
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
About this event
Our tax policies affect who gains wealth — namely corporations and wealthy white Californians — and who remains locked out from out state’s prosperity — Californians of color and people in low- and middle-income households. Join us to learn how the state’s current tax structures perpetuate wealth and racial disparities and how policymakers can work toward building a more equitable California.
Thank you to our event sponsors: Heising-Simons Foundation,
Disclaimer
The California Budget & Policy Center engages in independent fiscal and policy analysis and public education with the goal of improving public policies affecting the economic and social well-being of Californians with low and middle incomes.
Be part of the action
From speaker series to virtual panels to our annual conference, we host a variety of in-person and digital events to help you advance a more equitable and just California.
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
Local tax revenue reflects a community’s shared effort to support vital public services that all Californians need to live in our cities and counties, such as education for students in K-12 schools and community colleges, housing, health care, public parks, and libraries. When tax breaks provide advantages to some taxpayers over others, it not only creates inequities but can also lead to revenue losses that compromise the ability of schools and local communities to provide essential services for Californians. This is the case with commercial and industrial property taxes across California, and why voterswill be asked in fall 2020 to vote on Proposition 15, an amendment to the state Constitution that would change how commercial and industrial properties are taxed to provide more revenue for schools and communities.
Under Prop. 15, commercial and industrial properties would be taxed based on their market value rather than their purchase price. By moving from a property tax system based on purchase value to one based on market value, Prop. 15 would raise an estimated $6.5 billion to $11.5 billion annually in property tax revenues for K-12 schools and community colleges, counties, cities, and special districts, according to the Legislative Analyst’s Office.
FAQ: Understanding Commercial Property Tax & Revenue in California
How Are Commercial and Industrial Properties Taxed Today? The general property tax rate for California commercial and industrial properties has been capped at 1% of assessed value since voters approved Prop. 13 in 1978. Counties determine the assessed value of commercial and industrial properties based on the property’s purchase price plus an annual adjustment for inflation not to exceed 2%. Counties collect property taxes and are generally only allowed to reassess properties to their market value when they undergo a change in ownership or new construction.
How Is Revenue From Commercial and Industrial Property Taxes Distributed Across California? Revenue received from the taxes paid by commercial and industrial property owners is distributed to counties, cities, K-12 schools and community colleges, and special districts (such as public utility districts and fire protection districts) for services provided to Californians, based on complex state laws. The share of countywide property tax revenue going to each local entity is largely based on the distribution of these revenues dating back to the mid-1970s – before Prop. 13 was enacted and each local entity was able to set its own property tax rates. This means that there is wide variation among counties in the share of revenue going to – and the level of services provided by – each type of local government.
Why Are Commercial and Industrial Property Taxes Inequitable for Californians and in Need of Reform? The property assessment limits set by Prop. 13 mean that an owner that purchased a commercial or industrial property several decades ago pays far lower taxes than an owner that recently purchased a similar property – leading to inequity among local businesses and a significant loss of revenue at the expense of schools and local community services. Schools and local communities are losing significant revenues every year as properties that have not changed ownership in many years are assessed at values much lower than their market values. Additionally, when a property changes hands, commercial and industrial property owners can more easily avoid reassessment than residential property owners due to the laws defining ownership changes and the complexity of business property ownership.
Report: Raising Revenue for Schools and Local Communities, Changing California’s Inequitable Taxing of Commercial Properties, and Understanding Proposition 15
Local tax revenue reflects a community’s shared effort to support vital public services that all Californians need to thrive in our cities and counties. This ranges from education for students in K-12 schools and community colleges to access to housing, health care, public parks, and libraries. These vital public services are supported by tax revenues from commercial and industrial properties – many of which are still taxed based on purchase prices that are more than four decades old. California voters will be asked in fall 2020 to vote on a measure known as Proposition 15, an amendment to the state Constitution that would change how commercial and industrial properties are taxed and provide more revenue for schools and local communities to support services Californians rely upon.
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
The share of California corporate income paid in state taxes declined by more than half during the past three decades. In the early 1980s, corporations that reported profits in California paid more than 9.5% of this income in state corporation taxes. In contrast, corporations paid just 4.2% of their California profits in corporation taxes in 2017, the most recent year for which data are available. California’s state budget would have received $11.2 billion more revenue in 2017 had corporations paid the same share of their income in taxes that year as they did in 1981 – more than the state spends on the University of California, the California State University, and student aid combined.
Corporations pay less of their income in taxes today – even amid the COVID-19 economic crisis – than they did in the 1980s in part due to the reduction of tax rates by state policymakers. Since increasing the corporate tax rate to 9.6% in 1980, the Legislature has cut the rate twice: from 9.6% to 9.3% in 1987 and from 9.3% to 8.84%, its current level, in 1997.
In addition to cutting tax rates since the 1980s, state policymakers have enacted several corporate tax breaks that reduce the share of income that corporations pay in California corporation taxes. For example, beginning in 1987, California allowed multinational corporations to lower their tax liability by calculating their California income based on either their total income from worldwide operations or only from their operations within the US. This so-called “water’s edge” election will cost the state an estimated $2.4 billion in 2019-20. Also in 1987, state policymakers established the state’s research and development (R&D) tax credit, which primarily benefits large corporations and will cost the state an estimated $1.8 billion in 2019-20. As with many corporate income tax credits, the amount spent on the R&D credit each year is unlimited, and there is no expiration date. In total, California is projected to spend $5.7 billion on tax expenditures for corporations in 2019-20.
California spending on tax breaks for corporations far exceeds the amount the state spends on tax benefits for low-income Californians. In 2019, California was projected to spend $1 billion on the state’s two largest tax credits targeted to Californians with low incomes – the California Earned Income Tax Credit (CalEITC) and the Young Child Tax Credit (YCTC). The CalEITC and YCTC boost the incomes of families and individuals with annual earnings of less than $30,000, a large majority of whom are people of color. The CalEITC alone directly benefited 3.7 million Californians in 2018. One example of how tax credits, exemptions, and deductions could be more equitably targeted is to extend the CalEITC and YCTC to all immigrant families. The Legislature could pay for the extension of the CalEITC and YCTC to these immigrant families by eliminating or reducing tax breaks for corporations that can afford to contribute more.
Corporations can contribute more not only because they are paying less than half the amount in state taxes than they did three decades ago, but also because they are likely to pay far less of their income in federal taxes due to the federal Tax Cuts and Jobs Act (TCJA), signed by President Trump in 2017. The TCJA made several changes to federal tax law that benefit corporations, including slashing the federal corporate income tax rate from 35% to 21%, the largest one-time reduction in US history. The Institute for Taxation and Economic Policy (ITEP) estimated that the tax benefit to California corporate business owners was more than $13 billion in 2018. The reduction in federal corporate taxes may argue for an increase in the state’s corporate income tax rate. However, policymakers have other options for ensuring that corporations pay their fair share in state taxes. For example, they could review existing corporate tax provisions, such as corporate tax credits, exemptions, and deductions, and reduce or eliminate those that are not achieving the state’s policy goals. By reducing spending on corporate tax breaks, the state would have more resources available to support families with low incomes who are struggling to afford the costs of living in California, COVID-19 crisis or not.
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
California loses a large amount of state revenues through tax breaks, also called “tax expenditures,” with much of the benefits going to high-income households and corporations. Personal income and corporate income tax expenditures combined are projected to amount to more than $63 billion in forgone state revenues in 2019-20 (the fiscal year that started on July 1, 2019), or an amount equivalent to more than 40% of the 2019-20 General Fund budget. This is revenue that otherwise could go to Californians who need additional support to be able to live and work in the state while strengthening the state’s economy.
Unlike program spending, tax breaks generally are not up for debate every year, and instead often quietly continue from year to year. If tax breaks are debated at all, those discussions are largely deliberated outside of the usual budget cycle, reducing opportunities for advocates and the public to provide input on how the state is making fiscal decisions. Some of the largest tax expenditures – for example, the Mortgage Interest Deduction and the Water’s Edge Election – help higher-income households and businesses that do not need the help, or need it much less, while also reducing the resources available for individuals and families who do need support. This “upside-down” nature of the state’s tax expenditures also contributes to the racial wealth gap, as households with higher income and wealth that benefit most from many tax breaks are less likely to be comprised of people of color. Furthermore, it may be more effective to pursue many of the state’s policy goals through spending directly on services that benefit more Californians rather than indirectly through the tax code. California could improve its use of tax expenditures by setting sunset dates, requiring their periodic evaluation, and better targeting their benefits to low- and middle-income households. Doing so would free up funding that could be used to invest in policies that provide greater opportunities for millions of Californians that struggle with the cost of living to increase their incomes and wealth.
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
Introduction
The 2017 federal Tax Cuts and Jobs Act (TCJA) included a provision creating a new program designed to encourage private investments in economically distressed communities. The Opportunity Zones program provides federal tax incentives for investments in areas that meet certain criteria and have been designated as Opportunity Zones (OZs). Additionally, Governor Gavin Newsom’s 2019-20 budget proposal would provide state-level tax incentives for investments in OZs. There are 879 designated OZs in California, located in nearly all of the state’s counties. More than 4 million Californians live in these areas and will be potentially impacted by new investments eligible for Opportunity Zones tax incentives. The Opportunity Zones program has the potential to encourage new investments in eligible communities that improve the lives of residents with low incomes. However, the vast majority of the tax benefits will be realized by wealthy investors, and the program may accelerate gentrification in some areas or subsidize investments that offer little or no benefit to community residents.
This Issue Brief, the first in a series of Budget Center publications exploring the Opportunity Zones program, explains the structure of the program, its tax incentives, and how California’s communities may be affected.
The Basics: Opportunity Zones, Qualified Opportunity Funds, and Qualified Opportunity Zone Businesses
The TCJA allowed governors to nominate census tracts for OZ designation following certain federal criteria.[1] To qualify, census tracts must generally be low-income communities, defined as having a poverty rate of at least 20% or a median family income of 80% or less of the metropolitan area or state median family income.[2] States were also permitted to select a limited number of “contiguous tracts” that are not low-income communities but border a qualified low-income community and have a median family income that does not exceed 125% of that of the adjacent qualified low-income tract. Contiguous tracts may not comprise more than 5% of a state’s total selected OZs. Each state was permitted to nominate a total number of OZs not exceeding one-quarter of all eligible low-income tracts. In California, Governor Jerry Brown’s administration nominated 879 census tracts to become OZs, and the US Treasury Department certified all of them. One-tenth of California’s population (10.7%), nearly 4.2 million residents, live in OZ census tracts.[3] These designations will remain in effect for 10 years.
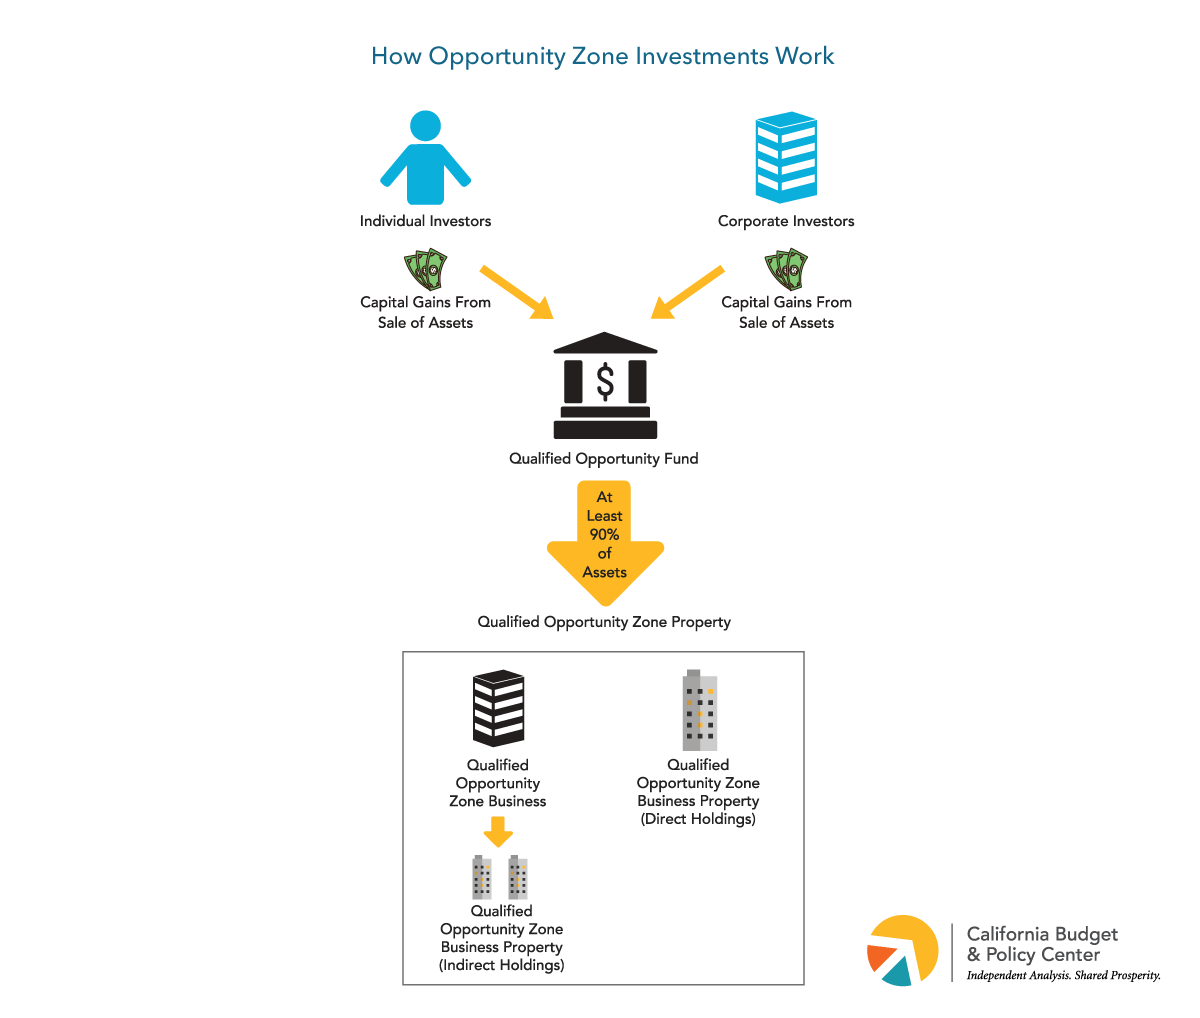
Individuals and corporations that invest in a Qualified Opportunity Fund (QOF) — an entity that in turn makes investments in OZs — are eligible for several tax benefits, discussed below. To be a QOF, at least 90% of the fund’s assets must be invested in “Qualified Opportunity Zone Property,” which may include either a stock or partnership interest in a “Qualified Opportunity Zone Business” that holds tangible property — such as buildings and equipment — in an OZ (known as “Qualified Opportunity Zone Business Property”) or direct holdings of such business property (Figure 1). A QOF, which may be a corporation or partnership, does not need to apply for QOF designation and may self-certify with the Internal Revenue Service (IRS).
Figure 1
The TCJA statute is vague about how much of a QOF’s or Qualified Opportunity Zone Business’ property must be located in an OZ, but the IRS has issued proposed regulations that seek to clarify this issue. If these proposed regulations go into effect, a QOF could have less than half of its assets in use within an OZ and its investors would still be eligible for the full tax benefit.[4]
The law also specifies that, if the original use of the Qualified Opportunity Zone Business Property does not start with the QOF investment, the property must be “substantially improved” — requiring the QOF to spend at least as much to improve the property as it spent to acquire it. Ostensibly, this requirement aims to prevent investors from getting tax benefits by simply buying property in an OZ without adding any value for the community. The IRS’ proposed regulations would make this requirement more flexible, which could increase the likelihood that tax subsidies will go to investments that provide few community benefits.[5]
The broad definitions in the law and the flexibility offered in the proposed regulations mean there will likely be few limitations on the types of investments that will qualify for preferred tax treatment. For example, investments in startup businesses, expansions of existing businesses, construction or substantial rehabilitation of residential or commercial properties, and infrastructure improvements are all likely to qualify. The only businesses explicitly prohibited from receiving Opportunity Zone tax benefits are so-called “sin businesses” including liquor stores, gambling facilities, golf courses, country clubs, tanning facilities, and massage parlors.
The regulations for the Opportunity Zones program have not been finalized at the time of this publication, and the IRS will issue further proposed regulations to clarify other aspects of the law in the coming months. The final regulations will impact the degree to which tax-privileged investments substantively benefit OZ residents and the generosity of the tax benefits for investors.
Tax Incentives for Investors Can Be Lucrative
The Opportunity Zones program attempts to promote investments in OZ census tracts by providing several tax breaks on capital gains that are reinvested into a QOF. A capital gain results when a taxpayer sells or exchanges an asset — such as corporate stock shares or real estate — at a price higher than its purchase price.[6] For federal tax purposes, the short-term capital gains tax rate, which applies to gains on assets held for one year or less, is equal to the taxpayer’s ordinary income tax rate, with a maximum rate of 37%. Lower federal rates apply to long-term capital gains on assets held for more than one year. The maximum rate for long-term capital gains is 20% plus a 3.8% surtax related to the Affordable Care Act.[7] Under the Opportunity Zones program, taxpayers reinvesting capital gains into a QOF within 180 days of the sale or exchange of the original investment are eligible for three federal tax benefits:
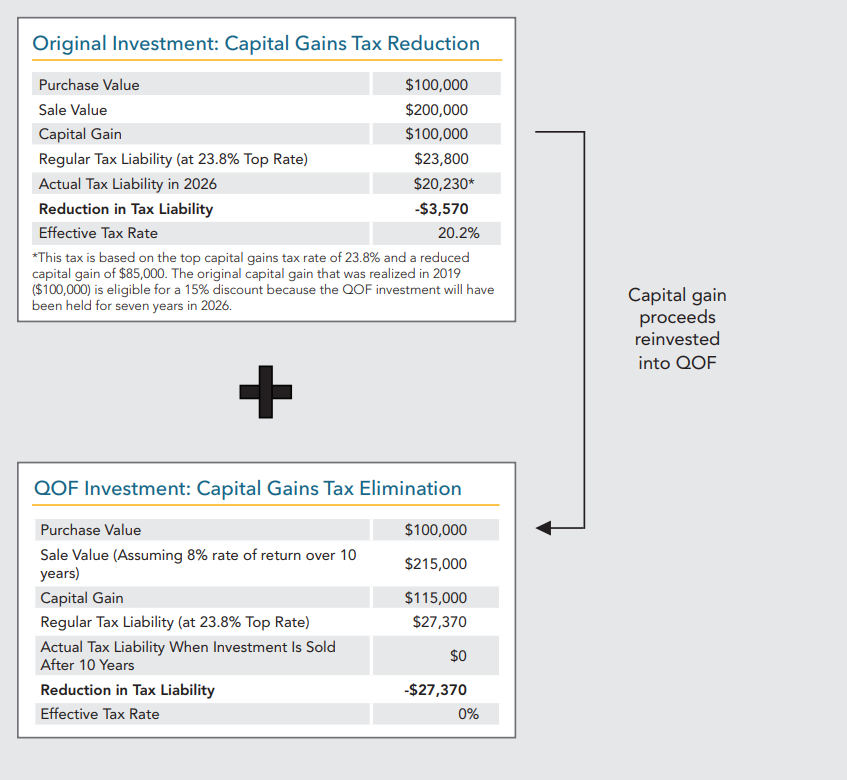
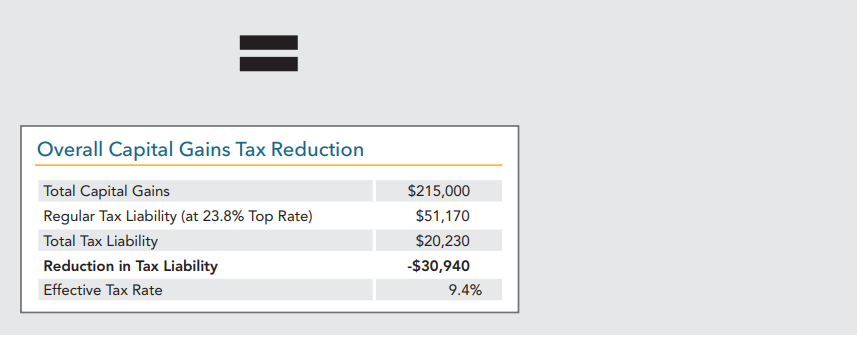
Deferral of tax on the capital gain on the original investment until 2026 (or the time the QOF investment is disposed of, if earlier) — allowing the reinvestment of the entire capital gain into a QOF with the potential benefit of a higher return.
Reduction of tax on the capital gain on the original investment if the QOF investment is held long enough (the taxable value of the capital gain — and thus the tax liability — is reduced by 10% if the QOF investment is held for five years and by 15% if the QOF investment is held for seven years).
Elimination of tax on the capital gain on the QOF investment if it is held for 10 years.
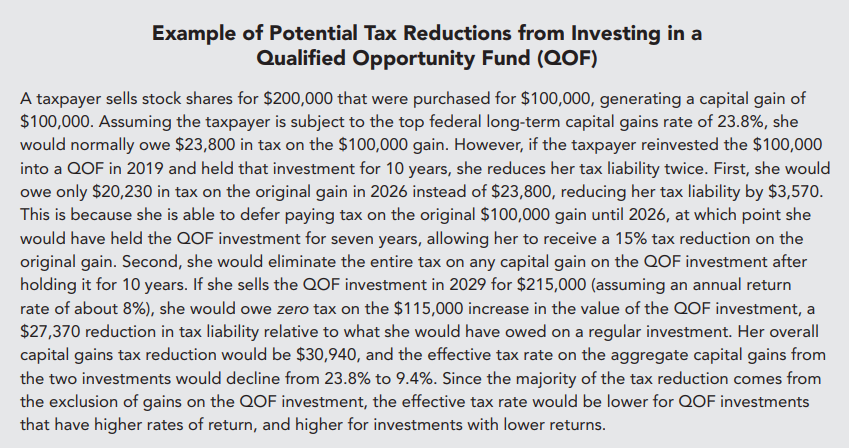
There is no upper limit on the tax benefits any QOF investor can receive, nor on the overall cost to the federal government in foregone tax revenues. (See text box for an example of the potential tax benefits from investing in a QOF.)
Wealthiest Investors Will Reap Greatest Share of Tax Savings While Community Benefits Are Uncertain
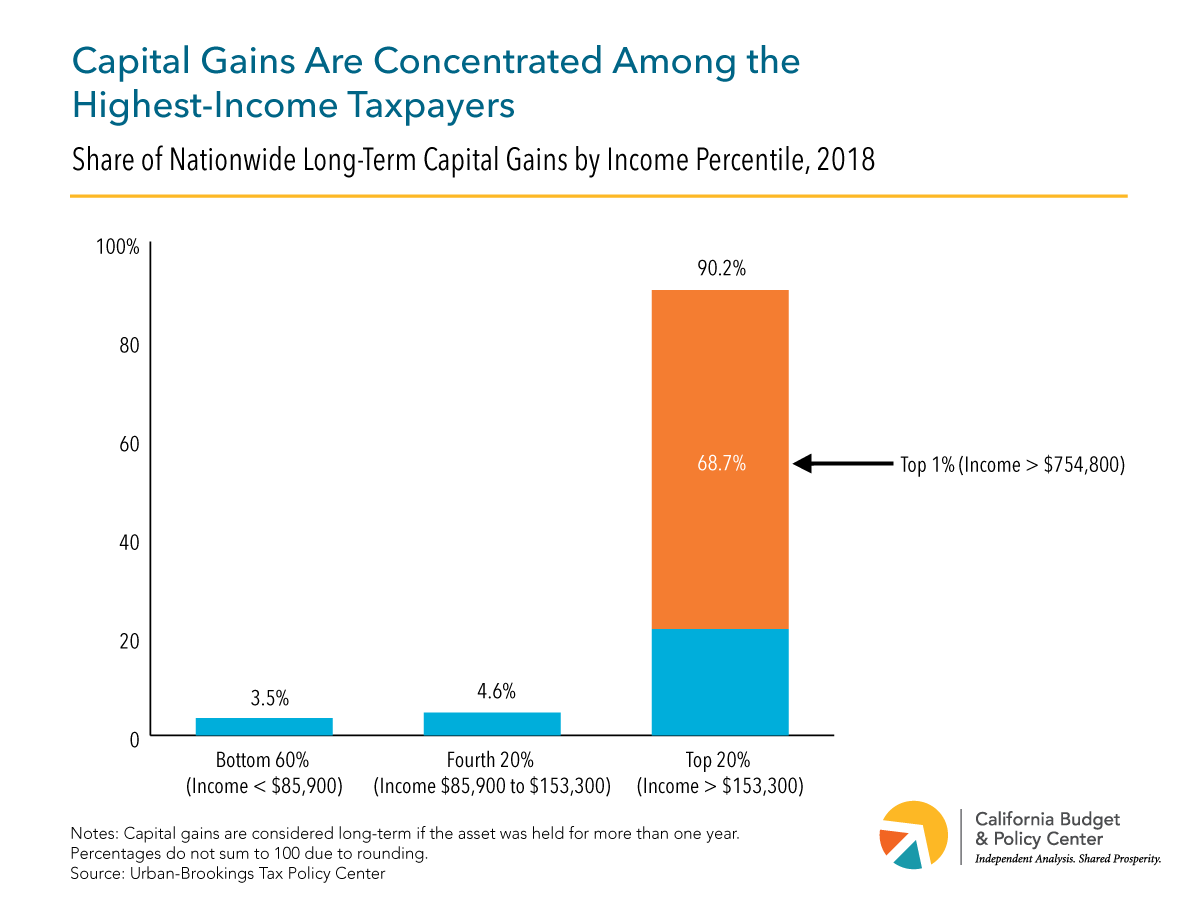
Taxpayers with holdings of appreciated assets will be the direct beneficiaries of Opportunity Zones tax incentives. Most of these benefits will accrue to very well-off investors, who hold a disproportionate share of such assets. Only 9.2% of all taxpayers report realizing any long-term capital gains, according to estimates from the Urban-Brookings Tax Policy Center.[8] In addition, capital gains are highly concentrated at the top of the income distribution. The top 20% receive 90.2% of all reported long-term capital gains, with the top 1% collecting 68.7% of these gains (Figure 2). Thus, very few low- or middle-income families will receive any tax benefits from the Opportunity Zones incentives.
Figure 2
While the benefits to wealthy investors are clear, there is no guarantee that the subsidized investments will positively impact current residents of designated OZs. The Opportunity Zones program is not the first attempt to bring investment and employment into areas that lack financial resources and jobs. A variety of federal and state programs have provided tax incentives and other benefits to attract business and capital investment and to increase employment in such areas, including Empowerment Zones, Enterprise Communities, Renewal Communities, New Market Tax Credits, and state-level enterprise zones. Research on the community impacts of these programs has reached mixed conclusions. Some studies have found increases in employment and wages and reductions in poverty in designated zones relative to similar communities where these incentives were unavailable, while others have found little evidence that the incentives led to statistically significant community improvements.[9] The inconclusiveness of the research exploring the connection between economic development tax incentives and community outcomes suggests that the costs of such incentives may outweigh the benefits.
A primary concern is investors may be drawn to projects or businesses in areas already in the process of gentrification, as these investments will likely yield the highest returns.[10] If investors do prioritize projects in gentrifying areas, a large portion of the tax-preferred investments could flow into communities that have fewer challenges attracting capital, meaning US taxpayers would be unnecessarily subsidizing investments that likely would have occurred without the incentives. The extent to which this occurs will partially depend on which census tracts states designated as OZs. (The next publication in this series will examine California’s selection of OZs, including the share of selected areas showing signs of gentrification.)
Since the professed goal of the Opportunity Zones program is to improve economically distressed communities, and not to give tax breaks to wealthy investors, the primary question should be whether the inflow of funds meaningfully improves the circumstances of residents in those communities. For instance, if the incentive results in more affordable housing or local businesses that create job opportunities for low-income residents, this would be considered a successful outcome — even if wealthy investors become wealthier in the process. However, given the few restrictions placed on the investments that can be made, and the laxness of some of the regulations proposed by the IRS, there is a real possibility that some of these new investments will contribute to the gentrification of communities. For example, QOFs may invest in luxury condominiums or companies that mostly employ high-skilled workers from outside the community. In fact, these types of investments may be more attractive than “social impact” investments due to potentially higher returns. This could put low-income residents at risk of facing increased costs of living or being displaced, harming the very people the incentive is intended to help. And since OZ census tracts have higher concentrations of black and Latinx residents than other communities, this could exacerbate existing racial and ethnic inequities.[11]
Some of the most disadvantaged communities may not see any new investment at all. These communities have a scarcity of assets to attract investors, present higher risks, and offer potentially lower returns. Therefore, investors are more likely to choose projects in areas that are already more advantaged or showing signs of revitalization over neighborhoods that have the greatest need for new resources.
Another consideration is the overall cost of the Opportunity Zones incentives in the form of foregone federal revenues from capital gains taxes. These lost revenues — mostly benefiting high-income investors — could instead help pay for other services that may have a greater impact on vulnerable communities in California and across the nation. The official cost estimate for the tax incentives is small relative to total cost of the TCJA — $1.6 billion over 10 years in a package of nearly $2 trillion in tax cuts.[12] However, the long-run costs could be much greater given that this estimate does not include revenue losses from the complete exclusion of gains on QOF investments held for 10 years, which fall outside the 10-year period for which budget estimates were made.
The high levels of flexibility for investors and uncertainty regarding the potential benefits and harms to OZ residents elevate the need for strong reporting and data collection requirements. The law does not include such requirements, but the US Treasury Department has the discretion to issue them in forthcoming regulations. Thus, until the final regulations are released, it is unknown whether there will be sufficient and transparent information available to determine how the tax incentives are being used and how subsidized investments are affecting the communities in which they are made.
What’s Next for California’s Opportunity Zones?
Now that the selection of OZ census tracts in California has been finalized, state and local leaders are contemplating how to encourage meaningful investments that will improve the lives of people in struggling communities. Policymakers are considering whether to provide state-level tax incentives to make QOF investments even more attractive, how to align existing state and local resources with those investments, and how to ensure transparency and accountability. Given that the federal tax benefits are heavily skewed toward wealthy investors (as would be state-level capital gains tax breaks) and that residents of affected communities may face affordability pressures and displacement risks, any state-level Opportunity Zones incentives should be structured to 1) provide greater opportunities for lower-income community members, 2) safeguard residents against displacement, and 3) avoid providing a windfall for the wealthy at the expense of the state’s finances. Finally, if state and local governments provide additional incentives to encourage investments in OZs, such incentives should be more narrowly targeted to investments likely to benefit current residents, and data collection and evaluation requirements should be established to enable an assessment of whether the incentives are achieving their intended purpose.
[1] The statute governing Opportunity Zones is found in the new Section 1400Z of the US Internal Revenue Code (26 US Code Section 1400Z).
[2] The definition of “low-income community” for the Opportunity Zones program comes from the statute governing the New Markets Tax Credit (26 US Code Section 45D(e)). For a census tract located in a metropolitan area to qualify, it must have a poverty rate of at least 20% or a median family income not exceeding 80% of the greater of the statewide median family income or the metropolitan area median family income. For a census tract not located in a metropolitan area to qualify, it must have a poverty rate of at least 20% or a median family income not exceeding 80% of the statewide median family income.
[4] The TCJA requires that “substantially all” of a business’ tangible property be Qualified Opportunity Zone Business Property, “substantially all” of which is in use in an OZ. The law does not define “substantially all,” but the IRS’ proposed regulations would define it as 70% in both cases. This means a business would only need to have 49% of its tangible property in an OZ (70% times 70%). Since the law requires only 90% of a QOF’s assets to be Qualified Opportunity Zone Property, a QOF holding property through an operating business could have as little as 44.1% of its assets being used in an OZ. US Department of the Treasury, Internal Revenue Service, REG-120186-18: Investing in Qualified Opportunity Funds (April 17, 2019), pp. 77-78.
[5] The proposed regulations released in October 2018 specify that only the value of buildings, excluding the value of the underlying land, would be considered in the calculation to determine whether a property has been substantially improved, which would allow more real estate investments to meet this test. Brett Theodos, Steven M. Rosenthal, and Brady Meixell, The IRS Proposes Generous Rules for Opportunity Zone Investors but What Will They Mean for Communities? (Urban-Brookings Tax Policy Center: October 23, 2018). Additionally, proposed regulations released in April 2019 clarify that unimproved land does not need to be substantially improved, but that such land must be used in a trade or business and would not be considered Qualified Opportunity Zone Business Property if it were being held for investment. The IRS is seeking comments on whether additional rules are needed to prevent QOFs from acquiring land in an OZ without adding any value or economic activity. US Department of the Treasury, Internal Revenue Service, REG-120186-18: Investing in Qualified Opportunity Funds (April 17, 2019), pp. 12-14.
[6] Technically, a capital gain is the difference between an asset’s sale price and its “basis,” which equals the asset’s purchase price with some adjustments, such as the cost of commissions for stocks or the cost of improvements minus depreciation for real property.
[7] Thus, the maximum federal tax rate on long-term capital gains is 23.8%. This includes the top long-term capital gains rate of 20%, which for the 2019 tax year applies to taxpayers with incomes above $434,550 ($488,850 for married taxpayers filing jointly). An additional 3.8% surtax on net investment income, including capital gains, helps fund Affordable Care Act benefits. This surtax applies to single taxpayers with incomes over $200,000 ($250,000 for married taxpayers filing jointly). In contrast to federal law, California taxes all capital gains as ordinary income, at a maximum rate of 13.3%.
[10] As described by the Urban Displacement Project, gentrification is “a process of neighborhood change that includes economic change in a historically disinvested neighborhood — by means of real estate investment and new higher-income residents moving in — as well as demographic change — not only in terms of income level, but also in terms of changes in the education level or racial make-up of residents.” Gentrification can lead to displacement, meaning long-term community residents are no longer able to live in gentrified communities. See Miriam Zuk and Karen Chapple, “Gentrification Explained” (Urban Displacement Project: 2015).
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
This website uses cookies to analyze site traffic and to allow users to complete forms on the site. The California Budget & Policy Center does not share, trade, sell, or otherwise disclose personal information. By using our website you agree to our Privacy Policy.