Skip to content

key takeaway

Prop. 40 would institute a one-time 5% tax on the wealth of billionaires to raise tens of billions in temporary revenue to address the loss of federal funding and other threats to health, nutrition, and education services, largely a result of H.R. 1 — the 2025 budget reconciliation law known as the “One Big Beautiful Bill Act.” Prop. 40 could potentially raise tens of billions in revenue in the short-term to preserve critical services, but may also lead to some income tax revenue losses in future years to the extent that billionaires leave the state to avoid the tax.

Background

California, like many other states, is facing a number of challenges to its ability to meet the needs of its residents, including the impending impacts of the deep federal cuts to public health care and nutrition assistance and the rising costs of providing services due to inflation, an aging population with more complex needs, and the state’s ongoing housing crisis. The federal cuts to Medi-Cal alone are expected to cost the state tens of billions of dollars in lost funding and could lead to around 1.3 million Californians losing health care access by 2029-30. Meaningfully addressing these challenges will require California to raise a substantial amount of revenue.

what is h.r. 1?

H.R. 1, the 2025 budget reconciliation law known as the “One Big Beautiful Bill Act,” signed by President Trump on July 4, 2025, will deeply harm Californians by cutting funding for essential health care and food assistance programs — while providing massive tax breaks to the wealthy and corporations. The spending cuts will disproportionately impact families with low incomes, immigrants, and communities of color, pushing more people into poverty and widening racial and economic inequities across the state.

Even prior to these more recent challenges, California was not generating enough revenue to meet the critical needs of all Californians through the state’s communities, evidenced by the state’s poverty rate remaining the highest in the nation. In addition to the human suffering caused by failing to ensure Californians can regularly access health care, put enough food on the table, and meet their other basic needs, such a failure dampens the state economy by preventing some individuals from fully participating in it and puts fiscal pressures on state and local governments as more households are forced to turn to costly emergency services and systems of last resort.

In the near term, Prop. 40 would likely generate tens of billions in revenue to prevent health coverage losses for Californians and stabilize the state’s health care system, and could provide additional support for nutrition assistance — which is also impacted by federal cuts — and for public education. Because the revenues would be one-time, the state would not be able to maintain these services in the future unless federal funding were fully restored or the state adopted alternative sources to raise this magnitude of revenue.

There is a strong rationale for taxing accumulated wealth — or taxing increases in wealth that currently go untaxed — given the profound wealth inequality and the vast unmet needs that exist in the state and across the country, as well as the ability of some ultrawealthy households to pay very little in income taxes as a share of their wealth.

At the same time, taxing wealth at the state level comes with some risks, particularly the potential for wealthy people to leave the state to avoid the tax, which would result in future state income tax losses if they did not return — putting at risk future funding for critical state services — and potential unknown impacts on the state economy. Prop. 40 attempts to counter that risk by applying the tax to billionaires who were California residents at the beginning of 2026, however it is likely this will be challenged in courts and the outcome is not certain.

In November, California voters will need to weigh the potential benefits of Prop. 40 against its potential tradeoffs.

Who Would Be Subject to the Tax Under Prop. 40 and How Would It Be Calculated?

Prop. 40 would institute a one-time tax on the worldwide wealth of billionaires. For the purposes of the measure, a billionaire subject to the tax could be an individual, a married couple, or a trust with net worth — as defined by the measure — above $1 billion. There are around 250 billionaires in California, with over $2 trillion in total wealth.1Forbes tracks the daily wealth of billionaires with its “Real-Time Billionaires” list, and the California-specific data was compiled in connection with Jasper Boll, Emmanuel Saez, and Gabriel Zucman, California Billionaires: Wealth, Taxes, and Wealth Tax Revenue Estimates (NBER Working Paper 35218, May 2026). Note: Saez is an author of Prop. 40.

The tax rate would be 5% for most billionaires, but the rate would be phased in for those with net worth between $1 billion and $1.1 billion.2Specifically, the 5% rate would be reduced by 0.1 percentage point for each $2 million that the household’s net worth falls below $1.1 billion. Taxpayers would have the option of paying the full amount of the tax with their 2026 tax returns or in installments across five years, with an annual deferral charge.

Net worth is typically calculated as the total value of assets held by an individual, couple, or family minus their total debts. However, Prop. 40 allows some exclusions from the net worth calculation, including:

  • Real property holdings, which are subject to constitutional tax limitations due to Proposition 13, approved by California voters in 1978;
  • Tangible personal property — such as vehicles, jewelry, appliances, or business equipment — held outside of California;3Tangible personal property is excluded from the net worth calculation if it is held outside of California for at least 270 days during 2026 unless it was temporarily relocated for the purpose of tax avoidance. and
  • Certain pensions, retirement accounts, and deferred compensation arrangements.

The measure would apply the tax to billionaires who were California residents on January 1, 2026, and the amounts subject to the tax would be determined based on their net worth on December 31, 2026. There will likely be legal challenges to the application of the tax based on residency prior to the enactment of the tax. Federal and state tax measures often have retroactivity provisions to minimize tax avoidance and courts have upheld many of these laws, although it is unknown how courts would ultimately rule on this measure. The measure specifies that in the case the residency and valuation dates are invalidated by courts, these dates shall be construed to be the earliest dates consistent with law.

Prop. 40 establishes procedures for estimating the value of various types of assets that would be included in net worth for the purpose of the tax. Valuation is simple for some assets, such as holdings of publicly traded stock, which have a known market value at any given time. Other assets, such as shares of private businesses, intellectual property such as copyrights or trademarks, and artwork, are more difficult to value without a sale taking place. The measure has detailed valuation rules and formulas for different types of assets, and both the taxpayer and the state’s Franchise Tax Board — which would be responsible for administering the tax — could obtain certified appraisals in the case of valuation disputes. Additionally, the measure contains provisions intended to minimize the ability of taxpayers to avoid or evade their tax responsibility.4Tax avoidance reflects legal avenues to reducing tax liability, such as redirecting wealth holdings to exempted assets or relocating, whereas tax evasion encompasses illegal tactics to avoid taxes, such as hiding assets in tax havens, underreporting of asset values, or falsely claiming residency outside of the tax jurisdiction.

Example: Potential Impact of Prop. 40 on Mark Zuckerberg

Mark Zuckerberg, cofounder of Facebook, has a net worth of around $200 billion.  Assuming he has approximately $200 billion in wealth subject to Prop. 40 on December 31, 2026, when net worth is to be determined for the purpose of the measure, he would owe around $10 billion in tax, which he could pay in five annual installments of $2 billion. His remaining wealth of around $190 billion would still be more than the entire economies of dozens of countries, roughly on par with the Gross Domestic Product of Morocco.

For comparison, Zuckerberg’s net worth increased 175% from 2023 to 2024 according to Forbes data, from $64.4 billion to $177 billion.

What Is the Difference Between Income and Wealth?
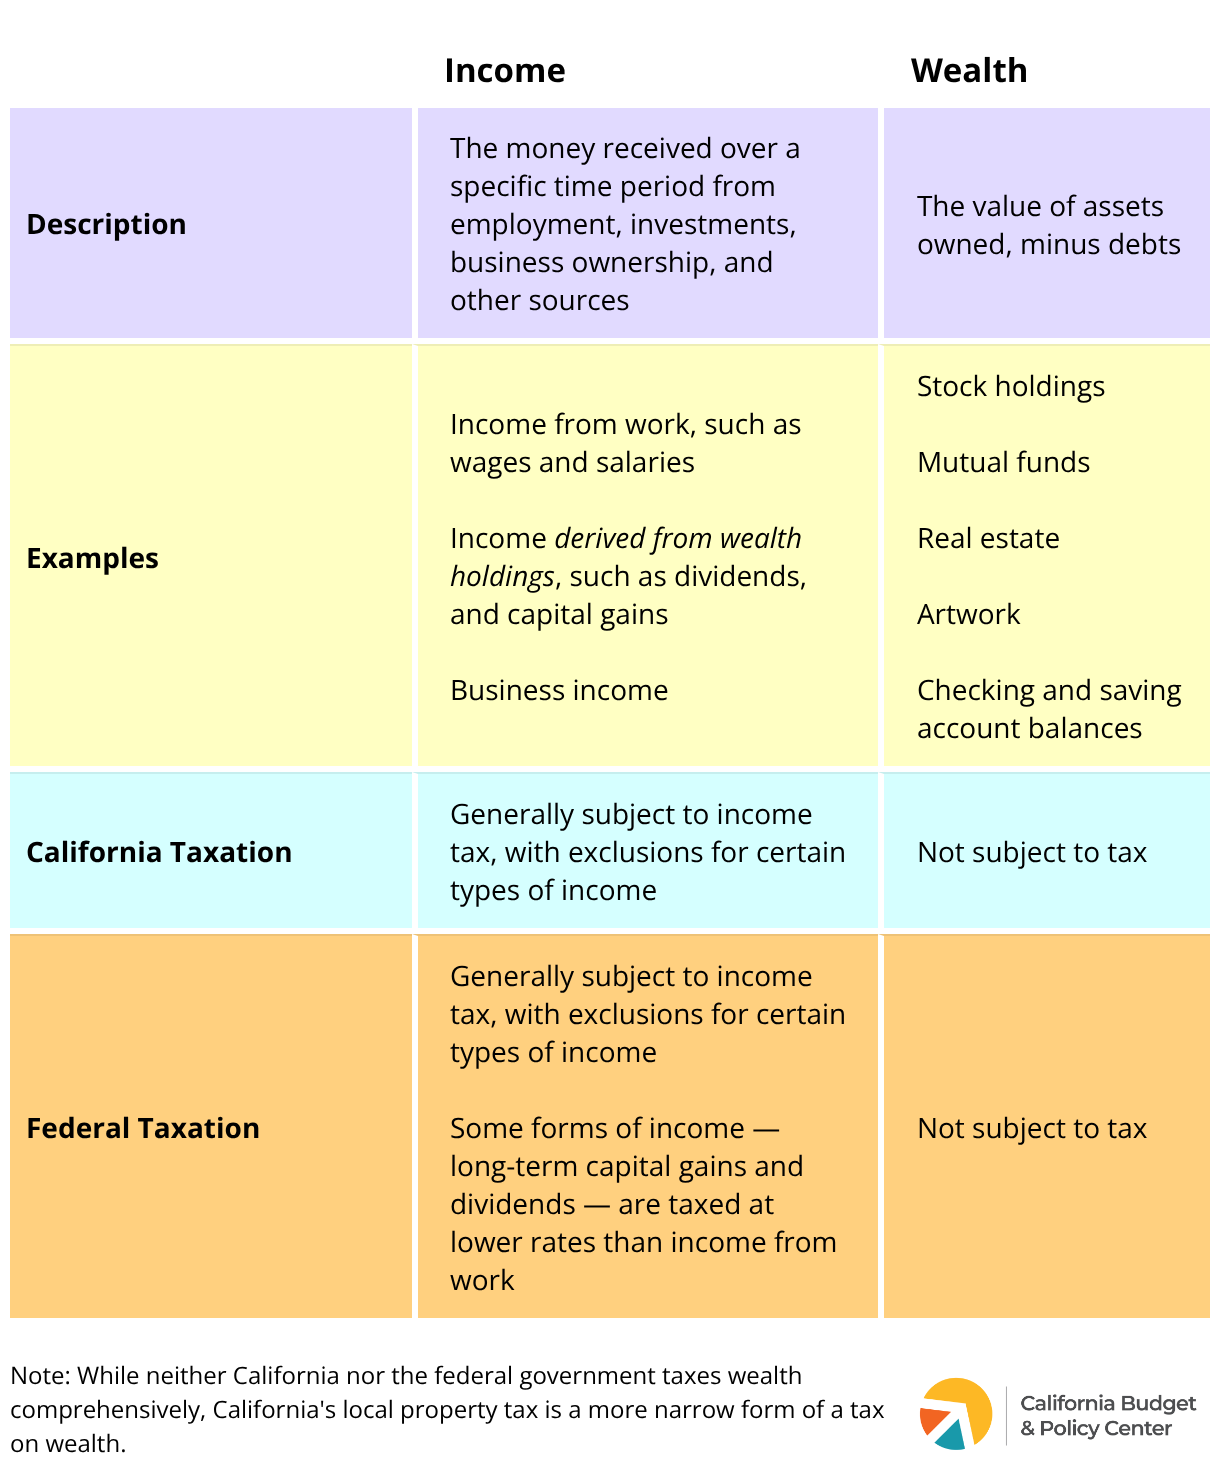
Capital Gains: Increases in Wealth

Households holding assets that have increased in value pay federal and state tax on those gains only when they sell those assets. This is known as a realized capital gain.

However, the value of an asset can grow exponentially and go untaxed as long as it is held onto — an unrealized capital gain. While the household doesn’t directly receive the proceeds from the gain until selling the asset, unrealized capital gains represent an increase in the household’s wealth and financial well-being.

For ultra-wealthy households, unrealized capital gains make up a large share of their total wealth.5For example, the Institute on Taxation and Economic Policy estimated that unrealized capital gains represent nearly 70% of total wealth for billionaires. In some cases, ultra-wealthy households — such as corporate founders — can avoid paying income taxes entirely in some years by not taking a salary, not selling any stocks or other assets, and simply borrowing against their wealth to pay their bills. There is evidence of some of the wealthiest Americans engaging in this behavior, detailed in analyses of leaked tax returns by investigative journalists, although recent research suggests that this is not a widespread phenomenon and that overall, wealthy households do have significant taxable income and their incomes allow them to cover their expenses while continuing to invest and grow their wealth.

Additionally, if someone holds onto assets until their death, their heirs do not have to pay any tax on the gain due to a provision in both federal and state law known as “stepped-up basis,” estimated to cost California around $5 billion each year.6Department of Finance, Tax Expenditure Report: 2025-26, p. 24. Note that the estimated annual cost of the provision is not equivalent to the revenue that could be generated from repealing it, and for this provision the revenue gains from repeal would start in the low hundreds of millions and increase with time, potentially reaching $5 billion annually in the future. Essentially, the combination of unrealized capital gains not being taxed and stepped-up basis results in some large wealth increases never being taxed.

How Is Wealth Distributed Across California?

Across the country, the gaps in income and wealth have steadily grown with the top 10% of households seeing substantial growth in both income and wealth accumulation. Similarly, in California, only a tiny fraction of the population benefits from extreme income and wealth.

While both wealth and income inequality are prevalent in the state, wealth is even more unequally distributed than income in California. While the state has more wealth than the rest of the country, the disparities in wealth are also starkest in California.

When focusing on the wealth distribution in the state, the data show an alarming gap between households with high and low wealth. Specifically, the wealthiest 20% of households have a net worth of over $1.5 million, while the bottom 20% of households have a net worth of $13,000 or less. Those who would be subject to the Prop. 40 tax — those with a net worth above $1 billion — have a net worth of over 3,000 times the median household.
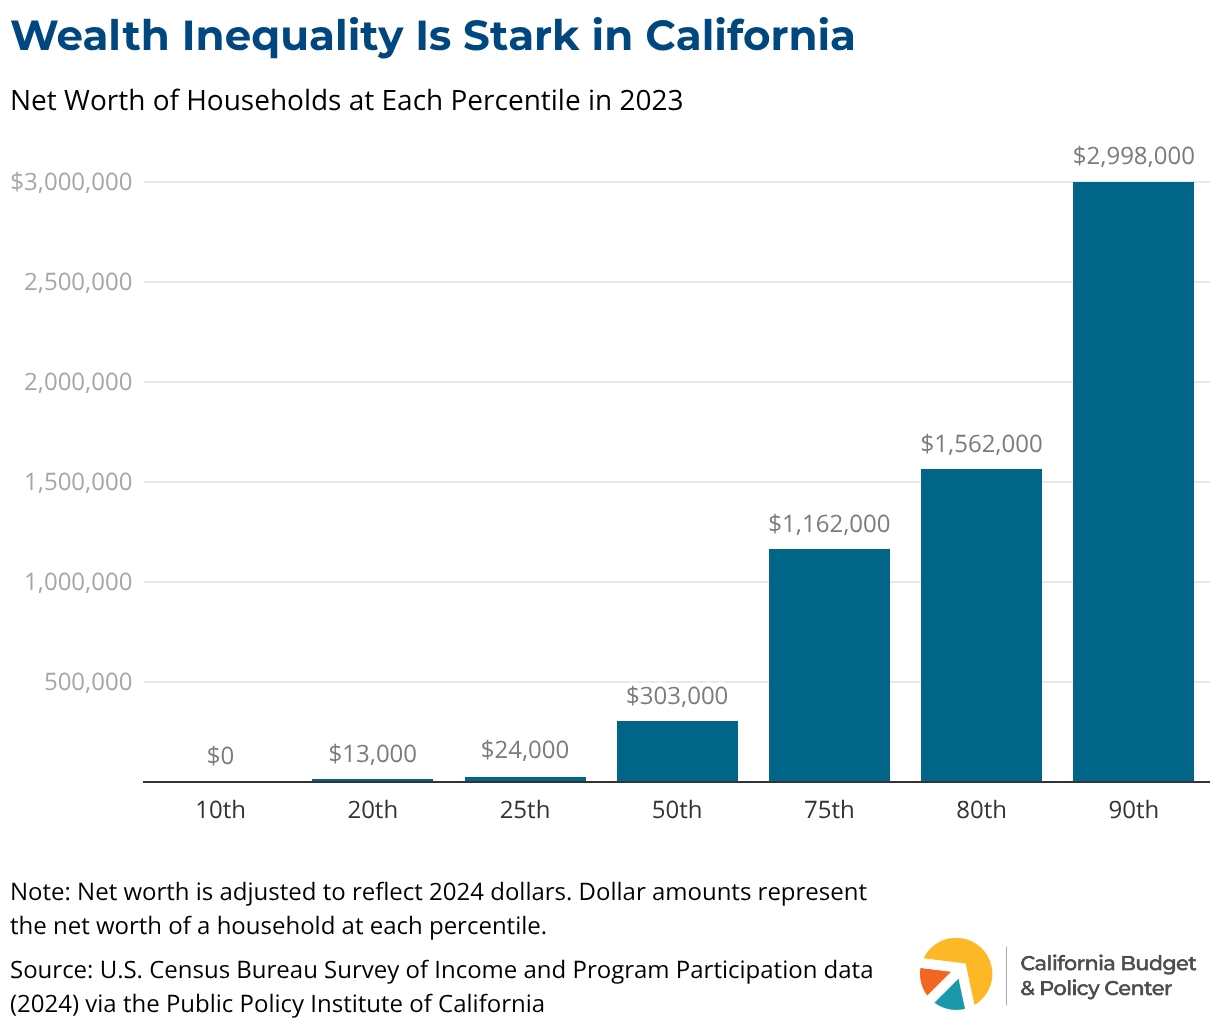
Wealth is also unequally distributed across racial and ethnic groups. For example, the median net worth of white households in 2023 was almost ten times the median net worth of Latinx households, reflecting the historical barriers to wealth accumulation these communities have faced. Black, Latinx, and other households of color often have less wealth due to many factors including a lower likelihood of owning stocks, occupational segregation pushing them into lower-payer jobs, and a lack of inherited generational wealth. These factors likely contribute to the large wealth disparities that have persisted throughout history.

How Much Revenue Will Prop. 40 Raise?

There is a high degree of uncertainty in estimating the potential revenue from this measure since it is impossible to accurately predict how billionaires and the courts will respond to the tax. It is likely there will be some avoidance and evasion of the tax, as billionaires may hide or underreport their assets, shift their asset holdings toward those that are exempt from the tax, attempt to sever their ties with California, or engage in other tactics to minimize or eliminate their tax liability.

After attempting to account for these factors, the Legislative Analyst’s Office estimates that the billionaire tax would likely raise “tens of billions” of dollars in the near term. It also suggests there could be some ongoing reductions in state income tax collections in the future — likely less than $1 billion per year — depending on the extent to which billionaires leave the state and no longer pay California tax on their income.

Authors of Prop. 40 estimate that the measure could raise around $100 billion over five years, after assuming that 10% of the potential tax base would be eroded due to avoidance and evasion. They assume a relatively low avoidance and evasion rate due to the one-time nature of the tax and its retroactive residency date as well as the inclusion of provisions in the measure intended to safeguard against the avoidance and evasion strategies seen with wealth taxes implemented in other countries, such as allowing fewer exemptions for certain asset types and applying the tax to trusts as well as individuals.

In contrast, researchers at the conservative-leaning Hoover Institution estimate the initial revenue gain might be closer to $40 billion, a still significant amount.

The large difference between estimates lies mainly in different assumptions about how many billionaires have or will successfully sever their residency ties with California to avoid the tax. The potential for migration and other avoidance efforts related to the measure and their implications are discussed below.

What Would Prop. 40 Funds Pay For?

All the revenue from the Billionaire Tax Act is intended to mitigate the harm from federal and state-level cuts to health care, food assistance, and K-14 public education programs. The measure would create a special fund — the 2026 Billionaire Tax Reserve Fund — to hold the revenue.

Revenues in the fund — after accounting for the costs incurred by the Franchise Tax Board to administer the tax — would be split between two subaccounts, with 90% of revenue going into the Billionaire Tax Health Account and 10% going into the Billionaire Tax Education and Food Assistance Account.

Because the measure does not contain specific requirements as to how the dollars within each fund must be spent, beyond being used for “health care funding” and “education-related and food assistance expenditures,” policymakers would have fairly broad authority to determine the allocation of funding within those categories. However, the measure specifies that funds may not be used to replace existing state funds for health care, education, or food assistance.

Additionally, each subaccount has a limit for how much can be appropriated in a fiscal year. The health subaccount has an appropriation limit of $22.5 billion per fiscal year, and the education and food assistance account has a limit of $2.5 billion per fiscal year. The entire amount does not have to be allocated each year and funds can be retained if determined necessary.

Prop. 40 specifies that the revenue generated by the billionaire tax would be excluded from three spending requirements in the state Constitution:

How Would Prop. 40 Revenues Impact Californians?

The majority of the revenues from the Billionaire Tax Act would directly support Californians who are harmed by federal and state cuts to the Medi-Cal and CalFresh programs.

H.R.1 is estimated to result in around 1.3 million Californians losing Medi-Cal coverage by 2029-30 and tens of billions of dollars in lost federal funding every year. These provisions target a wide range of populations including, but not limited to, immigrant Californians and low-income adults without dependents. Policy changes impacting these populations include increasing eligibility checks for Medi-Cal, imposing ineffective work reporting requirements, and limiting retroactive coverage for adults. Federal policy changes, including provisions of H.R. 1 and the expiration of enhanced premium tax credits, could also result in around 400,000 to 500,000 fewer Californians receiving health coverage through Covered California — the state’s health insurance marketplace established through the Affordable Care Act. The revenue from Prop. 40 could help mitigate some of the harms of these federal policies, for instance by replacing some lost federal funding and providing counties with additional resources to administer Medi-Cal and help eligible Californians maintain coverage.

This measure could also allocate funding to counteract the harmful enacted provisions from recent state budget packages that further harm Medi-Cal recipients. In combination with the federal cuts, state policy changes like freezing Medi-Cal enrollment for certain undocumented adults, imposing burdensome monthly premiums, reinstating the Medi-Cal asset limit, and denying full-scope Medi-Cal to certain immigrants could nearly double the uninsured rate to 14.7% by 2030.

A smaller proportion of the revenue could also go towards offsetting H.R.1’s harmful cuts to CalFresh. H.R.1 puts more than 3 million households at risk of losing some or all of their food assistance and could cost California between $2.3 billion and $5.1 billion annually.  The provisions include applying time limits to previously exempt populations like veterans, older adults, and former foster youth and eliminating CalFresh for tens of thousands of lawfully present immigrants.

The Prop. 40 revenues could also help sustain and support funding for public education which has been facing federal threats such as funding freezes, grant cancellations, and proposed budget cuts. Public education would receive less support under the measure than if the revenues were allocated to the General Fund — due to the Prop. 98 minimum funding guarantee — but that would also mean less funding available for health care and food assistance. Additionally, because the measure does not require any specific share of funding in the Billionaire Tax Education and Food Assistance Account to go to any of the specified allowable uses, it is possible that all of these funds would be used to support food assistance and none for education — or alternatively, all of the funds could go to education and none to food assistance. Again, policymakers would have significant flexibility in allocating the dollars in this fund to specific programs that align with the intended purposes of the fund.

What Are the Concerns About Prop. 40?

Prop. 40 Would Provide One-Time Revenues to Respond to Ongoing Federal Funding Losses

While the revenue that would be generated by Prop. 40 is mainly intended to address the harms of the federal cuts to health care and food assistance resulting from H.R. 1 and other federal threats, the revenue from this one-time tax would only be available for a few years. If the federal government does not reverse those deep cuts within the next several years, the state will again be presented with the choice of cutting services and letting Californians impacted by federal cuts fall through the cracks or finding new alternative revenue sources to help keep them afloat.

The Revenue from Prop. 40 Would Not Be Available to Support Other Core State Services

Because the revenue would be earmarked, state programs and services that help Californians — beyond health care, food assistance, and education — would not receive any of the one-time revenue under Prop. 40. For example, none of the revenue would be available to support other critical needs such as affordable housing and renter supports, homelessness response, subsidized child care, or other safety net programs. As noted above, because the measure does not specify how the funds in the Education and Food Assistance Account would be allocated, it is possible that the funds could be used only for food assistance or only for education, so there is no guarantee that funding is allocated for both of these purposes.

On one hand, there is a clear need for increased health care funding to respond to the dramatic federal cuts that could strip millions of Californians of their health insurance and put immense strain on health clinics and hospitals, particularly in rural areas. This need supports the rationale for dedicating the vast majority of the revenue to health care programs.

On the other hand, Californians facing barriers to economic security have many critical needs, and the state has long underinvested in meeting those needs. New revenues are essential to protect and expand vital state services — including services beyond what Prop. 40 revenues are allowed to fund. If the revenues from a new tax on wealth went into the state’s General Fund, policymakers would have the flexibility to deliberate and decide how to allocate funding to address the most pressing and changing needs of Californians.

There Are Uncertain Impacts of a State-Level Wealth Tax on the State’s Longer-Term Budget and Economy

Imposing a state tax on wealth for a small share of the population is a novel and untested approach in the United States, and novel approaches always come with some risks. Concerns have often been raised about the potential impacts of such a tax on the behavior of the ultra-wealthy: the extent to which they will engage in tax avoidance behaviors that have consequences for the state. The majority of these concerns focus on the risk that billionaires will leave the state to avoid the tax, which would lead to some loss of future income tax revenues from those households if they do not return later. A related concern often raised is how these potential migration impacts could affect the state’s economy if wealthy business founders/owners choose to relocate some of their business activities or if future company founders opt to start businesses in another state for fear of a future wealth tax.

While a significant outmigration of billionaires could reduce the one-time revenue yield from the billionaire tax, the bigger concern for the state is the potential impact on ongoing state income tax revenues, which could put a strain on the state budget in the future. The outcome here is also uncertain. The income taxes paid by billionaires are very small relative to their overall wealth, and some billionaires can essentially avoid income taxes entirely in some years by not selling any assets or receiving a salary. For example, researchers — including an author of Prop. 40 — examined public data reported to the US Securities and Exchange Commission and found that Google founders Larry Page and Sergey Brin did not sell stock, receive dividends, or take any compensation related to Alphabet (Google’s parent company) in 2019, 2020, or 2023, so they likely would not have paid any income taxes related to their Alphabet holdings or involvement. Additionally, it is not clear that migration and income tax losses would be permanent in response to a one-time tax.

Prop. 40 aims to address the potential concerns about migration by applying  the wealth tax to billionaires who were California residents as of January 1, 2026. This retroactive residency date is likely to be challenged in court. However, if it is upheld, any billionaire leaving after this date would not be able to avoid the tax. Additionally, even billionaires who announced moves out of California before this date may not have sufficiently severed their residency with the state for tax purposes, as the state’s Franchise Tax Board considers many factors when verifying residency status beyond simply whether a filer claims to be resident of another state or has purchased property in another state.

There is no way to accurately predict how billionaires would respond to the tax — or the prospect of being subject to the tax, as there is uncertainty about whether the measure will be approved by voters and whether the retroactive residency date will be upheld. There is a body of research on how income and wealth tax policies may impact interstate and international mobility of taxpayers, but the findings vary widely depending on the geographical scope, the type and magnitude of the tax change, the population impacted, the data available, and the research methodology.7For a summary of research focused on the mobility of high-income and high-wealth households in response to income and wealth taxes, see Fernando Rodrigo Sauco, “Millionaires on the Run? Taxation of the Rich and Induced Mobility: A Literature Review,” Hacienda Pública Española/Review of Public Economics 253, no. 2 (June 2025): 91-127.

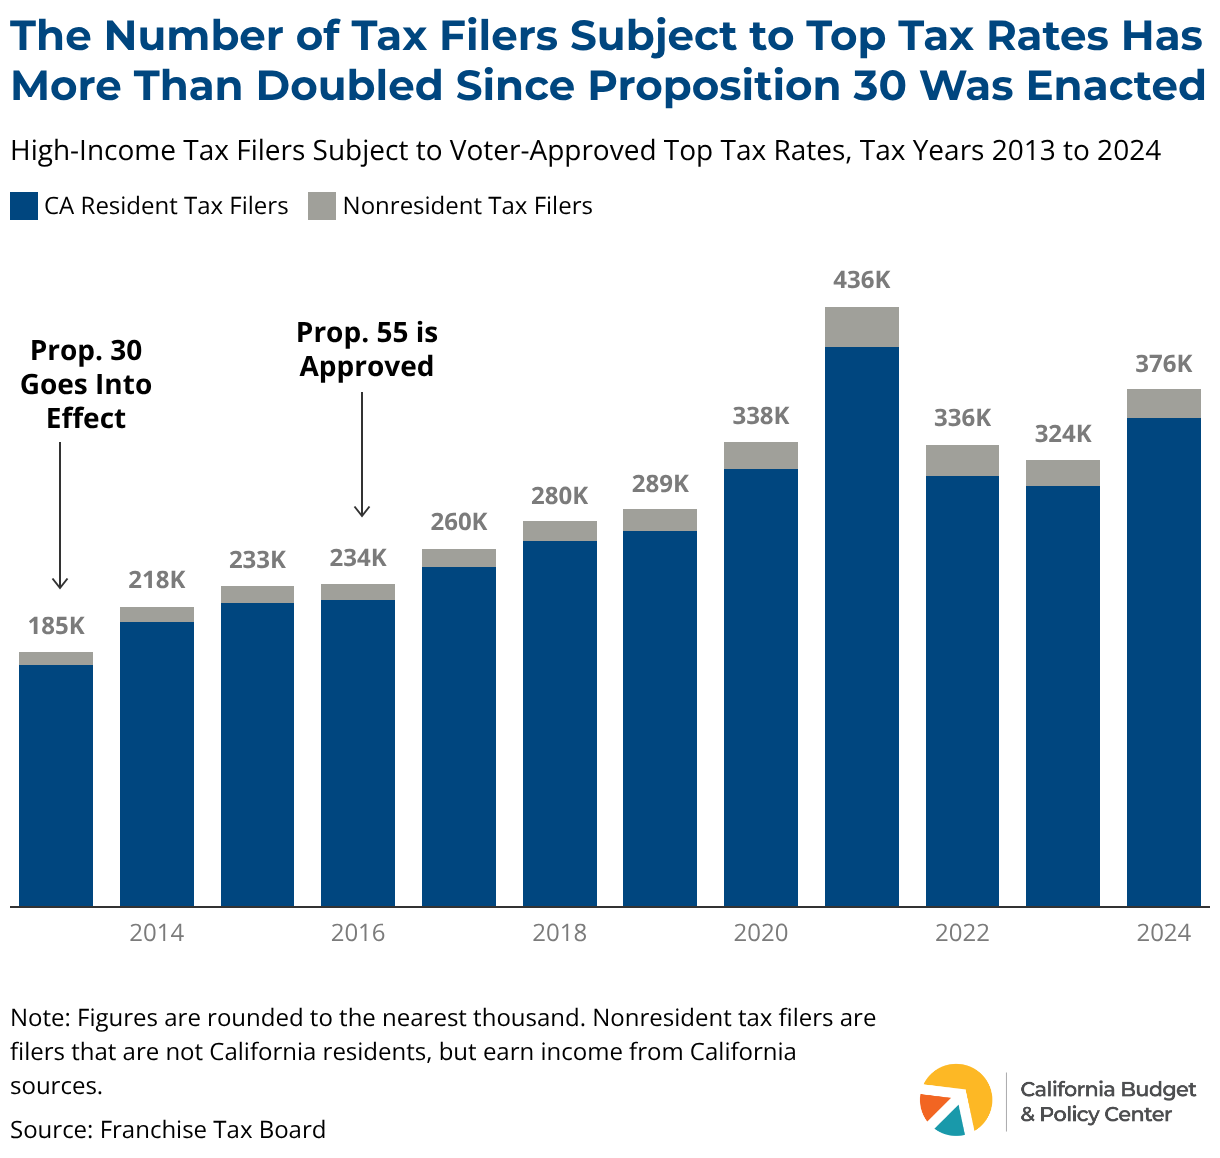
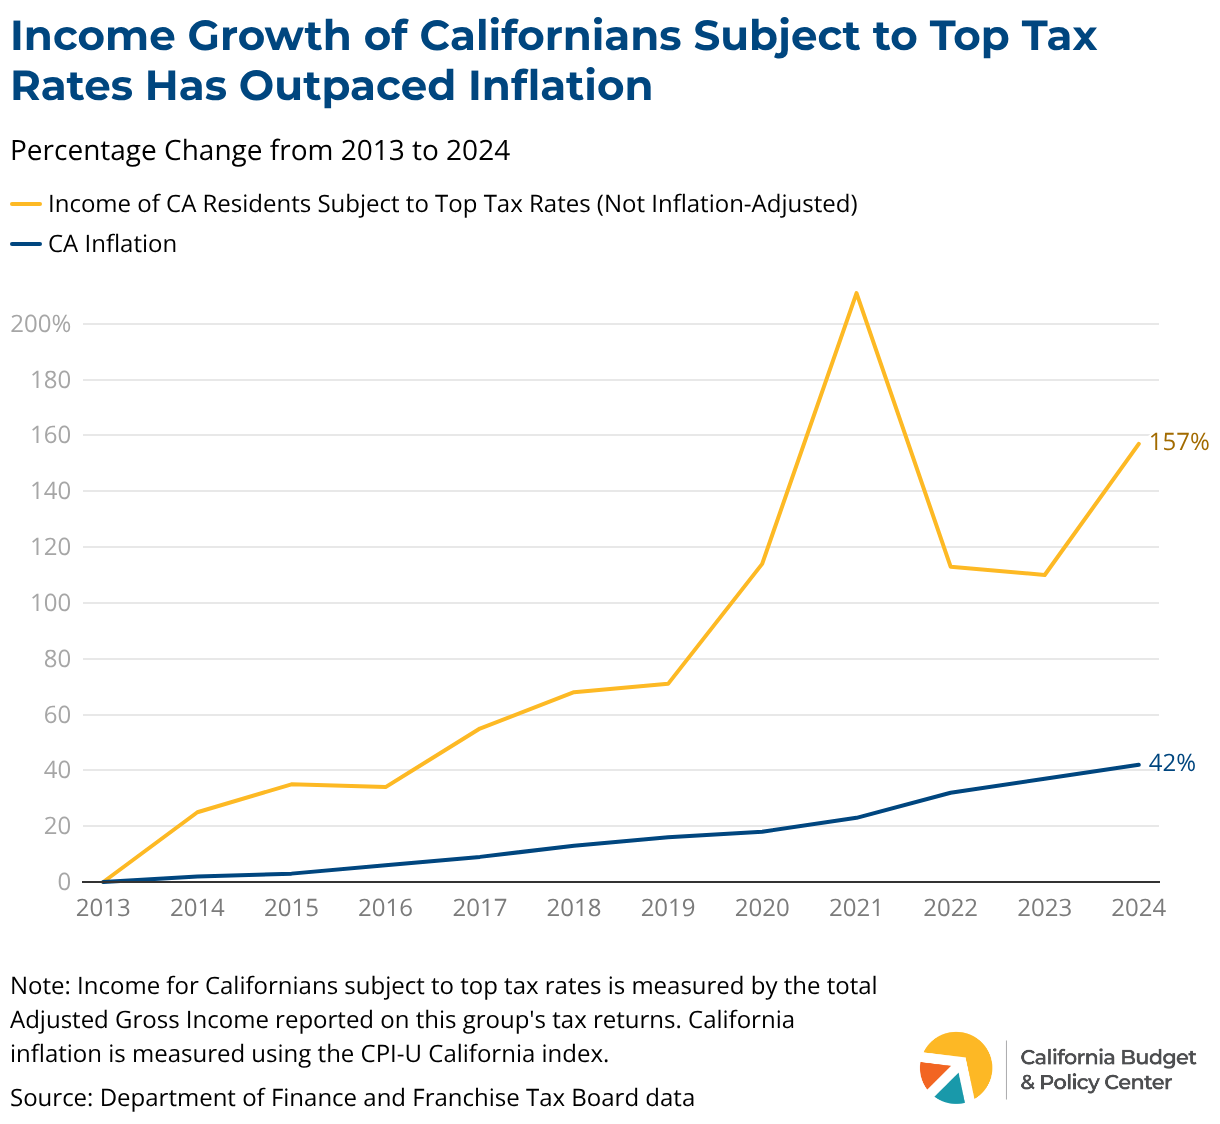
Research on the impacts of state-level income taxes on interstate migration has generally found very minor effects on the numbers of high-income people in a state relative to the state’s total population of high-income people.8While some studies have found statistically significant effects of taxes on migration rates among high-income tax filers, this translates to small changes in the stock of high-income people in a state. For example, Young et al. (2016) examined federal tax return data for all tax filers with incomes of at least $1 million across all states for 1999 to 2011 and estimated that a one percentage point increase in the income tax rates is associated with an 8% reduction in the net migration flows into the state — people moving in minus people moving out — but this only translates to only a 0.1% change in the population of millionaires. They also find that while millionaires are somewhat more sensitive to tax rates than the general population, they are also less likely to move between states overall. Rauh and Shyu (2024) examined the impacts of California’s income tax increases on high-income households enacted by Prop. 30 (2012) and estimated that the the tax increase was associated with a one-time increase in the outmigration rate of top-tax bracket filers of 0.8% — translating to around 535 out of the nearly 67,000 tax filers in the new top tax bracket. Notably, since the enactment of these top tax rates established by Prop. 30 and extended by Prop. 55 (2016), the numbers of tax filers with incomes placing them in these top tax brackets has grown significantly, along with the incomes of this group and the state revenue collections from the top rates. Additionally, there is evidence that state differences in tax rates have more significant effects on the choice of location among movers than on the probability of moving. For example, a study by Young and Lurie (2025) suggests millionaires in higher-tax states were no more likely to move than the general public in response to a 2017 federal tax change that impacted higher-income taxpayers in higher-tax states, but those that did move were more likely to move to lower-tax states. While taxes may be one factor in where people decide to live, they are one of many, and they may not outweigh other factors such as professional and family considerations, public amenities, weather, and lifestyle preferences. Indeed, survey data from the US Census Bureau show that the vast majority of people moving between states move for job or family reasons. Some research also finds that high-income people are generally less likely to move between states than the general population and are more embedded in their communities due to family, social, and business connections — they are more likely to be married, have children, and own businesses.9Young and Lurie (2025) did find an elevated migration of millionaires out of higher-tax states during the COVID pandemic when in-person social and business networks were disrupted, but this effect had generally subsided by the beginning of 2023.

However, the impact of a wealth tax on California billionaires may be different than the impact of income taxes on high-income households. There are no direct parallels to draw on, as no state has enacted this type of tax, and most wealth taxes in other countries have been imposed at the national level and applied to a broader segment of the population. These other wealth taxes have had substantial differences in design — including the tax rates, exemptions for specific types of assets, and the wealth thresholds above which the tax applies — as well as enforcement capacity. All of these factors can influence the impact of the tax, so the findings on migration and other avoidance behaviors are not uniform across studies of different wealth taxes and may not be directly relevant to the potential impact of a California billionaire tax.

Several countries, mainly in Europe, have levied taxes on their residents’ net worth in the past, but most have since repealed them. Among high-income countries — members of the Organization for Economic Cooperation and Development (OECD) — four currently impose taxes on wealth: Colombia, Norway, Spain, and Switzerland. This is down from 12 OECD countries with wealth taxes in 1990. A few other countries still have fairly comprehensive taxes on wealth — including Argentina (althougFor example, the Spain wealth tax study did find higher responses for people in higher wealth tax brackets, and a study on the impact of state-level estate taxes — essentially a one-time wealth tax levied when someone dies — on the state residence of US billionaires in the Forbes 400 found this population to be quite sensitive to the presence of an estate tax. However, this finding may not extend to a one-time wealth tax given that people are more likely to be mobile after retirement and may factor estate planning into their location decisions — and the estate tax study did find a stronger response for older billionaires.h this tax is being phased down), Bolivia, Uruguay — and additional countries including Belgium and Italy have taxes on the value of narrower categories of assets.10Washington State Department of Revenue, Wealth Tax Study Report (November 2024); PwC, Worldwide Tax Summaries: Net wealth/worth tax rates (Accessed July 6, 2026). Italy levies a 0.2% tax on foreign financial assets, and Belgium levies a 0.15% tax on securities accounts of at least 1 million euros.

Studies on wealth taxes in Spain and Switzerland — the only countries that have subnational wealth tax regimes instead of uniform national wealth taxes — found migration responses related to variation in tax rates between regions. The studies estimate that a one percentage point change in a wealth tax rate was associated with a change of around 8% to 10% in the population impacted by the tax. If billionaires in California had a similar response, a 5% wealth tax could result in substantial outmigration.

However, there are some caveats to extrapolating these findings — beyond the retroactive residency provision in Prop. 40 that may render billionaire outmigration after January 1, 2026 moot for the purpose of the tax. The subdivisions of Spain and Switzerland are much smaller than California, the taxes are ongoing instead of one-time, they are present across most or all regions of the countries, and they apply to a much broader population than billionaires — these factors could pull in opposite directions with regard to the applicability of these findings. It is also likely that some of the reported residence changes are fraudulent. Researchers found some suggestive evidence that false residency changes — such as a taxpayer claiming that a second home is their primary home —  are responsible for some of the effect in Spain. The prevalence of this phenomenon could be limited with adequate enforcement.

There is a possibility that wealthier people are more likely to move in response to taxes, which would have implications for a tax specifically targeted to billionaires.

For example, the Spain wealth tax study did find higher responses for people in higher wealth tax brackets, and a study on the impact of state-level estate taxes — essentially a one-time wealth tax levied when someone dies — on the state residence of US billionaires in the Forbes 400 found this population to be quite sensitive to the presence of an estate tax.11Note that this finding is specific to the ultra-wealthy Forbes 400 group, so it cannot be generalized to a broader group of wealthy households. Previous research examining the effect of estate and inheritance taxes on state migration rates of older adults and the locations of wealthy older adults estimated insignificant or modest effects. However, this finding may not extend to a one-time wealth tax given that people are more likely to be mobile after retirement and may factor estate planning into their location decisions — and the estate tax study did find a stronger response for older billionaires.

There is limited research on the overall economic impacts of wealth taxes. One recent study on now-repealed national-level wealth taxes in Sweden and Denmark — looking at the effects of tax reductions and repeals — estimated that a one percentage point increase in top wealth tax rates decreases the number of wealthy taxpayers in the country by about 2%, and because the wealthy are disproportionately business owners, there are some broader economic impacts. However, the estimated effects were very modest, as a large portion of business activity lost due to the outmigration of business owners is absorbed by other remaining businesses. Again, the differences in geography, nature of the tax changes studied (tax cuts versus tax increases), and the fact that these were recurring rather than one-time taxes mean that these findings may not be generalizable to a one-time state-level tax.

Research on one-time or temporary wealth taxes is limited. Several countries in Europe enacted national-level, short-term wealth taxes in the wake of WWI and WWII, and some levied narrow temporary taxes targeting wealth holdings after the Great Recession, with varying levels of success depending on the circumstances. The vast differences in historical context, geographic focus, and design elements — such as tax rates, payment periods, exemption levels, and assets targeted — make these experiences not particularly relevant comparisons for the Prop. 40 proposal, and there has not been empirical research on the migration or general economic impacts of these temporary taxes.

In sum, although existing research can provide some insights into the potential impacts of a one-time California billionaire wealth tax, there are many unknowns given the unique nature of the proposal. Additionally, the findings from research on tax policy impacts may not always identify causality or precisely measure effects due to the many potential confounding factors. Finally, even if effects are precisely measured, the research attempts to isolate the effects of tax policies holding all else equal, when in the real world there are a variety of factors influencing location decisions beyond taxes. Ultimately, California voters will need to decide if the benefits of the revenue generated by a tax on billionaires outweigh the concerns about the uncertain future fiscal and economic effects.

How Do Props. 41 and 42 Conflict With Prop. 40 on the November Ballot?

Two other constitutional amendment measures appearing on the November ballot, Prop. 41 and Prop. 42, contain provisions that conflict with Prop. 40 and could invalidate it in part or in full if they receive more votes. These measures could also make it harder to raise state revenues in the future to invest in the well-being of Californians, which could result in cuts to essential services that Californians want and need.

What is Proposition 41?

Prop. 41 would:

  • Require the State Auditor to conduct audits of programs that would receive revenue from new or higher special taxes, which are taxes that are dedicated to specific purposes rather than going into the state’s General Fund. This would include ongoing audits — every four years — of programs receiving funds from special taxes enacted on January 1, 2026 or later by either the Legislature or state voters. Additionally, pre-election audits would be required for programs that would receive revenues from a new or increased special tax that would appear on the statewide ballot. The pre-ballot and ongoing audits would be required to, among other things, contain recommendations on how the programs could reduce its costs by at least 10% annually. Policymakers would be under no obligation to implement these recommendations, but if they did, it could result in cuts to core services rather than simply “inefficient spending.”
  • Prohibit revenues raised by special taxes enacted since January 1, 2026 from being excluded from the state’s spending cap, also known as the “Gann Limit.” The measure also specifies that if another measure on the same ballot imposes a tax and exempts its revenues from the Gann Limit, the entirety of the other measure would be invalidated if Prop. 41 receives more votes. However, this would not prevent voters from approving future amendments to the state Constitution that would exclude certain tax revenues from the Gann Limit.

Because Prop. 40 would exclude the revenue generated by the billionaire tax from the Gann Limit, this is in direct conflict with Prop. 41. If both measures are approved, but Prop. 41 receives more votes, Prop. 40 could be invalidated. Alternatively, if both measures pass but Prop. 40 receives more votes, the billionaire tax could be collected, but it is possible that audits would be required of Medi-Cal and other programs receiving Prop. 40 dollars. If both measures pass, there may be litigation regarding the application of conflicting provisions, and the final decision would be made by the courts.

What is Proposition 42?

Prop. 42 would:

  • Prohibit the imposition of any new tax on the ownership of financial assets (such as bank accounts, stocks, bonds, or mutual funds), retirement accounts, interests in businesses, intellectual property, and other personal property (such as vehicles, jewelry, artwork, and other movable, physical property). Essentially, this would limit the taxation of assets to real estate assets, which are already subject to constitutional tax limitations under Prop. 13. However, if this measure is passed, it would not prevent voters from amending the state Constitution to tax any of these assets in the future, but state policymakers would not be able to enact taxes on any of the assets covered by Prop. 42 without voter approval.
  • Prohibit the imposition of new retroactive taxes, and in particular taxes based on residency prior to the effective date of the new tax — except in cases where the revenues would be used to respond to a governor-declared emergency and the tax does not apply retroactively for more than one year before the effective date. Once again, the approval of Prop. 42 would not impact the ability of voters to approve retroactive taxes in the future, but would impact state policymakers’ ability to do so. As noted above, many tax laws do have limited retroactivity periods — such as dating back to the beginning of a tax year — for several reasons, including preventing tax avoidance.

Both of these provisions conflict with Prop. 40, as the billionaire tax would apply to financial assets, business interests, and other personal property, and it would be retroactively based on the taxpayer’s residence as of January 1, 2026. If both measures pass and Prop. 42 receives more votes, Prop. 40 could be invalidated. If Prop. 40 receives more votes, the wealth tax could be collected, but Prop. 42’s tax restrictions would likely apply to future legislative tax proposals. Again, conflicts may ultimately be decided in courts if both measures pass.

The Bottom Line on Prop. 40

Prop. 40 is a bold proposal that would create a first-in-the-nation tax on wealth, raising significant — temporary — revenue by taxing the fortunes of California’s more than 250 billionaires. Proponents argue this unprecedented measure is needed to help offset deep federal cuts and protect health care, food assistance, and education for all Californians. Because a wealth tax is untested at a state level in the United States, it carries real uncertainty: courts may strike down the measure or portions of it, conflicting measures could lead to years of litigation, and no one can say how the location decisions of billionaires might change and what that would mean for California’s long-term finances. 

California voters will need to decide if the benefits of the revenue generated by a tax on billionaires outweigh the concerns about the uncertain future fiscal and economic effects of the billionaires tax.

Prop. 40 Supporters and Opponents

Prop. 40 is sponsored by Service Employees International Union — United Healthcare Workers West (SEIU-UHW), a local union representing health care workers. It has been endorsed by labor organizations including AFSCME California and Teamsters California, organizations including Our Revolution and California Democratic Socialists of America, and policymakers including US Senator Bernie Sanders, US Representative Ro Khanna, and State Superintendent of Public Instruction and former gubernatorial candidate Tony Thurmond.

Prop. 40 is opposed by labor organizations including the California Teachers Association and the State Building and Construction Trades Council of California, organizations including the California Business Roundtable, the California Medical Association, Planned Parenthood Affiliates of California, policymakers including Governor Gavin Newsom and US Representative Kevin Kiley, and gubernatorial candidates Xavier Becerra and Steve Hilton.

  • 1
    Forbes tracks the daily wealth of billionaires with its “Real-Time Billionaires” list, and the California-specific data was compiled in connection with Jasper Boll, Emmanuel Saez, and Gabriel Zucman, California Billionaires: Wealth, Taxes, and Wealth Tax Revenue Estimates (NBER Working Paper 35218, May 2026). Note: Saez is an author of Prop. 40.
  • 2
    Specifically, the 5% rate would be reduced by 0.1 percentage point for each $2 million that the household’s net worth falls below $1.1 billion.
  • 3
    Tangible personal property is excluded from the net worth calculation if it is held outside of California for at least 270 days during 2026 unless it was temporarily relocated for the purpose of tax avoidance.
  • 4
    Tax avoidance reflects legal avenues to reducing tax liability, such as redirecting wealth holdings to exempted assets or relocating, whereas tax evasion encompasses illegal tactics to avoid taxes, such as hiding assets in tax havens, underreporting of asset values, or falsely claiming residency outside of the tax jurisdiction.
  • 5
    For example, the Institute on Taxation and Economic Policy estimated that unrealized capital gains represent nearly 70% of total wealth for billionaires.
  • 6
    Department of Finance, Tax Expenditure Report: 2025-26, p. 24. Note that the estimated annual cost of the provision is not equivalent to the revenue that could be generated from repealing it, and for this provision the revenue gains from repeal would start in the low hundreds of millions and increase with time, potentially reaching $5 billion annually in the future.
  • 7
    For a summary of research focused on the mobility of high-income and high-wealth households in response to income and wealth taxes, see Fernando Rodrigo Sauco, “Millionaires on the Run? Taxation of the Rich and Induced Mobility: A Literature Review,” Hacienda Pública Española/Review of Public Economics 253, no. 2 (June 2025): 91-127.
  • 8
    While some studies have found statistically significant effects of taxes on migration rates among high-income tax filers, this translates to small changes in the stock of high-income people in a state. For example, Young et al. (2016) examined federal tax return data for all tax filers with incomes of at least $1 million across all states for 1999 to 2011 and estimated that a one percentage point increase in the income tax rates is associated with an 8% reduction in the net migration flows into the state — people moving in minus people moving out — but this only translates to only a 0.1% change in the population of millionaires. They also find that while millionaires are somewhat more sensitive to tax rates than the general population, they are also less likely to move between states overall. Rauh and Shyu (2024) examined the impacts of California’s income tax increases on high-income households enacted by Prop. 30 (2012) and estimated that the the tax increase was associated with a one-time increase in the outmigration rate of top-tax bracket filers of 0.8% — translating to around 535 out of the nearly 67,000 tax filers in the new top tax bracket. Notably, since the enactment of these top tax rates established by Prop. 30 and extended by Prop. 55 (2016), the numbers of tax filers with incomes placing them in these top tax brackets has grown significantly, along with the incomes of this group and the state revenue collections from the top rates. Additionally, there is evidence that state differences in tax rates have more significant effects on the choice of location among movers than on the probability of moving. For example, a study by Young and Lurie (2025) suggests millionaires in higher-tax states were no more likely to move than the general public in response to a 2017 federal tax change that impacted higher-income taxpayers in higher-tax states, but those that did move were more likely to move to lower-tax states.
  • 9
    Young and Lurie (2025) did find an elevated migration of millionaires out of higher-tax states during the COVID pandemic when in-person social and business networks were disrupted, but this effect had generally subsided by the beginning of 2023.
  • 10
    Washington State Department of Revenue, Wealth Tax Study Report (November 2024); PwC, Worldwide Tax Summaries: Net wealth/worth tax rates (Accessed July 6, 2026). Italy levies a 0.2% tax on foreign financial assets, and Belgium levies a 0.15% tax on securities accounts of at least 1 million euros.
  • 11
    Note that this finding is specific to the ultra-wealthy Forbes 400 group, so it cannot be generalized to a broader group of wealthy households. Previous research examining the effect of estate and inheritance taxes on state migration rates of older adults and the locations of wealthy older adults estimated insignificant or modest effects.

Stay in the know.

Join our email list!

key takeaway

Proposition 37 on the November 2026 ballot would establish a “middle-class” homebuyer downpayment assistance program, funded with up to $25 billion in revenue bonds. This assistance could only be used to purchase newly built homes or newly created housing units converted from nonresidential buildings, where the buyer is the first purchaser. The program is intended to be self-sustaining because participating homebuyers — not the state — would ultimately repay the bonds through their mortgage payments.

Supporting homeownership is an important strategy for promoting economic security and wealth building. However, it is unclear whether Prop. 37 would meaningfully help “middle class” Californians who face the greatest barriers to homeownership to afford a home.

As Prop. 37 would be financed through revenue bonds — which do not require voter approval — the program proposed by this initiative could have been enacted legislatively or a comparable program could have been established by the California Finance Housing Agency. Prop. 37 is a citizens’ initiative spearheaded by former California Senate Majority Leader and Assembly Speaker Bob Hertzberg.

What Would Prop. 37 Do?

The Middle Class Homeownership and Family Home Construction Act of 2026 would direct the California Housing Finance Agency (CalHFA) to establish a middle-class homebuyer downpayment assistance program, funded with up to $25 billion in revenue bonds. The new program would:

  • Provide up to 17% of the purchase price toward the down payment, which could only be used to purchase new homes or newly created housing units converted from nonresidential buildings, where the buyer is the first purchaser.
  • Require the buyer to put down at least 3% of the purchase price toward the down payment. Combined with the 17% state downpayment assistance, this would reach 20% of the home’s purchase price and eliminates the need for private mortgage insurance. A conventional first mortgage would cover the remaining amount.
  • Require the downpayment assistance to be provided as a loan, not a grant, which recipients are likely to pay back monthly as a fixed-rate second mortgage. This would be in addition to the homebuyer’s monthly payments on their conventional first mortgage.
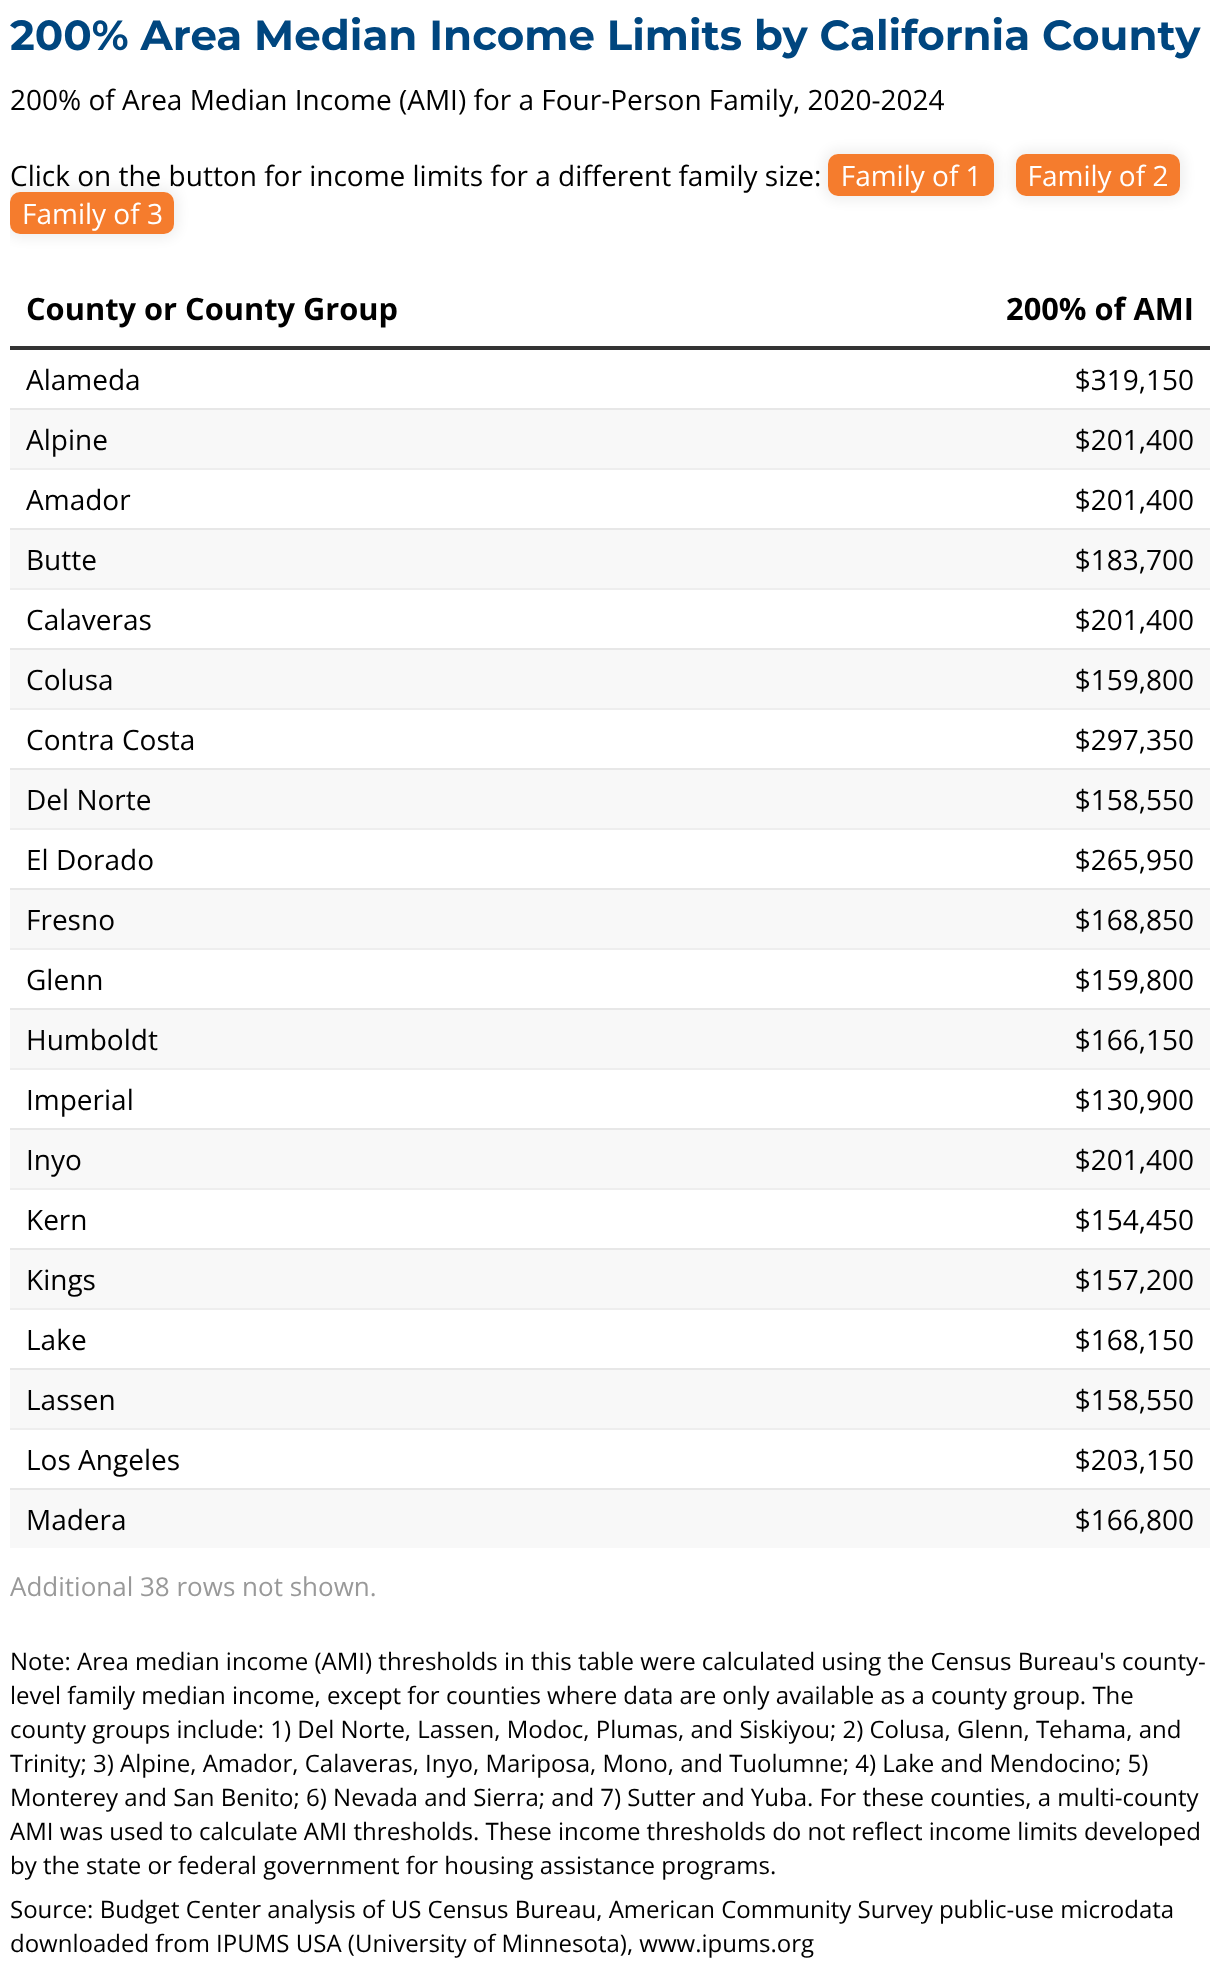
  • Allow applicants to have incomes up to 200% of the Area Median Income (AMI), which varies by region.
  • Cap the maximum home purchase price at roughly $1 million to $1.5 million, depending on the county and other factors. This is equivalent to a  $170,000-$255,000 downpayment assistance cap per home.
  • Not require applicants to be first-time or first-generation home buyers, nor would recipients owe the state any equity gained in their home. These are requirements of comparable state downpayment assistance programs the state currently operates.
  • Allow home builders to become “qualified builders,” and have their developments automatically qualify for the program if they meet specified labor and enforcement standards.

How Would Income Eligibility for Prop. 37’s Downpayment Assistance Vary Across California Counties?

Prop. 37 would make a broad group of Californians eligible for downpayment assistance by allowing family incomes not exceeding 200% of Area Median Income (AMI) to qualify, a threshold that extends well beyond established downpayment assistance programs.

AMI represents the midpoint of family incomes in a specific area, adjusted for household size. In other words, half of households in an area have incomes that exceed 100% AMI and half have incomes below that level, so 200% AMI is roughly double what a typical family makes in the area. The limit is tied to local incomes, so whether a family income would qualify for Prop. 37’s downpayment assistance would vary significantly across California.

For example, a Budget Center analysis of Census Bureau data shows that a family of four earning up to $166,800 annually in Madera County or up to $375,800 annually in Santa Clara County could each qualify for assistance. However, the final dollar amounts would be set by CalHFA if Prop. 37 is approved by voters.

How Is Prop. 37 Different from California’s Existing Downpayment Assistance Programs?

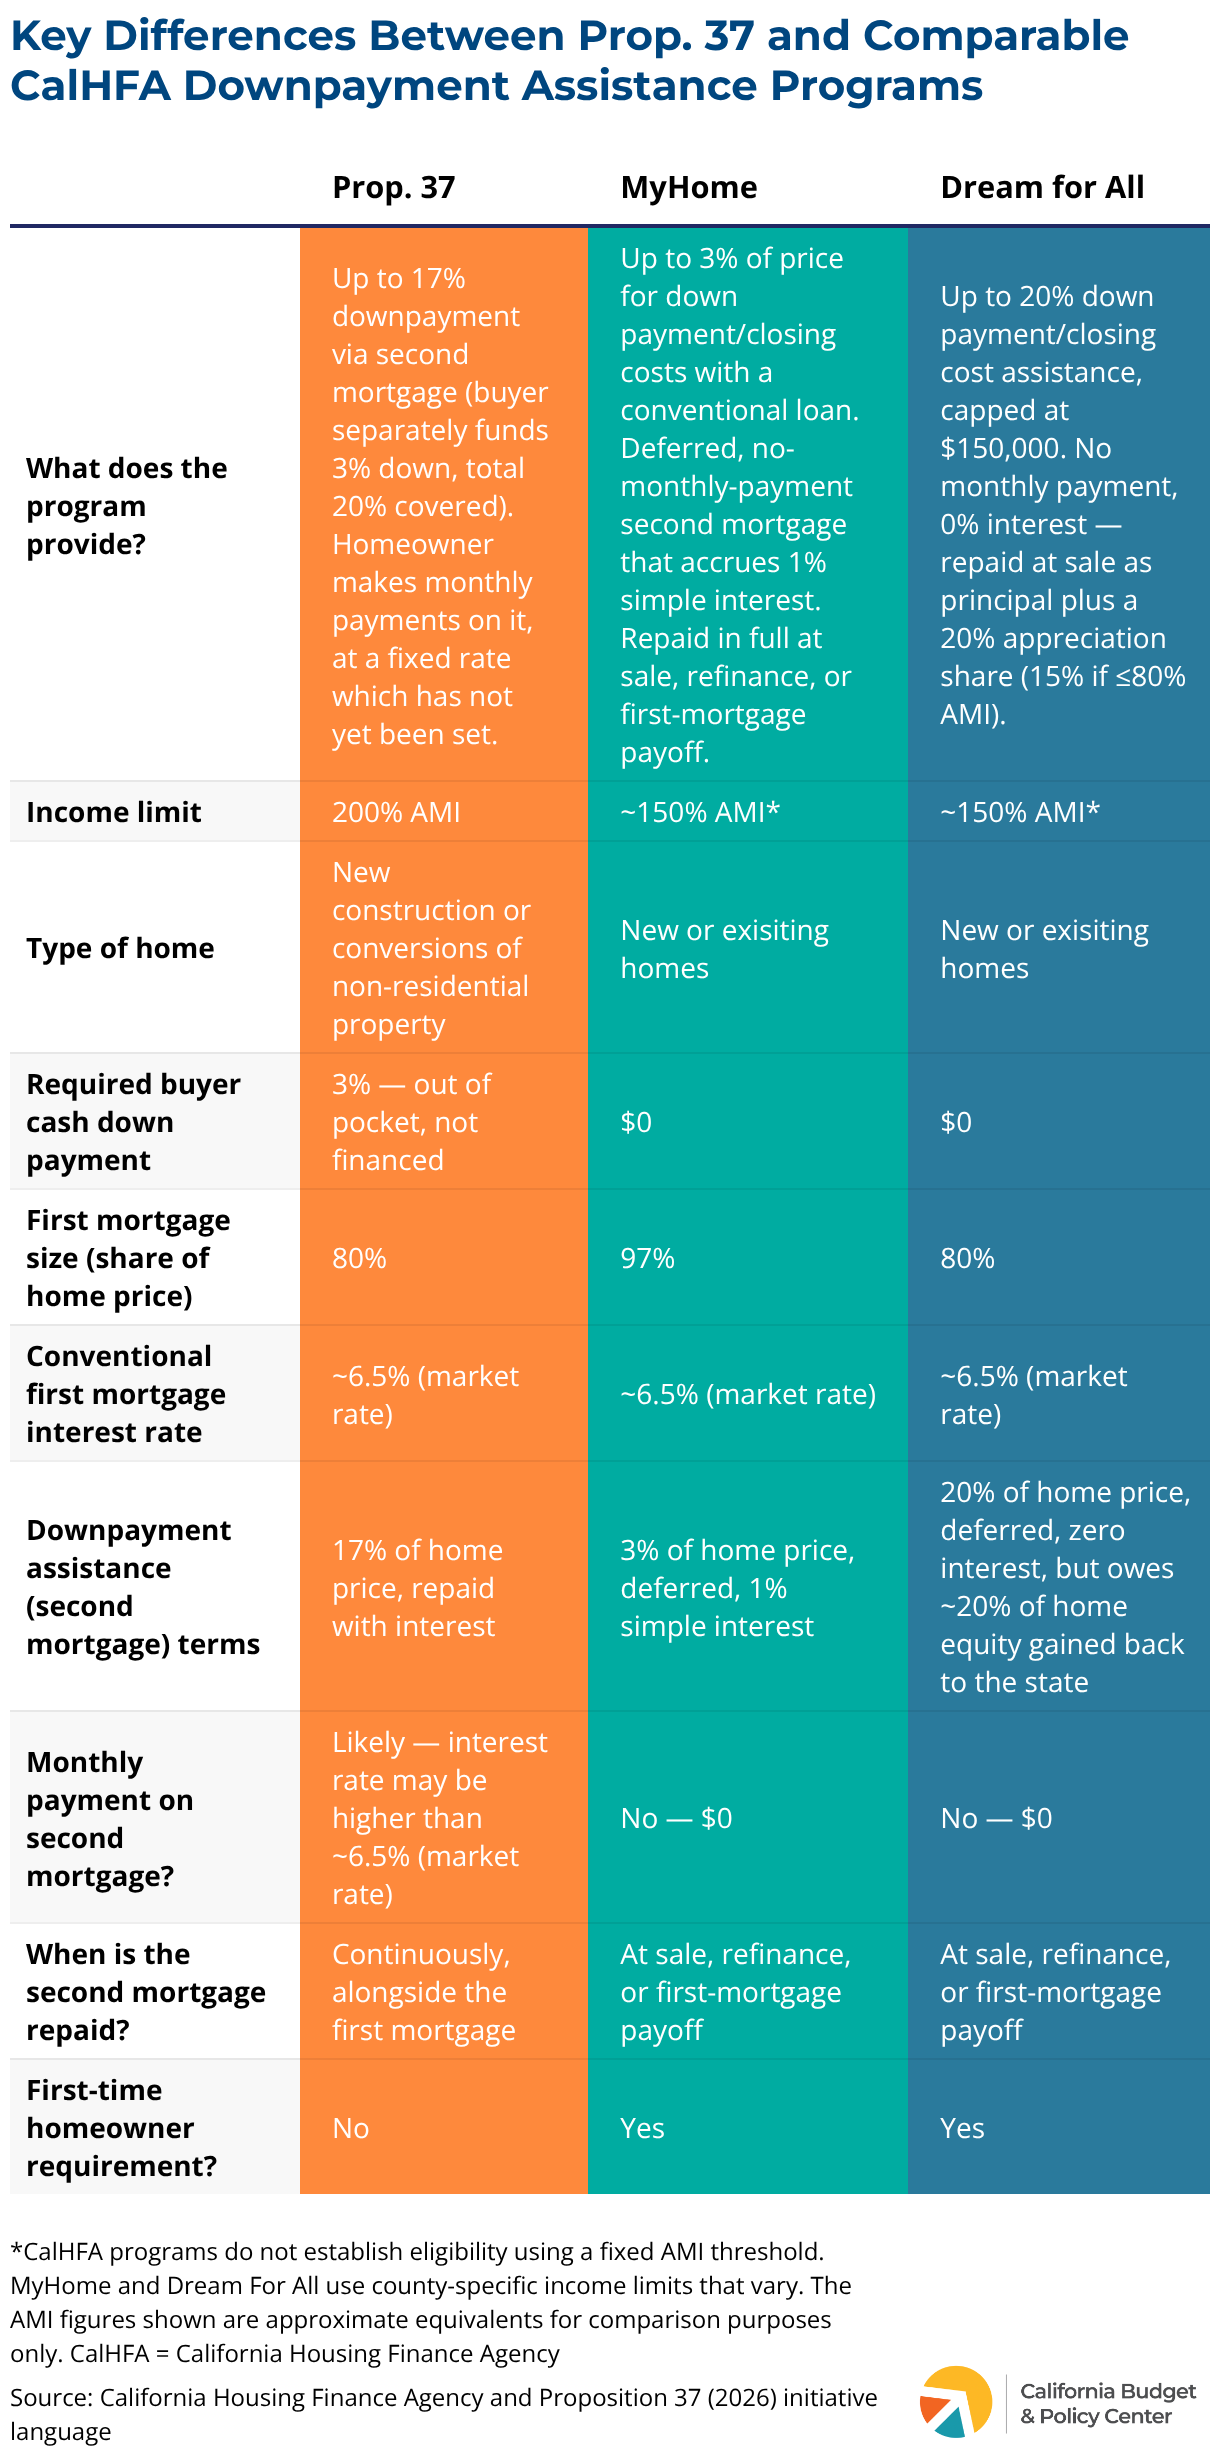
California operates several statewide homeownership programs through CalHFA, but Prop. 37 would take a different approach that could hit family budgets harder, as participants are likely to pay back the downpayment assistance monthly as a fixed-rate second mortgage.

For example, CalHFA’s MyHome Assistance Program and the Dream for All Shared Appreciation Loan program both provide downpayment assistance through deferred “silent second” loans (also known as silent second mortgages). MyHome charges 1% simple interest on the assistance; Dream for All accrues no interest, but requires a 15% or 20% share of the home’s appreciation to go to the state. Under both programs, nothing is due on these silent second mortgages until the homeowner sells, refinances, or pays off the first mortgage. This ensures that the downpayment assistance doesn’t compete with the first mortgage, groceries, utility bills, or other basic needs in a family’s monthly budget.

Prop. 37’s approach is likely to require monthly payments. This is because CalHFA would issue up to $25 billion in revenue bonds, and by law those bonds must be repaid from the proceeds of the program itself — meaning the principal and interest of the second mortgages CalHFA issues. The second mortgages would need to generate steady, ongoing revenue to pay the debt from the revenue bonds. Language in the measure also states “a borrower may request a temporary hardship deferral of monthly interest payments on its middle-class homeownership loan,” further alluding to its intended structure.

A voter casts a ballot at a polling place during an election, with voting booths and other voters visible in the background.

Curious About Other Ballot Propositions?

Browse our collection of resources covering California’s statewide ballot measures to help you understand what’s at stake for California this November.

Under Prop. 37, the second mortgage payment could also likely carry higher interest rates above conventional first mortgage rates. Although the measure states the intent to provide below-market downpayment assistance financing, it doesn’t guarantee it. The interest rate on the second mortgages would ultimately depend on the terms under which the bonds are issued and market conditions at the time of implementation, which are largely outside CalHFA’s control.

Revenue bonds that finance second mortgages are inherently riskier for investors because if a homeowner defaults, the first mortgage gets repaid before the second, leaving the bond investors more exposed to loss. Investors may therefore require a higher return to compensate for that additional risk, which could increase the interest rate on the second mortgage. This means Prop. 37’s second mortgage rate could land above the roughly 6.5% conventional first-mortgage rates buyers already face today. CalHFA wouldn’t set the actual rate or terms on the second mortgage until implementation, so the interest rate cannot be known before voters decide on Prop. 37.

Ultimately, while Prop. 37 could help get homebuyers to a 20% downpayment to avoid private mortgage insurance, the monthly repayment costs for the second mortgage could erode much of the benefit the downpayment assistance was meant to provide.

Would Prop. 37 Reach “Middle-Class” Californians Facing the Greatest Barriers to Homeownership?

Prop. 37 would make a broad range of households eligible for downpayment assistance, but income eligibility alone does not determine who can realistically purchase a home. Racial and ethnic disparities in income, wealth, credit access, and housing affordability mean that not all eligible families across California may be positioned to benefit from the program as proposed.

Prop. 37 would require the buyer to put down at least 3% of the purchase price, which would still be unattainable for many Californians. For example:

  • A house that costs $500,000 would require a 3% down payment of $15,000.
  • A house that costs $700,000 would require a 3% down payment of $21,000.

These upfront costs could be out of reach for many families, with the result that Prop. 37’s assistance could largely benefit families with incomes toward the higher end of the eligibility range. According to the Public Policy Institute of California, the median amount in Californians’ checking and savings accounts was just over $18,000 in 2025 dollars. This means that a 3% down payment could still almost or entirely clear out most or all of what an average family has in checkings and savings.

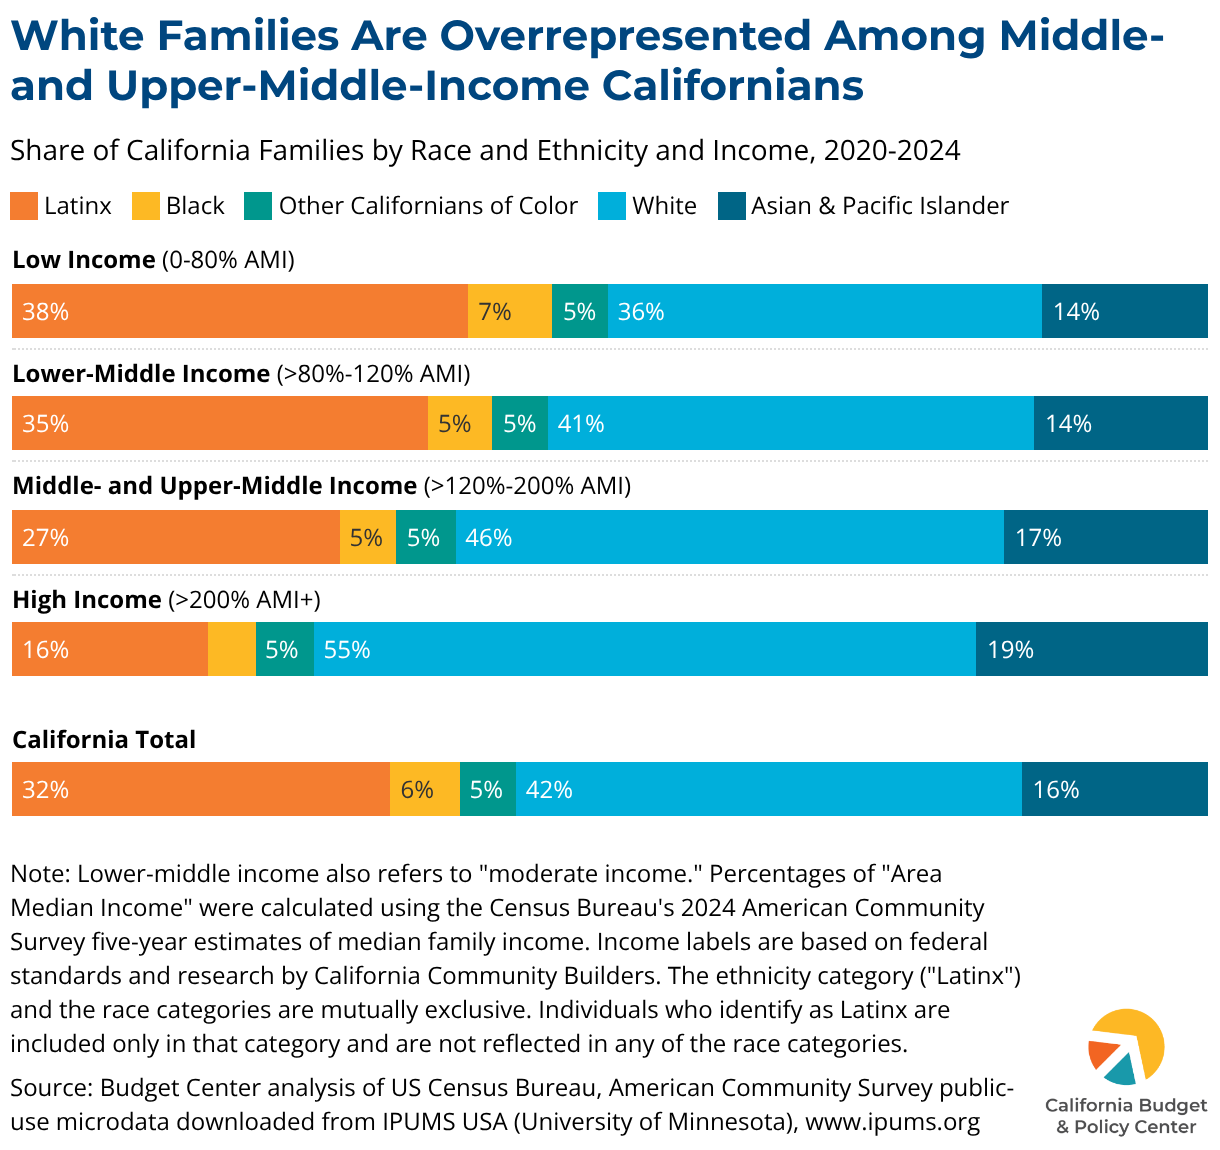
Prop. 37 could also reinforce economic, racial, and ethnic inequities in homeownership. The measure is intended to help “middle class” Californians, roughly defined as those with incomes between 80% to 200% AMI. White families are overrepresented among middle- and upper-middle-income Californians (46%), compared to their share of all California families (42%).

In contrast, Black and Latinx families are underrepresented in this “middle class” income range. This means that white families could disproportionately benefit from this program —  even though white households already make up the largest share of homeowners in the state, while Black and Latinx renter households face disproportionately high housing costs.

Prop. 37 does not require applicants to be first-time or first-generation home buyers, further exacerbating equity concerns. Black and brown communities have been historically excluded from building wealth and accumulating assets, making the barrier to entering the housing market even more pronounced. Families of color face occupational segregation that pushes them into lower-paying jobs. They are also less likely to inherit generational wealth, and are more likely to be renters. These factors make it substantially more difficult to save for a down payment, even at similar income levels. Additionally, data limitations often mask significant disparities in homeownership access across racial and ethnic groups, especially among Asian American, Native Hawaiian, and Pacific Islander Californians.

Could Prop. 37 Encourage Sprawl and Harm the Environment?

By restricting downpayment assistance to newly built homes or newly created housing units converted from nonresidential buildings, Prop. 37 could push more “middle-class” housing onto land that’s not well suited for housing. Much of the land in California best suited for housing has already been developed, leaving remaining areas that are often far from job centers, prone to wildfire,environmentally sensitive, or important for agriculture.

While existing state down payment assistance programs are not immune to these concerns because they can also be used to purchase new homes, Prop. 37 goes further by limiting assistance exclusively to newly constructed homes. As a result, Prop. 37 could further direct “middle-class” housing demand toward suburban and exurban areas. This is a critical deviation from infill development — building on denser, already developed land — which has been the focus of state affordable housing and environmental efforts.

This pattern of building housing on the periphery of cities is known as urban sprawl and carries various environmental and equity considerations. Development in more suburban and inland areas can push Californians further from job centers, increasing their commute times and making it difficult to travel without a car. It may also encourage development in areas on the outskirts of cities that may cause new homes to infringe upon natural habitats and important agricultural lands, especially in areas like the Central Valley. Sprawl can also lead to divestment from urban areas, which are often composed of communities of color, and concentrate investment in higher-income, suburban neighborhoods, further exacerbating racial and income inequality across the state.

What Other Homeownership Costs Could Come with Prop. 37’s New-Construction Requirement?

Prop. 37’s new construction requirement could steer homebuyers toward housing with higher out-of-pocket costs on top of their monthly mortgage payments. Unlike existing state down payment assistance programs, which can be used to purchase both new and existing homes, Prop. 37 would limit assistance to newly constructed homes. New construction homes are more likely to come with homeowners association (HOA) dues, Mello-Roos assessments, and home insurance challenges.

HOA fees are far more common in new homes as nearly 70% of newly built homes listed for sale nationally in 2024 were subject to HOA dues, compared with about 38% of existing homes. In California, more than a third of residents live in an HOA — including about 65% of all California homeowners. The average monthly fee is $280, and fees can rise up to 20% annually without a homeowner vote under current state law.

New construction in undeveloped areas of California also often comes with Mello-Roos special tax assessments, which fund infrastructure like roads, schools, and utilities in newly developed areas and are layered on top of regular property taxes — typically adding another monthly fee to new-build homes for years.

California’s home insurance market also compounds the problem. Some state insurers have stopped providing coverage in many of the wildfire-prone areas where new homes are being built which has statewide ramifications. California’s state-run insurer of last resort, known as the FAIR Plan, is likely to be overburdened to the extent that more insurers drop coverage across the state.

While home insurance challenges are not unique to Prop. 37, they remain acute in the wildland-urban interface — where almost 45% of the houses built in California have been located over the last 30 years. Though these areas tend to have less expensive real estate, they are also particularly susceptible to wildfires. That exposure could mean higher premiums, more difficulty securing a loan, or dependence on the FAIR Plan, driving additional costs on top of the repayments of Prop. 37.

Altogether, these compounding factors could undercut the affordability gains the measure is purported to provide for Californians. As a result, the benefits of Prop. 37 may skew toward eligible families with greater financial resources who were already better positioned to cover the costs of homeownership.

Who Supports and Opposes Prop. 37?

There have been some official supporters of the initiative, but no official opponents as of mid-summer 2026. Former California Senate Majority Leader and Assembly Speaker Robert Hertzberg is the primary sponsor and a supporter of this proposition. Hertzberg has stated the main goal of the measure is to allow working families and their children to build wealth and remain in California.

Various carpentry-focused unions and realty organizations — like the California Association of Realtors and the Northern California Carpenters Regional Council — have also expressed support for the measure. Gubernatorial candidate Xavier Becerra has also expressed support for this measure.

Stay in the know.

Join our email list!

key takeaway

Proposition 1, appearing on the November 2026 ballot, would provide funding for affordable housing and accessible homeownership. Prop. 1 asks voters to authorize a $11.25 billion general obligation bond to fund programs that support the creation and preservation of affordable housing, expand homebuying opportunities for low- and moderate-income Californians and veterans, and invest in permanent solutions to solve homelessness. If Prop. 1 is approved, it would replenish funding for several successful state programs that have exhausted their resources. Prop. 1 was placed on the ballot by the Legislature through passage of Senate Bill 417 (2026).

How Has California Expanded Affordable Housing & What Gaps Remain?

Over the past six years, California has nearly tripled the number of new affordable homes it funds. Yet the state continues to face a severe shortage of affordable housing, particularly for Californians with the lowest incomes. California needs more than 2.5 million new homes, including at least 1 million homes that are affordable to lower-income households. Housing cost pressures fall hardest on California renters as nearly half pay unaffordable rents — a hardship that disproportionately impacts Black and Latinx renters with low incomes, older adults, mixed-status families, and people with disabilities.

Unlike market-rate or luxury housing, affordable housing projects typically cannot be built without subsidies because affordable rents do not generate enough revenue to cover development or operating costs. As a result, affordable housing projects rely on multiple funding streams to close financing gaps. Currently, more than 46,000 affordable homes across California (491 developments) are waiting for the last bit of state funding needed to break ground. Prop. 1 would provide funding for various programs that help bridge the financial gap to keep affordable housing construction moving.

Why Is Affordable Housing Funding Running Out & How Would Prop. 1 Help?

Despite the ongoing housing affordability challenges Californians are facing, state funding for affordable housing has largely disappeared. Over the past several years, affordable housing programs have relied on one-time General Fund investments to supplement voter-approved housing bonds, but those investments have drastically declined. The 2026 Budget Act only includes one-time investments in two significant affordable housing programs: $500 million for state Low Income Housing Tax Credits and $200 million for the Multifamily Housing Program, effectively leaving multiple programs without additional funds. Beyond these investments, there is no meaningful ongoing or one-time investment from the state General Fund for affordable housing development.

The state’s remaining modest affordable housing funding sources, including the Affordable Housing and Sustainable Communities Program (AHSC), funded through Cap-and-Invest; state and federal Low-Income Housing Tax Credits; and SB 2 planning funds are insufficient to meet the demand and often require additional funding to be fully leveraged. The AHSC program was expected to receive nearly $800 million per year for affordable housing, but recent changes by the California Air Resources Board put that funding  at risk.

A voter casts a ballot at a polling place during an election, with voting booths and other voters visible in the background.

Browse our collection of resources covering California’s statewide ballot measures to help you understand what’s at stake for California this November.

The funding approved by voters through the 2018 Veterans and Affordable Housing Bond Act has been fully committed — exhausted within five years, by the end of 2023, due to overwhelming demand. The state’s flagship Multifamily Housing Program, which relied on funding from the bond and one-time General Fund investments, is routinely oversubscribed by roughly 9 to 1. Together these signal that the barrier to building more affordable housing in California isn’t a lack of will or projects — it’s a lack of sustainable funding.

Without new state investments, affordable housing production will stall just as California is making meaningful progress and as federal cuts threaten to make it even more difficult for Californians to make ends meet, which is why state lawmakers placed Prop. 1 on the ballot.

What Affordable Housing and Homeownership Programs Would Prop. 1 Fund?

Prop. 1 asks voters to authorize $11.25 billion in general obligation (GO) bonds that would support the construction and preservation of affordable rental homes, expand homeownership assistance for low- and moderate-income homebuyers, including veterans, and provide permanent housing for people at risk of or experiencing homelessness. Within these categories, it would provide some funding for programs that serve distinct populations, such as California tribes, farmworkers, unhoused youth, and college students. The bond funds would be allocated as follows:

Affordable Housing Development and Preservation

  • $5.1 billion for the Multifamily Housing Program (MHP), which supports the construction, rehabilitation, or preservation of affordable rental housing. At least 10% of units in a MHP development must be available for extremely low-income households who are at the highest risk of facing homelessness. This is one of California’s model affordable housing development programs.
  • $1.15 billion for supportive housing through the MHP program. Supportive housing provides stable homes with wrap-around services for people who were chronically homeless or at risk of becoming so. These funds can be used for operating subsidy reserves, which are critical to the longevity and sustainability of permanent supportive housing.
    • Up to 15% — $150 million — would be allocated as grants to acquire or build permanent supportive housing among other specified uses.
    • Another $150 million is carved out for the capital development or acquisition of youth housing through MHP. This would serve current or former foster youth, homeless minors or youth, or youth at risk of homelessness.
  • $750 million for the Portfolio Reinvestment Program, which provides funding to rehabilitate and extend the long-term affordability of state-funded rental multifamily housing projects that are at risk of conversion to market-rate housing.
  • $500 million for the Infill Infrastructure Grant Program. This would provide incentive grants to assist with new construction and rehabilitation of infrastructure that supports high-density affordable and mixed-income housing in locations designated as infill. 
  • $450 million for the Joe Serna, Jr. Farmworker Housing Program to fund grants or loans for the construction or rehabilitation of housing for agricultural employees and their families.
  • $350 million for affordable student housing projects to be split evenly between the University of California and the California State University. 
  • $200 million for a new Community Anti-Displacement and Preservation Program, which helps protect unsubsidized housing that may naturally be affordable and requires long-term affordability regulations.
  • $200 million for the Tribal Housing Grant Program which finances housing and housing-related activities to enable tribes to rebuild and reconstitute their communities. 
  • $200 million to the Affordable Housing Innovation Fund for the Local Housing Trust Fund Matching Grant Program. This would fund competitive grants or loans to local housing trust funds that develop, own, lend, or invest in affordable housing and would be used to create pilot programs to demonstrate innovative approaches to creating or preserving affordable housing.

Homeownership

  • $1.25 billion for the CalVet Home Loan Program to help veterans and their families purchase homes. This portion of the bond would be repaid through  mortgage (principal and interest) payments. 
  • $600 million for the CalHome program. CalHome provides forgivable loans for lower-income households in self-help homeownership projects, including subdivisions and manufactured homes. 
  • $500 million for the My Home downpayment assistance program to fund low-to-moderate income home purchase assistance programs.

What Benefits Would Prop. 1 Create for California’s Economy & Communities?

Prop. 1 would help expand and preserve California’s affordable housing supply while generating economic benefits and advancing the state’s housing goals. The bond would help close the financing gap for affordable rental homes, which serve lower-income California families and include seniors, people with disabilities, farmworkers, college students, and unhoused youth. According to legislative analyses, the bond is expected to:

  • Produce more than 40,000 new affordable homes for lower-income families and individuals.
  • Preserve more than 5,500 existing affordable homes, ensuring they remain affordable for future generations. 
  • Create more than 53,000 construction jobs through building new housing across the state.
  • Generate $1.3 billion in state and local tax revenue that supports local communities and public services.

Every $1 invested in state affordable housing leverages roughly $4 in federal, local, and private investment, maximizing the impact of public dollars. Affordable housing also delivers economic, health, and environmental benefits. For example:

Together, these investments would expand housing opportunities, reduce housing instability, strengthen local economies, and help California meet its long-term housing needs.

How Would Prop. 1 Be Repaid?

Prop. 1 asks voters to authorize a total of $11.25 billion in GO bonds, divided as follows:

  • A $10 billion GO bond for affordable housing and homeownership programs that would be repaid from the state’s General Fund, and
  • A $1.25 billion veterans’ bond, a type of tax-exempt GO bond, for the CalVet Home Loan program that would be repaid through mortgage payments, with the General Fund as a backstop.

California voters often pass GO bonds to fund infrastructure projects that are designed to serve the public over many generations, as has been the case with affordable housing. Voters have also historically passed veterans’ bonds for CalVet to support homeownership opportunities for veterans.

GO bonds are repaid from the state’s General Fund. Repaying the $10 billion bond would cost $580 million per year for the next 30 years, for a total estimated cost of $17.4 billion ($10 billion in principal and $7.39 billion in interest). As of the governor’s proposed 2026-27 budget, California had $6.3 billion in General Fund debt service for GO bonds, or roughly 2.6% of General Fund expenditures.

In contrast, veterans bonds are generally self-supporting because they are repaid through principal and interest payments made by CalVet Home Loan Program borrowers. However, they are still GO bonds and are ultimately backed by the state’s General Fund. If program revenues were insufficient to cover the debt service, the General Fund would be responsible for the difference. It is unclear how often, if ever, the General Fund has had to backfill debt payments for previous veterans bonds.

Prop. 1 bond dollars would replenish depleted affordable housing programs. But bond dollars alone will not solve the housing shortage, nor would they replace the need for ongoing investments to meet the state’s substantial housing needs.

Prop. 1 and Prop. 38 Draw From Same Bonding Capacity, Face Important Trade Offs

Voters face two GO bond measures on the November 2026 ballot: Prop. 1 and Proposition 38. Prop. 38 would authorize $8.4 billion in GO bonds to support research and development in immunology and immunotherapy. Voters should weigh how each proposal addresses the state’s most pressing needs, fits within California’s limited borrowing capacity, and affects the state’s ability to invest in services that help families today and in the future.

Like all GO bonds, Prop. 38 would require long-term General Fund debt-service payments — estimated at $500 million annually for 25 years — reducing budget and bonding capacity for other state priorities. If both Prop. 1 and Prop. 38 are approved, it would reduce General Fund dollars by roughly $1.1 billion annually.

Public sector investment in scientific research is needed, particularly given federal cuts, but Prop. 38 raises important fiscal and policy considerations. GO bonds are conventionally used to finance infrastructure projects — like roads, bridges, or housing — that can be used over decades, roughly matching the time it takes to repay the bond itself.

Funding research through GO bonds does not work the same way. Bond-funded research gets most of the dollars upfront for grants, salaries, and operating costs, but are not guaranteed to be built into a lasting asset. Research findings do compound overtime, but the bond dollars themselves are depleted after a few years. The state then spends years or decades paying interest on bonds that stopped directly funding work long ago. So while scientific research needs funding, a GO bond is not the appropriate funding mechanism. Plus, half of Prop. 38’s funding would be concentrated on a limited set of health conditions, even though California already has multiple public and private research institutions conducting work in these areas.

Prop. 1 doesn’t confront these same challenges. While previous affordable housing bond dollars were also used up quickly, they left behind affordable homes that will continue to serve numerous families for decades. Affordable housing developments that use state dollars must have affordability requirements for at least 55 years — way beyond the repayment of the bonds with which they’re financed. The community benefits and capital assets outlast the debt, which is the intended purpose of GO bonds.

Prop. 1 Supporters and Opponents

Prop. 1 is supported by a broad coalition of organizations representing housing, business, labor, local government, older adults, tenants, homelessness, urban planning, construction, environmental, and civil rights interests, among others.

Official opposition has been limited. The primary opponents on record include a few Republican state legislators who voted against placing the measure on the ballot.

Stay in the know.

Join our email list!

key takeaway

Proposition 3 will appear on the November 2026 statewide ballot, asking California voters whether to make permanent the higher-income tax rates on the state’s highest earners. These top tax rates were first enacted by voters in 2012 and renewed in 2016 to help fund schools, health care, and other supports for working families. Without action, the current rates are set to expire after 2030, reducing state revenues by billions of dollars annually and threatening funding for schools and state programs and services that support Californians every day.

What Would Prop. 3 Do?

Prop. 3  would make permanent the rates put in place since 2012, preserving a key element of progressivity (requiring households with higher incomes to pay higher tax rates) in the state’s revenue structure that funds critical investments that improve the quality of life for all Californians. The measure would not raise taxes or change existing income tax rates; it simply removes the expiration date on current tax rates for the state’s highest earners. Revenues would continue to support the entire state General Fund budget by helping meet the TK-14 constitutional funding guarantee and freeing up revenue for other programs and services, just as they have since 2012.

Background on Prop. 30 and Prop. 55

In 2012, after the state faced significant revenue losses as a result of the Great Recession, California voters approved Proposition 30, which added new income tax brackets for the state’s highest earners (10.3%, 11.3%, and 12.3%, depending on household income) and included a temporary sales tax increase. Both the income tax rates and the sales tax increase were temporary, with the sales tax set to expire in 2016 and the income tax rates in 2018. Proposition 30 also created the Education Protection Account, a state account in the General Fund that receives and disburses revenues from the top income tax rates.

what is the education protection account (epa)?

Proposition 30 (2012) established the Education Protection Account, a state account where revenues from the top income tax rates are deposited. Of the funds in the account, 89% are distributed to schools and 11% to community colleges. This revenue is treated as General Fund revenue, subject to constitutional requirements including Prop. 98 (1988), the state’s minimum funding guarantee for TK-14 education, and Prop. 2 (2014), which established rules for building state budget reserves and paying down state debts. The revenue deposited into the EPA increases the Prop. 98 guarantee and is used to help meet the guarantee, freeing up General Fund revenue for other state budget priorities.

In 2016, voters approved Proposition 55, which extended the income tax rates for another 12 years (to 2030), while allowing the sales tax to expire as scheduled. Prop. 55 also added a constitutional formula intended to increase funding for the Medi-Cal program when revenues exceed a certain threshold. This specific formula has never directed funds to Medi-Cal, and the current measure would allow it to expire. However, top tax rate revenues do support the Medi-Cal budget indirectly through the General Fund capacity generated by Prop. 55.

Since their initial enactment in 2012, these higher tax rates have generated around $120 billion for schools and other essential services. In recent years, the higher rates have generated around $10 billion annually. These revenues now form a core component of the state budget, supporting the TK-14 education budget, strengthening General Fund capacity to support other vital programs and services, and building reserves.

Who Pays the Voter-Approved Top Tax Rates?

The voter-approved top tax rates only impact the highest-income Californians.

These rates only apply to the top 2% of California tax filers. In tax year 2025, these top rates only applied to people with incomes above around $371,000 for single tax filers and about $743,000 for married couples filing jointly. These thresholds increase annually with inflation.

Without Voter-Approved Tax Rates, the Top 1% Would Receive Another Tax Cut

The top-earning 1% of Californians would receive a major tax cut if Prop. 55 rates are not extended. If the voter-approved top tax rates are allowed to expire, the vast majority of tax filers in the top 1% by income would receive an average annual tax cut of nearly $59,000, according to estimates from the Institute on Taxation and Economic Policy. This top 1% group would get about 98% of the total tax cuts. The remaining tax cuts would go to some households in the next 4% of highest-income filers.1Not all households in the top 5% or top 1% would receive tax cuts from the expiration of the top tax rates for several reasons. First, filers are subject to the top tax rates if their taxable income — that is, income after accounting for allowed exemptions and deductions — exceeds the thresholds established by Prop. 30 and Prop. 50. In contrast, the thresholds for the top 5% and top 1% used by the Institute on Taxation and Economic Policy for this analysis are based on total income before exemptions and deductions. So tax filers in the top 1% by total income may have taxable incomes under the threshold for the top rates. Second, some high-income filers that use specific tax preferences may be subject to an “alternative minimum tax,” which could be triggered if their regular tax bill were reduced. And finally, because thresholds for these rates vary by household type, a married couple filing a joint tax return with a total income of $500,000 falls into the top 5% of all tax filers, but their total income — even before accounting for exemptions and deductions — is below the threshold for the Prop. 55 taxes of around $743,000, for example. Around 15% of this group would receive a tax cut, averaging more than $2,000 annually. Californians in all other income groups would see no change to their taxes.

California’s tax system would be more regressive if the Prop. 55 tax rates expire. A regressive tax system is one in which lower-income households pay larger shares of their income in taxes than higher-income households. In contrast, in a progressive tax system, higher-income people pay higher shares of their income in taxes. California’s tax system is more progressive than many other state tax systems, in large part due to these voter-approved top tax rates that are up for renewal under Prop. 3.

When you add up the various state and local taxes that Californians pay — including the sales tax, property tax, and other types of taxes — the highest-income 1% currently pay about 12% of their income in taxes on average. That’s barely more than the 11.7% paid by Californians in the lowest 20% by income. If the top rates were not in effect, the top 1% would pay only about 10.7% of their income in state and local taxes — lower than what the bottom fifth of Californians pay.

Top Earners’ Incomes Have Soared

The number of Californians with incomes high enough to be subject to the voter-approved top tax rates has more than doubled, reflecting soaring incomes among top earners. Around 185,000 tax filers, including more than 175,000 California resident filers, had incomes above the thresholds for Prop. 30’s top tax rates in 2013, the first year the rates were in effect. By 2024 (the latest available data), the number had reached nearly 376,000, including around 355,000 California residents.2“Tax filer” represents a tax filing unit — the primary filer as well as any spouses and dependents included on the tax return. A tax filing unit can be an individual, a couple, or a family, and in some cases can include unrelated dependents. This increase is due to the incomes of these high-income households growing much faster than inflation over this period.

Californians subject to the top tax rates have seen their incomes grow dramatically over the past several decades, while most Californians have lost ground or experienced income declines after adjusting for inflation. The top 1% of Californians saw their inflation-adjusted incomes increase more than 2.5 times (157%) between 1987 and 2024, while those in the bottom 80% saw decreases in real income over that time.

To be in the top 1%, a tax filer had an income of at least $973,097 in 2024. On average, this group reported more than $3 million per tax return in 2024 — about 54 times the income of the middle fifth of Californians, who earned around $56,000 on average. In even starker contrast, the top 0.1% had an average income of over $15 million — 268 times that of the middle fifth of Californians. In other words, someone in the top 1% can earn in just under one week what the average middle-income Californian earns in an entire year, and someone in the top 0.1% can earn that amount in just over a day.

What Have the Top Income Tax Rates Accomplished?

Since the passage of Prop. 30 in 2012, the top tax rates have generated about $120 billion in state revenue.3This figure reflects revenues from the top tax rates allocated to TK-14 education from the Education Protection Account (EPA) through the 2024-25 fiscal year. On average, this revenue has represented about 5.5% of total General Fund revenues. The funds raised by the top tax rates approved by voters through Prop. 30 and Prop. 55 have been a major revenue source for the state, supporting critical services including education, health care, and economic security programs. This revenue has also helped the state to build up budget reserves to be better prepared for downturns when revenues decline or come in lower than expected.

The annual revenue raised by the top tax rates has increased in line with overall state revenues. These revenues are sensitive to stock market fluctuations, as a large share of the income of high-income households comes from earnings on investments such as dividends and capital gains. For example, Prop. 55 revenues peaked at more than $16 billion when the stock market surged in 2021 and then subsequently fell in line with the stock market decline in the following years, before growing to nearly $12 billion in 2024. The sensitivity of these revenues to economic conditions makes it all the more important that state leaders have the capacity to save revenues during high-revenue years in the state’s budget reserves for future downturns, as required under Prop. 2 of 2014 — which may be modified to require additional savings in some strong-revenue years if voters approve changes to the existing measure with Prop. 2 on the November 2026 ballot.

Top tax rate revenues provide critical support for schools and community colleges. Top tax rate revenues serve two purposes for the TK-14 education budget: 1) increase the Prop. 98 minimum guarantee’s annual calculation and 2) provide the revenues needed to meet the guarantee. Because top tax rate revenues count as General Fund revenues, they directly affect how the annual Prop. 98 level is calculated. In years when the General Fund experiences strong growth, the guarantee is set as a share (about 40%) of General Fund revenues, establishing a higher floor.4The minimum guarantee is determined using one of three formulas: 1) approximately 40% of General Fund revenue, 2) the prior year level adjusted for K-12 attendance growth and growth in per capita personal income, or 3) the prior year level adjusted for K-12 attendance growth and per capita General Fund revenue growth. In other years, the guarantee builds on the prior year’s level, carrying forward the growth built when revenues were strong. Regardless of how the guarantee is calculated, the effect of the top tax rate revenue is cumulative. As shown in the chart below, the guarantee has grown on an ongoing basis since 2012-13, with part of this growth attributable to the top tax rates.

what is proposition 98?

Prop. 98 is a constitutional amendment adopted by California voters in 1988 that establishes an annual minimum funding level for TK-14 education each fiscal year, commonly referred to as the minimum guarantee. Prop. 98 funding comes from a combination of state General Fund revenue and local property taxes. Prop. 98 spending supports TK-12 schools, community colleges, county offices of education, the state preschool program, and state agencies that provide direct TK-14 instructional programs. While Prop. 98 establishes a required minimum funding level for programs falling under the guarantee as a whole, it does not protect individual programs from reduction or elimination.

In addition to raising the guarantee’s calculation, Prop. 55 revenues directly help meet the guarantee. Revenues from the top tax rates are used to meet the Prop. 98 obligation, which frees up General Fund dollars that would otherwise be needed to meet the guarantee. These freed-up dollars are used to support non-TK-14 programs, build state reserves, and pay down debts. Since 2012-13, when these revenues began to flow to schools and community colleges, Prop. 55 revenues have provided about $120 billion to help meet the TK-14 budget.5While the top tax rate revenues have provided approximately $120 billion to the TK-14 budget through the EPA, because these revenues also reduce the General Fund dollars to meet the guarantee, the overall education funding impact is approximately 40% of total revenues.

The chart below shows the growth in the minimum guarantee, and the share provided by the top tax rate revenues, adjusted to 2024 dollars. Throughout this period, top tax rate revenues have enabled the state to implement key educational programs. For example, in the 2013-14 school year, policymakers began implementing a major school finance reform to more equitably allocate dollars to school districts based on student need.

Why Renewing the Top Tax Rates Matters for California

As the revenues from the current top tax rates have become a critical source of funding for education, health care, and other state services, their expiration after 2030 would likely lead to significant budget shortfalls. If Prop. 3 does not pass — and state leaders or voters do not approve alternative revenues — funding for essential state services would be put in jeopardy. This is especially concerning given that state officials already project ongoing budget deficits in upcoming years, as the cost of existing state services is growing due to inflation and a changing population, and revenue growth is not keeping up. Those projected deficits, compounded by federal cuts resulting from H.R. 1, the 2025 federal budget reconciliation law known as the “One Big Beautiful Bill Act,” would put significant pressure on the state budget and the programs it supports.

In recent years, the top tax rates have contributed around $10 billion annually to the state budget, and the Legislative Analyst’s Office projects that making these rates permanent would bring in between $5 billion and $15 billion annually in the future — depending on the economy and stock market performance. The loss of $5 billion to $15 billion could mean:

  • Reduced General Fund resources to protect and strengthen services that keep Californians healthy, housed, and economically secure. In recent years, more than two-thirds of state spending growth from available revenues has gone simply to sustaining existing levels of services, including keeping pace with rising costs and growing caseloads in programs like Medi-Cal, In-Home Supportive Services, and child care. The loss of Prop. 55 revenues would worsen existing deficit projections, making it harder for the state to maintain even current levels of services, potentially leading to programmatic cuts to essential programs.
  • The loss of a key revenue stream and increased pressure to meet the Prop. 98 minimum guarantee. In the near term, without the revenues from the top tax rates, the state would need to replace billions in funding for TK-12 education from other General Fund sources to meet the guarantee, potentially resulting in cuts to other services like health care and child care.8As noted in a text box above (“What Is the Education Protection Account?”), the revenues from the top tax rates both 1) increase the Prop. 98 guarantee and 2) are used to help meet the guarantee, freeing up General Fund revenue for other state budget priorities. If the top tax rates are not extended, the revenues that they generate would be eliminated after the 2030 tax year. This would impact the level of the Prop. 98 guarantee while also creating a hole in the Prop. 98 budget that would have to be filled with other General Fund revenue. In the long run, the loss of this dedicated revenue stream would result in the Prop. 98 guarantee being lower than if the top tax rates were extended — by around 40% of the total revenue loss. In other words, TK-14 education would receive less funding over time than it would if voters extended the top rates.
  • A reduced capacity to save and prepare for economic downturns. Without the additional revenues from the current top tax rates, deposits into the state’s rainy day fund and debt repayments required by Prop. 2 would be lower. This would leave the state less resilient when the next recession arrives, making critical state services more vulnerable to cuts.
  • Diminished ability to respond to anticipated federal cuts. The 2025 budget reconciliation package, H.R.1, includes significant cuts to health care and food assistance. Cuts to health care could total tens of billions each year. On top of that, cuts to food assistance could cost the state more than $5 billion annually. Currently, the state budget does not have the General Fund capacity to fully address these cuts, and the loss of top tax rates would only increase the millions of Californians at risk of losing these critical services.
  • 1
    Not all households in the top 5% or top 1% would receive tax cuts from the expiration of the top tax rates for several reasons. First, filers are subject to the top tax rates if their taxable income — that is, income after accounting for allowed exemptions and deductions — exceeds the thresholds established by Prop. 30 and Prop. 50. In contrast, the thresholds for the top 5% and top 1% used by the Institute on Taxation and Economic Policy for this analysis are based on total income before exemptions and deductions. So tax filers in the top 1% by total income may have taxable incomes under the threshold for the top rates. Second, some high-income filers that use specific tax preferences may be subject to an “alternative minimum tax,” which could be triggered if their regular tax bill were reduced. And finally, because thresholds for these rates vary by household type, a married couple filing a joint tax return with a total income of $500,000 falls into the top 5% of all tax filers, but their total income — even before accounting for exemptions and deductions — is below the threshold for the Prop. 55 taxes of around $743,000, for example.
  • 2
    “Tax filer” represents a tax filing unit — the primary filer as well as any spouses and dependents included on the tax return. A tax filing unit can be an individual, a couple, or a family, and in some cases can include unrelated dependents.
  • 3
    This figure reflects revenues from the top tax rates allocated to TK-14 education from the Education Protection Account (EPA) through the 2024-25 fiscal year.
  • 4
    The minimum guarantee is determined using one of three formulas: 1) approximately 40% of General Fund revenue, 2) the prior year level adjusted for K-12 attendance growth and growth in per capita personal income, or 3) the prior year level adjusted for K-12 attendance growth and per capita General Fund revenue growth.
  • 5
    While the top tax rate revenues have provided approximately $120 billion to the TK-14 budget through the EPA, because these revenues also reduce the General Fund dollars to meet the guarantee, the overall education funding impact is approximately 40% of total revenues.
  • 6
    Prop. 2 (2026), if approved, would make additional changes to require state leaders to increase deposits into the rainy day fund in some high-revenue years.
  • 7
    Starting in 2030-31, the entire amount will be deposited into the rainy day fund, although  policymakers will retain the option to use up to one-half to pay down debts.
  • 8
    As noted in a text box above (“What Is the Education Protection Account?”), the revenues from the top tax rates both 1) increase the Prop. 98 guarantee and 2) are used to help meet the guarantee, freeing up General Fund revenue for other state budget priorities. If the top tax rates are not extended, the revenues that they generate would be eliminated after the 2030 tax year. This would impact the level of the Prop. 98 guarantee while also creating a hole in the Prop. 98 budget that would have to be filled with other General Fund revenue.

Stay in the know.

Join our email list!

key takeaway

Prop. 1, passed in March 2024, aims to strengthen California’s behavioral health system by funding mental health treatment, substance use disorder services, and supportive housing for veterans and individuals facing homelessness. Ensuring equitable access to these essential services is critical as the state works to address both housing insecurity and behavioral health needs across diverse populations.

Millions of Californians, including many facing housing insecurity, rely on county-provided services to address mental health conditions and substance use disorders. Strengthening the state’s behavioral health system is essential to guaranteeing that every Californian — regardless of race, age, gender identity, sexual orientation, or where they live — can access the care they need.

In March 2024, California voters narrowly passed Proposition 1 on the promise to improve the state’s behavioral health system and provide the housing support needed to successfully maintain mental health and substance use disorder services for all Californians.

Prop. 1 was a two-part measure that 1) amended California’s Mental Health Services Act and 2) created a $6.38 billion general obligation bond. The bond will fund behavioral health treatment and residential facilities, and supportive housing for veterans and individuals at risk of or experiencing homelessness with behavioral health challenges.

As the transformation of California’s county-based behavioral health system brings both benefits and potential challenges for Californians, this Q&A highlights key developments of Prop. 1 since its passage and addresses important questions and considerations that remain.

Key Acronyms

  • BHSA: Behavioral Health Services Act (formerly the Mental Health Services Act)
  • BHIBA: Behavioral Health Infrastructure Bond Act 
  • BHCIP: Behavioral Health Continuum Infrastructure Program
  • CalHHS: California Health and Human Services Agency
  • CalVet:  California Department of Veteran Affairs
  • DHCS: California Department of Health Care Services
  • HCD: California Department of Housing and Community Development

Key Terms

What does Prop. 1 do?

Prop. 1 significantly amended the Mental Health Services Act (MHSA), a law that California voters passed in 2004 that created a millionaire’s tax to provide increased funding for mental health services. Revenue from this tax is crucial to California’s behavioral health system as it accounts for nearly one-third of county behavioral health services funding. Prop. 1 renamed the law the Behavioral Health Services Act (BHSA) and made other changes, including:

  • Expanding its scope to encompass treatment for substance use disorders.
  • Modifying how revenue from the millionaire’s tax is allocated for behavioral health services.
  • Changing the requirements for counties’ three-year program and expenditure plan for behavioral health services and outcomes.
  • Revising accountability and transparency requirements for counties.

Prop. 1 additionally established a $6.38 billion behavioral health infrastructure bond. Roughly $4.4 billion is dedicated to the infrastructure development of treatment and residential care facilities. The remaining $2 billion is reserved for permanent supportive housing units specifically for veterans and other Californians with serious mental health conditions or substance use disorders. 

This initiative was designed to create targeted funding for mental health services and housing or treatment units for people with behavioral health conditions who are experiencing or at risk of homelessness. As such, these reforms will only serve a subset of Californians, as they do not cover everyone at risk of homelessness or all individuals with behavioral health conditions.

What do we know about the behavioral health infrastructure bond?

Major developments regarding Prop. 1 have primarily related to the Behavioral Health Infrastructure Bond Act (BHIBA). BHIBA created a $6.38 billion general obligation bond to fund the infrastructure development of treatment and residential sites as well as supportive housing. There are two programs funded by the bond which are overseen by different state departments:

HCD is aggregating two main funding sources for Homekey+ for a total of $2.25 billion for the upcoming November application cycle:

  • $1.98 billion from Prop. 1 bond funding, with $1.065 billion designated for veterans and $922 million for other people experiencing or at risk of homelessness. 
  • $323 million Homeless Housing, Assistance, and Prevention Program (HHAP) Homekey Supplemental funding appropriated in the 2023 and 2024 Budget Acts.

Homekey+ projects are required to demonstrate a funding match of at least 3 years for operating costs. For long-term sustainability, HCD is encouraging counties to pair the restructured BHSA housing intervention dollars and other funding sources for behavioral health treatment to provide long-term service and operating costs for Homekey+ projects. However, Homekey+ projects will be awarded before counties are required to have their new three-year BHSA expenditure plans approved, which may create budgeting challenges.

How are counties allocating Behavioral Health Services Act (BHSA) funds under Prop. 1?

Prop. 1 significantly reforms the allocation of MHSA (now BHSA) dollars to prioritize Californians who are most affected by severe behavioral health conditions (mental illness and substance use disorders) and homelessness.1SB 326 created the legislative language for the BHSA.

Under Prop. 1, counties continue to receive the bulk of BHSA funds (90%). However, the allocation across different spending categories would change. Counties would allocate their BHSA funds as follows:

Prop. 1 shifts a small percentage of dollars from counties to the state (from about 5% of total MHSA funding to about 10%). This would result in about $140 million annually redirected to the state budget. However, this amount could be higher or lower depending on the total amount of revenue collected from the tax.

Prop. 1 also revised the allocation of state-level funds:

  • At least 3% to the Department of Health Care Access and Information to implement a statewide behavioral health workforce initiative.
  • At least 4% to the California Department of Public Health for population-based mental health and substance use disorder prevention programs. A minimum of 51% of these funds must be used for programs serving Californians who are age 25 years or younger.

What are the new county reporting requirements under Prop. 1?

Prop. 1 changes the way counties plan and report behavioral health funding. 

Starting in 2025, counties will need to develop integrated county plans for the 2026-29 fiscal years. The steps for developing plans are similar to how counties developed plans under the MHSA — counties will still gather community input and receive approval from County Boards of Supervisors. However, a key change is that counties will now report on all behavioral health funding, not just BHSA dollars. This includes local, state, and federal funding sources such as opioid settlement funds, SAMHSA and PATH grants, realignment funding, and federal financial participation.

Counties will also be required to report on unspent funds, service utilization data, outcomes with a focus on health equity, workforce metrics, and other information. The Department of Health Care Services (DHCS) has the authority to impose corrective action plans on counties that fail to meet these requirements. Additionally, the State Auditor will release a report on the implementation of the BHSA by December 31, 2029, with follow-up reports every three years thereafter.

What do we know about implementation timelines?

Since the passage of Prop. 1 in March, various developments regarding both the behavioral health infrastructure bond and county guidance for BHSA reforms have surfaced.

Behavioral Health Infrastructure Bond

Treatment and Residential Sites — BHCIP

In July, the Department of Health Care Services (DHCS) released an expedited timeline to roll out $3.3 billion for the construction, renovation, or expansion of treatment and residential care facilities through the existing Behavioral Health Continuum Infrastructure Program (BHCIP). Round 1 applications for “launch ready” projects are currently being accepted through mid-December 2024. DHCS is prioritizing applicants working in regional models or collaborative partnerships focused on expanding residential treatment facilities. Awards for Round 1 are anticipated to be announced in May 2025 and Round 2 “unmet needs” project applications will be opened in the same timeframe for the remaining $1.1 billion bond funds.

Permanent Supportive Housing — Homekey+

The Department of Housing and Community Development (HCD), in conjunction with the Department of Veteran Affairs (CalVet), engaged with stakeholders on the roll out of the Homekey Plus (Homekey+) program. Homekey+ is expanding on the Homekey Program which funded the acquisition and conversion of property for permanent supportive housing during and after the COVID-19 pandemic. It is receiving roughly $2 billion in bond funds to develop supportive housing for people with behavioral health conditions, with $1.065 billion designated for veterans and $922 million for other people experiencing or at risk of homelessness. HCD was collecting stakeholder input through the end of September. Applications will open November 2024 with continuous award announcements beginning in May 2025.

Behavioral Health Services Act Reform

Since the passage of Prop. 1 in March 2024, the California Health and Human Services Agency (CalHHS) and the State Department of Health Care Services (DHCS) have held public listening sessions to share Prop. 1 implementation updates and collect feedback from counties and other interested groups.

DHCS, in coordination with other agencies and departments, is currently in the midst of stakeholder engagement to inform new county expenditure plans and reporting requirements under the BHSA.2Other departments and agencies include: CalHHS, the California Behavioral Health Planning Council, and the Behavioral Health Services Oversight and Accountability Commission. CalHHS plans to share full guidance to counties in early 2025.

In addition, Prop. 1 created a Behavioral Health Services Act Revenue and Stability Workgroup, which has held two meetings. This group is charged with developing and recommending solutions to reduce BHSA revenue volatility and to propose appropriate prudent reserve levels to support the sustainability of county programs and services.

To support Prop. 1 implementation, the Department of Health Care Access and Information (HCAI) is taking steps to improve the behavioral health workforce. HCAI recently presented its strategy on how to grow and diversify the behavioral health workforce to the California Health Workforce Education and Training Council, and will provide additional updates in November 2024. The behavioral health workforce shortage in California is a major obstacle to addressing the growing need for mental health and substance use disorder services.

What don’t we know about Prop. 1 implementation?

There are several critical questions and considerations surrounding the BHSA reforms and behavioral health bond funds that are yet to be addressed. As key Prop. 1 players continue to engage with stakeholders, roll out program details, and prepare to release additional county guidance in early 2025, the following fundamental questions are essential to understanding how these reforms will impact Californians and current behavioral health and housing systems. Key questions include:


  • 1
    SB 326 created the legislative language for the BHSA.
  • 2
    Other departments and agencies include: CalHHS, the California Behavioral Health Planning Council, and the Behavioral Health Services Oversight and Accountability Commission.

Stay in the know.

Join our email list!

key takeaway

California voters will decide on November 5th, 2024 whether to pass Proposition 35, which would 1) require the state to request federal approval for the Managed Care Organization tax on an ongoing basis and 2) allocate those dollars for certain health care investments.

Access to health care is essential for everyone to be healthy and thrive. In California, Medi-Cal, the state’s Medicaid program, provides free or low-cost health care to over one-third of the state’s population. Medi-Cal covers a wide range of services to Californians with modest incomes, and many children, seniors, people with disabilities, and pregnant individuals rely on it. About half of Medi-Cal beneficiaries are Latinx, highlighting Medi-Cal’s role in promoting health equity.

California’s shortage of health care workers undermines the availability and quality of care for communities across the state. When people can’t find a provider in their area or experience long wait times for appointments, they don’t have meaningful access to health care. Enrolling in Medi-Cal and navigating the health care system can also be difficult, underscoring the need to invest in outreach and enrollment supports. While state policymakers have made considerable investments in recent years to bolster the health care workforce, more progress is needed.

what is health equity?

When everyone has the opportunity to be as healthy as possible and no one is disadvantaged from achieving this because of their race, gender identity, sexual orientation, the neighborhood they live in, or any other socially defined circumstance.

This year, policymakers had to make challenging decisions about health care investments due to the state’s recent budget shortfall and resistance from some state leaders to raise ongoing revenues. This has led to debates over the allocation of revenue from the state’s recently approved Managed Care Organization (MCO) tax. In response, many representatives of the health care industry have proposed Proposition 35, which would: 

  1. Require the state to request federal approval for the MCO tax on an ongoing basis.
  2. Allocate MCO tax revenue for certain health care investments.

There are merits to having dedicated funding to invest in the state’s health care system. However, this approach would reduce flexibility in the state budget and could negatively affect available funding for other key services that improve the lives of Californians. This Q&A provides a high-level overview of Prop. 35, including how Californians with low incomes might be impacted by its passage as well as implications for the state budget.

What is the Managed Care Organization (MCO) tax?

Managed Care Organizations (MCOs), also known as health insurance plans, are responsible for managing health care services as a way to control costs, utilization, and quality of care. Anthem Blue Shield and Kaiser Permanente are two examples of MCOs in California. These health insurance plans oversee the health care benefits that people receive, often requiring prior authorization or referrals to ensure that people receive appropriate and cost-effective care.

MCOs manage health care services for people with private health insurance as well as Medi-Cal enrollees. They contract with Medi-Cal to receive payments based on the number of Medi-Cal recipients they serve. Medi-Cal is a joint federal-state program, with the federal government covering part of the cost and the state covering the rest.

Federal law allows states to impose a tax on MCOs and other health-related services to help cover the state share of Medicaid health care costs, but states must comply with federal regulations and receive federal approval for these taxes. Eighteen states reported having an MCO tax in place during the 2023 state fiscal year.

California’s MCO tax is a charge based on enrollment in Medi-Cal managed care plans and private health insurance plans. The MCO tax is distinct from other types of state taxes in that the primary state fiscal benefit comes from the additional federal dollars drawn down as a result of the tax. MCOs bear very little of the cost, as they receive Medi-Cal payments from state and federal funds that offset the portion of the tax levied on Medi-Cal enrollment. By drawing down additional federal funding, the MCO tax frees up state General Fund dollars that would otherwise have been used to support existing Medi-Cal services.

California’s MCO tax was most recently approved in December 2023, and it will expire at the end of 2026 unless it is renewed again. However, state leaders are seeking additional changes to the MCO tax structure to draw down more federal funding. These changes are still pending federal approval.

The state is expected to receive net revenues of $7 billion to $8 billion annually while the tax is in effect, assuming the federal government approves recent changes. Essentially, the net revenues are the additional federal funds the state is able to draw down minus the cost of the state’s portion of payments to MCOs to offset the cost of the tax. Under the enacted 2024-25 budget, most of that revenue will be used to offset state General Fund spending on existing Medi-Cal services, with a smaller portion going to increased provider rates and augmentations.

How do policymakers currently plan to use MCO tax dollars?

Policymakers outlined a plan — which Prop. 35 would overturn — to use revenue from the MCO tax in the 2024-25 budget package, with the majority of dollars allocated to offset General Fund spending on Medi-Cal and maintain existing services in the program. Assuming that the federal government approves the changes to the MCO tax that state leaders are seeking, the budget includes the following MCO tax dollars to sustain existing services in Medi-Cal:

  • $6.9 billion in 2024-25
  • $6.6 billion in 2025-26
  • $5.0 billion in 2026-27

Policymakers also allocated funding from the MCO tax for new targeted Medi-Cal provider rate increases as well as other investments. These budget allocations include:

  • $133 million in 2024-25
  • $728 million in 2025-26
  • $1.2 billion in 2026-27

The rate increases from the current MCO tax spending plan are intended to build on investments that policymakers made in previous years. As shown below, the majority of funds for rate increases that will go into effect on January 1, 2025 will support emergency department physician services, abortion care and family planning, and ground emergency medical transportation.

The current MCO tax spending plan also includes additional rate increases and investments that would take effect on January 1, 2026, with the vast majority of dollars allocated to physician and non-physician professionals (e.g., physician assistants, nurse practitioners and certified nurse midwives). 

Policymakers also allocated $40 million one-time MCO tax dollars in 2026-27 to strengthen and support the development and retention of the Medi-Cal workforce. This amount reflects a decrease in health care workforce investments that state leaders made in the past. More substantial and sustained investments are necessary to build a health care workforce that can better meet the needs of Californians.

This MCO tax spending plan would be overturned if voters approve Prop. 35.

How does Prop. 35 differ from the current MCO tax plan?

Prop. 35 proposes a major shift to how state policymakers have used MCO tax revenue to essentially reduce, or offset, General Fund spending on Medi-Cal. If passed, Prop. 35 would overturn the current MCO tax spending plan that policymakers agreed upon in the 2024-25 budget. 

Prop. 35 would require the California Department of Health Care Services to request federal approval for the MCO tax on an ongoing basis in an attempt to make this funding stream more permanent. Federal approval is required for the state to levy health care taxes that draw down additional federal dollars. 

While Prop. 35 provides some flexibility for the state to structure future versions of MCO tax proposals to comply with federal regulations and ensure federal approval, it does set limits to the tax on commercial enrollment. This limitation could affect the state's ability to secure future approval for a tax that generates the same level of revenue as the current tax. The measure also specifies that the MCO tax would not go into effect if the state does not receive federal approval and federal funding in the future.

Additionally, Prop. 35 would establish rules for how MCO tax revenue would be spent in the short term (2025 and 2026) and long term (2027 and beyond). The key difference is that policymakers would no longer be able to use the bulk of the dollars to offset General Fund spending in Medi-Cal. Another notable difference is that Prop. 35 would require funds to be spent by the end of each calendar year or fiscal year, beginning 2027. Currently, policymakers have the flexibility to save funds for future years to help cover costs if the MCO tax is not approved in the future. 

If passed, funds would first cover a portion of MCOs’ cost of the tax as well as administrative costs. 

For calendar years 2025 and 2026, $2 billion would be used to offset General Fund spending in Medi-Cal. Specifically, this amount would cover a portion of the non-federal share of Medi-Cal managed care rates for health care services for children, adults, seniors, and people with disabilities. This represents the majority of funds (about 43%), as shown below. MCO tax revenue would also support health workforce initiatives, including primary care, specialty care, and emergency care.

For calendar year 2027 and beyond, Prop. 35 would allocate revenue from the MCO tax differently. After covering a portion of MCOs’ cost of the tax as well as administrative costs, the next $4.3 billion collected from the tax would be allocated for specific purposes. The majority of funds (44%) would support access to primary care and specialty care. Specifically, it would increase reimbursement rates for primary care services and increase the number of specialty care service providers. A smaller portion of funds would support other rate increases, such as emergency department services and family planning. Prop. 35 would allow the Department of Health Care Services to allocate 8% of funds — $344 million — to provide overall support to the Medi-Cal program.

If there are remaining MCO tax revenues after these funding allocations are made, the measure contains parameters to allocate the excess revenue. Examples of these other allocations include:

  • Additional General Fund offset to support existing services in Medi-Cal.
  • A grant program to expand the number of community health workers. 
  • Supporting the state’s ongoing efforts to reduce the cost of prescription drugs.
  • Providing additional funding to health workforce initiatives.

In addition, Prop. 35 would establish oversight and accountability measures, requiring the state controller to perform independent financial audits. It would also create an advisory committee that would provide input to the Department of Health Care Services on future MCO tax proposals. This advisory committee would be made up of mostly health care provider representatives.

Would Prop. 35 actually make the MCO tax permanent?

No, the MCO tax funding structure under Prop. 35 is entirely dependent on federal approval and ongoing renewals. Prop. 35 would require the California Department of Health Care Services to request federal approval for the MCO tax on an ongoing basis in an attempt to make this funding stream more permanent. Federal approval is required for the state to levy health care taxes that draw down additional federal dollars.

One issue with Prop. 35 is that the MCO tax may not be a sustainable, long-term funding source. While the federal government has historically approved California’s MCO tax, it has indicated that it may revise the rules governing state MCO taxes in the future, which would have implications for the amount of net revenue that future versions of the tax may bring into the state. 

Without federal approval and federal funding, the MCO tax and spending plan under Prop. 35 would not be implemented.

How would Prop. 35 impact the state budget?

While Prop. 35 would ensure more funding is dedicated for health care, its requirement to spend MCO tax revenues on specific services would also limit policymakers’ flexibility in making budget decisions. This is particularly concerning in years when the state is facing a budget shortfall because the reduced flexibility could lead policymakers to make cuts to other critical public services to balance the budget.

State leaders are required to balance the budget each year, and there are already several strict requirements on how some state funds are spent that make budgeting complex. By creating additional mandates on state spending, Prop. 35 would result in policymakers having even less flexibility in making budget decisions. While the measure gives policymakers some ability to modify the structure and uses of the MCO tax, changes would require a three-fourths vote in the Legislature — which can be difficult to obtain — and would need to further the purpose of Prop. 35. 

In years when the state is facing a budget shortfall, this limited flexibility could result in cuts to other critical public services that help Californians make ends meet and address vital needs, such as income supports, subsidized child care, food assistance, and investments in reducing homelessness and increasing affordable housing.  

Of course, cuts could be limited or avoided during budget deficits if state leaders are able to raise new revenues to address a shortfall. However, the state Constitution requires a two-thirds vote in the Legislature to raise taxes, while spending cuts can be approved with a simple majority, and state leaders have generally been more inclined to make cuts than to increase taxes.

In the near term, Prop. 35 would result in the recently enacted 2024-25 budget being out of balance. This is because a solution to the budget shortfall involves using some MCO tax dollars that were previously intended to support provider rate increases and other augmentations to instead offset General Fund spending on existing Medi-Cal services. Since Prop. 35 would require MCO tax revenues to be used for health program augmentations instead of offsetting existing spending, state leaders would have to identify other solutions — potentially spending cuts or delays, revenue increases, or additional budget reserve withdrawals — in next year’s budget to cover the difference. The Legislative Analyst’s Office estimates that the General Fund impact would be between $1 billion and $2 billion in 2025 and 2026, but in a legislative hearing on August 13, 2024, the Department of Finance noted that it estimates the impact could range from $2.6 billion and $4.9 billion in fiscal years 2024-25 through 2026-27.

In the long term, raising state General Fund revenues — through sources aside from the MCO tax — would help to increase the state’s capacity to cover the costs of existing Medi-Cal services and improve state health services and increase access to care, without jeopardizing other state services. This is especially important given that there is no guarantee the federal government will continue to approve an MCO tax that yields the amount of revenue anticipated from the currently authorized tax.

How would Prop. 35 impact Californians?

If passed, millions of Californians who receive health care services through Medi-Cal — about half of whom are Latinx — could have better access to care, especially for primary care and specialty health care services. Increasing provider participation in Medi-Cal is critical to improving access to a wide range of health care services, especially in historically underserved areas where there is often a shortage of providers. By increasing the number of providers in the Medi-Cal network, patients can receive more timely care, which can help improve health and well-being for all Californians, but especially Latinx communities. 

However, there are some critical health equity investments that are included in the current MCO tax spending plan that are either not included or not prioritized in Prop. 35. Examples include:

These potential cuts raise health equity concerns, as they would disproportionately impact people of color, children, older adults, and people with disabilities. Policymakers should explore alternative revenue-raising measures to sustain and advance these crucial health equity initiatives, if Prop. 35 passes.

Additionally, Prop. 35’s limitations on using MCO tax proceeds to offset General Fund spending on current Medi-Cal services could make policymakers more likely to make cuts to other state services when facing budget shortfalls. Such cuts would likely harm Californians with low incomes most. For example, in the difficult budget years during and following the Great Recession, deep cuts were made to safety net programs such as subsidized child care, income supports for families under the California Work Opportunity and Responsibility to Kids (CalWORKs) program, and income support for older adults and people with disabilities under the Supplemental Security Income/State Supplementary Payment (SSI/SSP) program.

Lastly, the passage of Prop. 35 would lock in spending decisions in the future, which would impact how Californians engage with the state budget process. Advocates and community members would have less opportunity to weigh in on how state resources should be allocated because the MCO tax spending decisions would be constrained by the ballot measure. Currently, Californians can contribute to conversations about how MCO tax revenue should be spent during the budget process via public hearings and interactions with policymakers.

What are arguments for and against Prop. 35?

Supporters of Prop. 35 believe the measure will protect and enhance access to care for Medi-Cal patients by ensuring that MCO tax dollars are directed toward patient care. They argue that it would prevent lawmakers from redirecting funds intended for health care to other purposes. Key supporters include the California Medical Association, Planned Parenthood Affiliates of California, the California Hospital Association, the California Primary Care Association, and the California Dental Association.

Opponents of Prop. 35 argue that the measure would reduce flexibility in how Medi-Cal dollars are allocated and overturn the commitments made in the 2024-25 budget to fund important services with MCO tax dollars, including continuous Medi-Cal coverage for young children and the rate increase for community health workers. Opposition groups include The Children’s Partnership, the California Pan-Ethnic Health Network, the California Alliance for Retired Americans, Courage California, and the League of Women Voters of California.

Stay in the know.

Join our email list!

key takeaway

California voters will decide on November 5th, 2024, whether to pass Proposition 36, which would increase penalties for several drug and theft crimes. This would significantly drive up state prison costs, cut funding for behavioral health treatment and other critical services, and potentially push more Californians into homelessness.

Introduction

Over many years, California lawmakers and voters adopted harsh, one-size-fits-all sentencing laws that prioritized punishment over rehabilitation, led to severe overcrowding in state prisons, and disproportionately impacted Californians of color.

California began reconsidering its “tough on crime” approach in the late 2000s. Multiple reforms were adopted as prison overcrowding reached crisis proportions and the state faced lawsuits filed on behalf of incarcerated adults. These reforms worked as intended: The number of adults serving sentences at the state level fell from a peak of 173,600 in 2007 to around 90,000 today. Meanwhile, violent and property crime rates in California remain well below historical peaks. 

A key justice system reform was Proposition 47, which passed with nearly 60% support in 2014. Prop. 47 reduced penalties for six nonviolent drug and property crimes from felonies to misdemeanors. As a result, state prison generally is no longer a sentencing option for these crimes. Instead, people convicted of a Prop. 47 offense serve their sentence in county jail and/or receive probation.

Prop. 47 also requires the state to calculate prison savings due to reduced incarceration and use those dollars to reduce recidivism and support crime victims. Since 2016, over $800 million in Prop. 47 savings has been allocated across the state for behavioral health treatment and other critical services that promote community safety.

However, interest groups opposed to justice system reforms qualified Prop. 36 for the November ballot. Their goal is to increase punishment for drug and theft crimes in California, including by reversing key provisions of Prop. 47. Major donors to Prop. 36 include Walmart ($2.5 million), Home Depot ($1 million), Target ($1 million), In-N-Out Burger ($500,000), the California Correctional Peace Officers Association ($300,000), and Macy’s ($215,000).

Prop. 36 Would Increase Penalties for Several Drug and Theft Crimes

Prop. 36 would amend state law to increase penalties for several drug and theft crimes. These changes would disproportionately impact Californians of color given racist practices in the justice system as well as social and economic disadvantages that communities of color continue to face due to historical and ongoing discrimination and exclusion.

Prop. 36 would increase penalties for drug crimes in multiple ways. Key drug-related provisions of the measure include the following:

Prop. 36 also would increase penalties for theft crimes in multiple ways. Key theft-related provisions of the measure include the following:

Prop. 36 Would Drive Up State Prison Spending and Create Unfunded Costs at the State and Local Levels

By increasing punishment for several drug and theft crimes, Prop. 36 would create substantial new costs — including for incarceration and the court system — at the state and local levels. However, the measure would provide no new revenue to pay for these expenses.1Prop. 36 states that a person charged with a “treatment-mandated felony” may receive, if eligible, relevant Medi-Cal or Medicare services that are delivered through a court-ordered treatment program. (Medi-Cal is supported with state and federal funding; Medicare is funded solely by the federal government.) Therefore, some federal funding could be available to support services for people who are charged with a treatment-mandated felony and are eligible for Medi-Cal or Medicare. However, the state would have to pay a portion of any Medi-Cal services delivered, and Prop. 36 would not provide any revenue to offset those new state costs. In addition, the costs associated with treatment-mandated felonies represent only part of the substantial state and local criminal justice costs that Prop. 36 would create — costs for which the measure provides no new funding. State and local leaders would face the prospect of curtailing funding for existing public services in order to make room in their budgets for the unfunded costs imposed by Prop. 36.

While Prop. 36 would clearly burden public budgets, the magnitude of the impact is uncertain. Cost estimates have been developed by the nonpartisan Legislative Analyst’s Office (LAO) as well as by Californians for Safety and Justice (CSJ), a leading statewide public safety advocacy group. Both organizations suggest that the cost of Prop. 36 could be substantial, although the LAO’s estimates are significantly lower than CSJ’s.2The substantial gap between these two sets of estimates is likely the result of different assumptions, methodologies, and/or data sources adopted by each organization.

Specifically:

  • The LAO estimates that the ongoing increase in state criminal justice costs would likely range from several tens of millions of dollars to the low hundreds of millions of dollars. This estimate reflects a larger prison population — which could grow by “around a few thousand people” — as well as an increase in state court workload.
  • In addition, the LAO estimates that ongoing local criminal justice costs would likely increase by tens of millions of dollars due to Prop. 36. This estimate reflects larger county jail and community supervision populations — which, combined, could rise by “around a few thousand people” — as well as higher costs for courts, prosecutors, public defenders, and county agencies like probation and behavioral health departments.
  • In contrast, CSJ projects that Prop. 36 would lead to much higher costs. CSJ estimates that combined state and local costs would rise by around $4.5 billion ongoing. For example, CSJ suggests that more than 32,000 additional people would be sentenced to state prison within seven years. CSJ also assumes that over 31,000 additional people would serve one-year sentences in jail each year. These projected increases in incarceration are much higher than what the LAO’s analysis suggests.

Regardless of the magnitude of the costs created by Prop. 36, the result would be the same: elected officials would face difficult choices about how to accommodate these new unfunded costs in their budgets. Such choices could disproportionately harm Californians with low incomes and communities of color depending on which current state and local services were affected by funding reductions.

These tough decisions would come at a time when state and local leaders are already struggling to keep their budgets balanced and ensure ongoing support for core services. For example, the 2024-25 state budget package relies heavily on borrowing from future budgets and only temporarily increases revenues — decisions that could compromise the state’s ability to sustain core programs as well as stall much-needed investments in the coming years. The new unfunded costs imposed by Prop. 36 would make it even more challenging for state leaders to sustain support for core services and maintain a balanced budget.

In addition, Prop. 36 would reverse the modest progress that California has made in controlling state prison spending. Justice system reforms, including Prop. 47, have reduced the prison population and allowed state leaders to end private-prison contracts, begin closing state-owned prisons, and bend the prison cost curve. In fact, prison spending is billions of dollars lower today than it would be absent these reforms. These freed-up dollars have been redirected to critical state services that rely on the state’s General Fund for support.

Moreover, the prison system’s “footprint” on the state budget has been shrinking as reforms have taken effect. The budget of the California Department of Corrections and Rehabilitation (CDCR) comprised over 9% of total General Fund spending in 2013-14 — the fiscal year before Prop. 47 was approved in November 2014. Since then, CDCR’s share of the state budget has dropped to less than 7% as prison spending has grown more slowly than overall state expenditures.

Still, state correctional spending remains too high, and more work is needed to further downsize California’s costly and sprawling prison system. However, the trend has been moving in the right direction, and the significant gains that have been made over the last decade would be eroded if Prop. 36 is approved by voters.

Prop. 36 Would Reduce State Funding for Behavioral Health Treatment and Other Critical Services

By passing Prop. 47 in 2014, voters not only reduced penalties for several low-level crimes and lowered the prison population — they also required state prison savings from Prop. 47 be used for services that reduce crime, support youth, and help crime victims heal. To date, Prop. 47 savings — as calculated by the Department of Finance — exceed $800 million, or around $90 million per year, on average.

Prop. 47 savings are annually deposited into the Safe Neighborhoods and Schools Fund and used as follows:

  • 65% for behavioral health services — which includes mental health services and substance use treatment — as well as diversion programs for individuals who have been arrested, charged, or convicted of crimes. These funds are distributed as competitive grants administered by the Board of State and Community Corrections.
  • 25% for K-12 school programs to support vulnerable youth. These funds are distributed as competitive grants administered by the California Department of Education.
  • 10% to trauma recovery services for crime victims. These funds are distributed as competitive grants administered by the California Victim Compensation Board.

Prop. 47 savings are invested in a broad range of programs that support healing and keep communities safe. For example, a recent evaluation shows that people who received Prop. 47-funded behavioral health services and/or participated in diversion programs were much less likely to be convicted of a new crime. People who enrolled in these programs had a recidivism rate of just 15.3% — two to three times lower than is typical for people who have served prison sentences (recidivism rates range from 35% to 45% for these individuals). These programs are also successful in reducing homelessness and promoting housing stability, with a 60% decrease in the number of participants experiencing homelessness by the end of the program compared to when they enrolled.

Because Prop. 36 would undo key provisions of Prop. 47, the annual state savings from Prop. 47 would decline. The LAO estimates that this reduction would likely be in the low tens of millions of dollars per year, whereas CSJ projects that the state savings would be entirely eliminated.

The most recent estimate of Prop. 47 savings is $95 million, as reflected in the 2024-25 state budget. If Prop. 36 had been in effect this year, these savings would have been tens of millions of dollars lower (based on the LAO’s analysis) or entirely eliminated (based on CSJ’s assessment). Either way, there would be substantially less funding for services that reduce crime, support youth, and help crime victims heal. In other words, Prop. 36 would shift tens of millions of dollars or more each year from behavioral health treatment and other critical services back to the state prison system.

Prop. 36 Could Push More Californians Into Homelessness

Prop. 36 could worsen homelessness in California by pushing more residents into the carceral system, further exacerbating the deep link between homelessness and incarceration. While the lack of affordable housing is the primary cause of homelessness, this detrimental outcome is intensified by incarceration as formerly incarcerated people are nearly 10 times more likely  to experience homelessness than the general population. 

Californians leaving incarceration often face significant obstacles to securing long-term, stable housing, which is essential for reconnecting with support networks, finding employment, and maintaining health. Without proper housing, which Prop. 36 does not account for or ensure, formerly incarcerated individuals are more likely to recidivate and resort to survival crimes, perpetuating the harmful cycle.

A recent statewide homelessness study found that nearly 1 in 5 unhoused Californians (19%) entered homelessness directly from an institutional setting, primarily a jail or prison. Additionally, fewer than 20% of people leaving jail or prison had support finding housing upon their release. Prop. 36 does nothing to address this need and instead reverts funding from existing programs that help unhoused individuals with conviction histories connect with housing, behavioral health treatment, and other necessary services needed to reintegrate.

Further, Prop. 36 fails to follow effective, evidence-based interventions that successfully help individuals obtain and sustain mental health and substance use treatment, with housing as a foundational component. The initiative allows certain people arrested for drug possession to admit guilt (or plead no contest) and have their charges dismissed if they complete court-ordered treatment.

However, completing a treatment program is especially challenging for individuals experiencing housing instability or homelessness. Not having a home causes severe stress and trauma and harms physical and mental well-being, which can trigger or worsen mental health issues and lead to complex coping mechanisms like substance use. Yet there is no guarantee that those who are referred to treatment and who may need housing will receive it in a timely manner, essentially curtailing their chances of completing the program and increasing their likelihood of facing incarceration for up to three years.

Moreover, coerced treatment is antithetical to successful “Housing First” principles, which prioritize permanent housing before addressing treatment and other comprehensive needs. Policy experts also recommend against legally compelling people to comply with treatment for opioid use disorders as an alternative to other sanctions like incarceration. While coerced treatment may help engage people with substance use challenges, it likely has minimal to no effect on treatment retention, remission, and overdose mortality. This approach effectively places individuals in vulnerable positions that can lead to long-term incarceration and an increased likelihood of homelessness under Prop. 36.

Creating Safe and Equitable Communities Requires Smart Investments, Not Harsh Penalties and Mass Incarceration

Creating safe, vibrant communities for all Californians is achievable through intentional investments that uplift opportunities and economic security. Rather than promoting this positive vision for California, Prop. 36 advances an incarceration-focused approach that:

Instead of increasing incarceration, state leaders should prioritize policies and interventions proven to reduce crime, enhance public safety, and expand behavioral health treatment options. Effective measures include increasing affordable and supportive housing, expanding economic security programs, broadening access to health care and behavioral health services, supporting education and youth intervention programs, improving recidivism reduction strategies, and implementing equity-centered policies that target vulnerable residents. By focusing on these proven strategies, we can create safer, more equitable communities for all Californians.

  • 1
    Prop. 36 states that a person charged with a “treatment-mandated felony” may receive, if eligible, relevant Medi-Cal or Medicare services that are delivered through a court-ordered treatment program. (Medi-Cal is supported with state and federal funding; Medicare is funded solely by the federal government.) Therefore, some federal funding could be available to support services for people who are charged with a treatment-mandated felony and are eligible for Medi-Cal or Medicare. However, the state would have to pay a portion of any Medi-Cal services delivered, and Prop. 36 would not provide any revenue to offset those new state costs. In addition, the costs associated with treatment-mandated felonies represent only part of the substantial state and local criminal justice costs that Prop. 36 would create — costs for which the measure provides no new funding.
  • 2
    The substantial gap between these two sets of estimates is likely the result of different assumptions, methodologies, and/or data sources adopted by each organization.

Stay in the know.

Join our email list!