Prop. 42 would prohibit new taxes on the ownership of certain assets as well as taxes that apply retroactively. The primary intent of the measure is to invalidate Prop. 40 — the one-time billionaire tax measure also appearing on the November ballot — if it receives more votes, and it would also create new barriers to raising progressive state revenue in the future to adequately meet the needs of Californians.
What Would Prop. 42 Do?
Prop. 42 would amend the state Constitution to prohibit taxes on the ownership of certain assets and on certain retroactive taxes.
Prohibition on New Taxes on Assets
Prop. 42 would prohibit the imposition of any new state tax — enacted on or after January 1, 2026 — on the ownership of financial assets (such as bank accounts, stocks, bonds, or mutual funds), retirement accounts, interests in businesses, intellectual property, and other personal property (such as vehicles, jewelry, artwork, and other movable, physical property).
Prohibition on Retroactive Taxes
Prop. 42 would prohibit the imposition of new retroactive taxes, specifically any tax that is based on “conduct, activities, or a status” that preceded the effective date of the tax. The measure also explicitly prohibits taxes based on someone’s residency status prior to the tax going into effect. An exception would be made for retroactive taxes in cases where the revenues would be used to respond to a governor-declared emergency and the tax does not apply retroactively for more than one year before the effective date.
What Would Prop. 42 Mean for Californians and the State Budget?
The primary intent of Prop. 42 is to invalidate Prop. 40, which would create a one-time tax on the wealth of billionaires. The tax would apply retroactively to billionaires who were California residents on January 1, 2026 and would apply to financial assets like stocks and bonds and other types of assets that would put it in direct conflict with Prop. 42’s prohibition of such taxes — though Prop. 40 would exclude retirement accounts, which is a key focus of Prop. 42. If both measures were to pass and Prop. 42 received more votes, Prop. 40 would likely be invalidated.
But the measure would also have more far-reaching consequences by making it harder for state leaders to raise revenues from wealthy households to effectively meet the needs of Californians and to quickly adapt to changing circumstances.
This would come at a time when California is facing challenges on multiple fronts — the consequences of the steep federal cuts to health care and food assistance enacted in H.R. 1, the sustained high poverty rate, the ongoing housing affordability and homelessness crises, and rising costs of maintaining current services due to inflation and an aging population. Addressing these issues and ensuring California communities can thrive will require the state to substantially raise ongoing revenues.
While Prop. 42 would reduce the options state policymakers have to increase revenues, California voters may still be able to amend the state Constitution in the future to allow a new tax on assets or one that applied retroactively. However, legal challenges are possible and there is no absolute certainty on how courts would rule.
Impacts of Prohibition on Taxing Assets
Currently, the ownership of assets is generally not taxed in California, with the exception of local property taxes on real estate — already subject to strict constitutional limits under Prop. 13 (1978) — and some types of personal property including boats, planes, and business equipment, as well as state vehicle license fees.
While the state does not currently tax the ownership of financial assets, business interests, or other intangible assets, it is not constitutionally barred from doing so. Prop. 42 would enshrine this prohibition in the state Constitution, which would prevent state leaders from creating wealth-based taxes in the future. This would limit the options policymakers have to raise progressive revenue to maintain and improve state services that support Californians in staying healthy, housed, and economically secure.
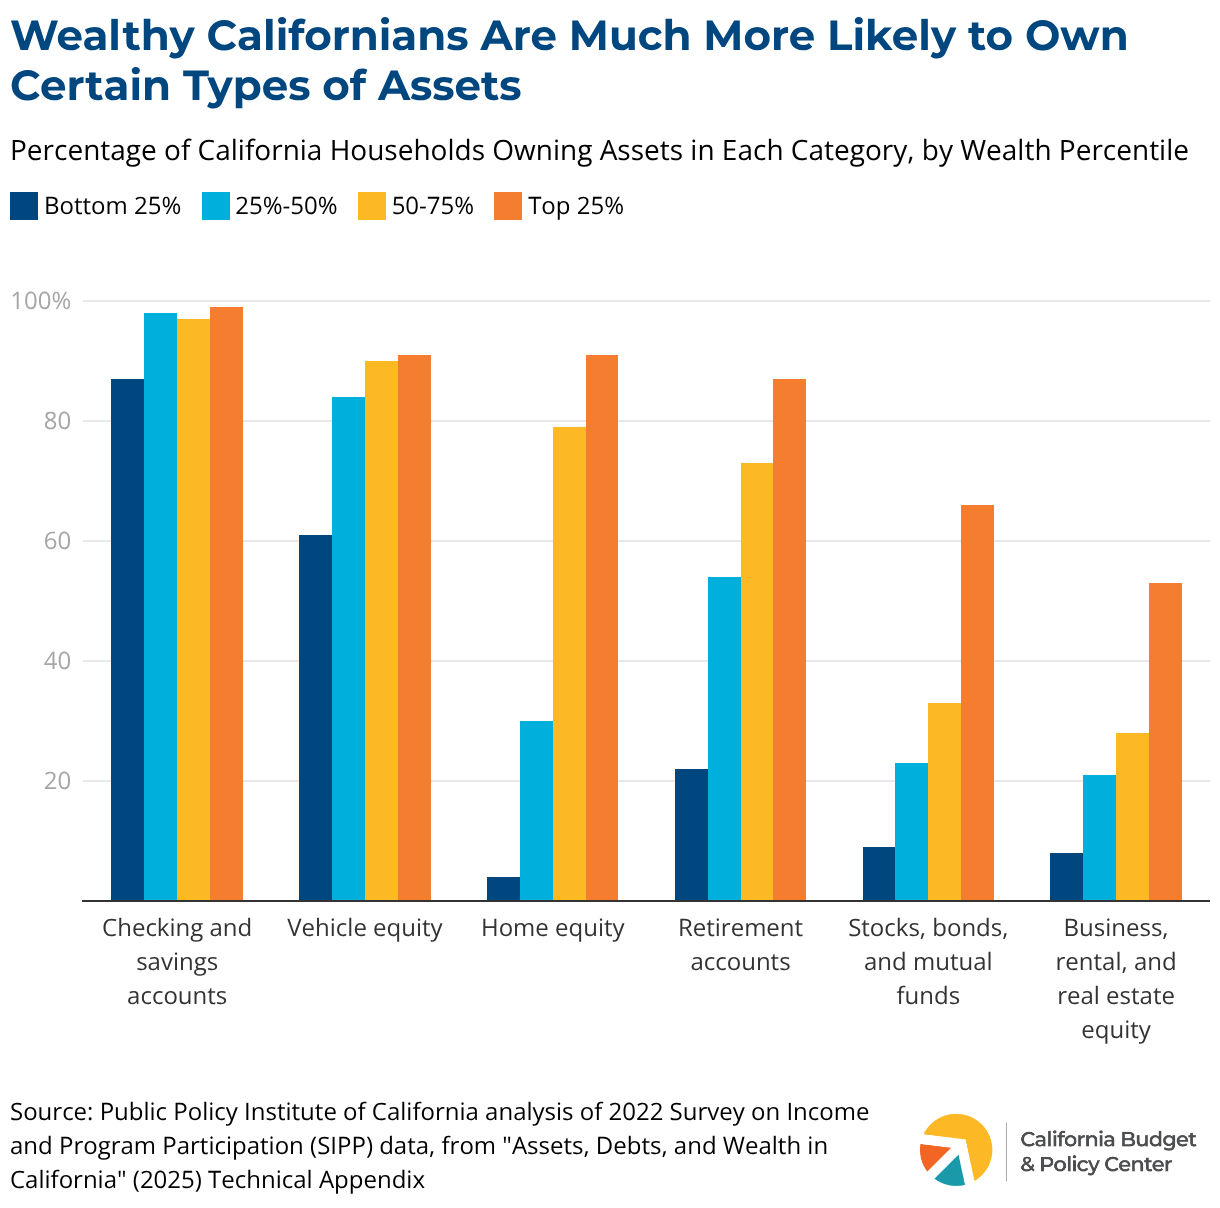
While most Californians hold assets in some form, such as checking or savings accounts, some types of assets are far more likely to be held by wealthy households. For example, about two-thirds of Californians in the top 25% of the wealth distribution hold stocks, bonds, or mutual funds, compared to only 9% of Californians in the bottom 25%, according to an analysis by the Public Policy Institute of California.
Current federal and state tax policies allow some large wealth increases to never be taxed. California — like the federal government — only taxes the income people receive when they sell their assets, but does not tax the growth in value of assets they hold onto. This growth is known as an unrealized capital gain, and for very wealthy households, unrealized capital gains make up a large share of their total wealth. Some wealthy people may even be able to avoid paying income taxes entirely in some years by not taking a salary, not selling any stocks or other assets, and simply borrowing against their wealth to pay their bills.
Additionally, if someone holds onto assets until their death, their heirs do not have to pay any tax on the gain due to a provision in both federal and state law known as “stepped-up basis,” estimated to cost California around $5 billion each year.
For these reasons, broadly prohibiting state leaders from enacting any new taxes on assets would narrow the options available to ensure that the wealthiest Californians pay their fair share to support the services that benefit residents across the state.
Impacts of Prohibition on Retroactive Taxes
Many federal and state tax law changes have modest retroactivity periods, such as looking back to the beginning of a tax year. This has the benefit of reducing taxpayers’ ability to engage in activities to avoid or evade the tax before it goes into effect, which would reduce the revenue potential. Looking back to the start of the current tax year can also more immediately raise revenues when there are urgent needs.
Broadly prohibiting retroactive taxation would hamstring the ability of state leaders to enact effective and timely tax policy changes that raise revenues needed to meet the needs of Californians.
Who Supports and Opposes Prop. 42?
The top contributor to the Prop. 41 campaign is a group called “Building a Better California,” which is largely funded by Google cofounder Sergey Brin and other billionaires. This group is also opposing Prop. 40 and supporting Prop. 41. The measure is also endorsed by the California Republican Party, the California Chamber of Commerce, the California Taxpayers Association, the California Professional Firefighters, and the State Building & Construction Trades Council of California.
There is no official opposition campaign for Prop. 41, but prominent opponents include the Service Employees International Union – United Health Workers West (SEIU-UHW) — the main proponent of the Prop. 40 billionaire tax measure — as well as other labor groups including the California Federation of Teachers and the California Federation of Labor Unions. The California Democratic Party and the League of Women Voters are also opposed.
Curious About Other Ballot Propositions?
Browse our collection of resources covering California’s statewide ballot measures to help you understand what’s at stake for California this November.
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
key takeaway
Prop. 41 would 1) impose new audit requirements for programs funded with state special taxes and 2) prohibit the collection of new state taxes that are excluded from the state’s spending limit. The primary intent of the measure is to invalidate Prop. 40 — the billionaire tax also appearing on the November ballot — but Prop. 41 could also make it harder for the state to meet the needs of Californians in the future.
What Would Prop. 41 Do?
Prop. 41 would amend the state Constitution to impose new rules related to state taxes. The measure would require “financial and performance audits” of programs receiving revenues from special taxes and would also prevent state taxes from being excluded from California’s spending cap, also known as the “Gann Limit.”
Creates New Audit Requirements for Special Taxes
Prop. 41 would create new pre-election and ongoing audit requirements for programs receiving — or proposed to receive — revenues from state-level special taxes. In contrast to a general tax, which can be used for any purpose, a special tax raises revenue for specific purposes.
Pre-election audits: The State Auditor would be required to perform an audit of any program that would be funded by a special tax proposed through a statewide voter initiative. The audit would be required while the initiative is being circulated for signatures — before it officially qualifies for the ballot — and a summary of the audit findings would be included in the voter information guide. The full audit would also be made available to the public.
Ongoing audits: The State Auditor would be required to audit programs receiving revenues from special taxes enacted by the Legislature or approved by voters through a statewide initiative on or after January 1, 2026. These audits would be required every four years.
The audits would assess programs based on specific criteria outlined in Prop. 41, and would require the State Auditor to recommend how programs could reduce costs by at least 10% annually.
The State Auditor would be reimbursed for the costs of these audits with revenues from the relevant special tax. If, however, a special tax initiative fails to qualify for the ballot or is rejected by voters, the audit costs would be absorbed by the state’s General Fund.
Prohibits Taxes That Are Excluded from the State Spending Limit
Prop. 41 would prevent the state from collecting or enforcing any state tax that is 1) enacted on or after January 1, 2026 and 2) excluded from the state spending cap, also known as the Gann Limit. Currently, the measure would apply only to Prop. 40 if both measures pass and Prop. 41 receives more votes, but it could potentially be applied to other tax policy proposals in the future.
California’s spending limit was established by Prop. 4 (1979) and is based on state spending in 1978-79, annually adjusted for population changes and inflation. Under the state Constitution, if state revenues exceed the limit over two consecutive years, the excess must be split equally between refunds to taxpayers and spending on TK-14 education. In effect, the spending limit restricts the ability of state leaders to raise and spend revenue to meet the most pressing needs of Californians.
Conflicts with Other Measures on the Ballot
The California Constitution states that if provisions of multiple measures on the same ballot conflict, the provisions of the measure receiving the higher number of votes will prevail. Prop. 41 broadly specifies that if another measure on the same ballot either 1) imposes different audit rules on special taxes or 2) contains a tax that is exempted from the state spending limit, the entirety of the other measure would be invalidated if Prop. 41 receives more votes.
Prop. 41 is in direct conflict with Prop. 40. This is because Prop. 40 would create a one-time tax on the wealth of billionaires and exclude the revenues from the state spending limit, which Prop. 41 prohibits.
If both measures were to be approved and Prop. 41 received more votes, Prop. 40 could be invalidated. Alternatively, if both measures pass but Prop. 40 receives more votes, the billionaire tax could be collected, but it is possible that audits would be required of Medi-Cal and other programs receiving Prop. 40 dollars. If both measures pass, there may be litigation regarding the application of conflicting provisions, and the final decision would be made by the courts.
How Would Prop. 41 Affect Californians and the State Budget?
The primary intent of Prop. 41 is to invalidate the Prop. 40 billionaire tax, but it would also create new barriers to raising state revenue and effectively meeting the needs of Californians.
Prop. 41 would also increase state costs related to conducting audits for programs that are often already subject to close scrutiny — reducing funding available to support critical state services. This would come at a time when Californians are already dealing with affordability concerns as well as the consequences of the steep federal cuts to health care and food assistance enacted in H.R. 1, signed by President Trump in 2025.
Impacts of Audit Requirements
The pre-election audit requirement could dissuade voters from approving special tax initiatives that would raise needed revenue to support and improve state services that help Californians stay healthy, housed, and economically secure. A summary of the audit would appear in the voter guide, and voters could interpret it as evidence that the programs to be funded are inefficient or ineffective. For example, because the State Auditor would be required to recommend options to cut program costs by 10%, voters may assume this means the program is inefficient even if that is not the case.
Additionally, the requirement for cost-cutting recommendations could result in service cuts with real human impacts. While policymakers would be under no obligation to implement these recommendations, if they did it could result in cuts to core services rather than simply “inefficient spending.” For example, if a program receiving special tax revenues is already operating efficiently but the Auditor must identify ways that costs could be reduced by 10%, lawmakers may be under pressure to adopt those recommendations — particularly in difficult budget times. Those cuts could lead to fewer Californians being served, reductions in benefit levels, or decreased service quality.
While it is clearly important for tax dollars to be spent efficiently and effectively, many state programs are already subject to occasional or ongoing audits. The State Auditor currently performs audits as a result of existing state laws, legislative requests, and whistleblower tips. Additionally, the “High-Risk” audit program requires the Auditor to periodically review programs or agencies determined to be at high risk for “waste, fraud, abuse, or mismanagement” or those raising concerns related to efficiency or effectiveness.
Prop. 41’s additional audits would increase state costs, reducing the resources available to directly support services for Californians. Moreover, in the case of program audits related to a proposed special tax, the audit costs would be absorbed by the state’s General Fund if the ballot initiative were not enacted, leaving less funding for critical state services like education, health care, and human services.
Impacts of State Spending Limit Provisions
The primary impact of preventing new revenues from being excluded from the spending limit would be the invalidation of the billionaire tax proposed by Prop. 40 — if both measures pass and Prop. 41 receives more votes.
In the future, voters may be able to exclude the revenues from a statewide tax initiative from the spending cap if the initiative amends the Constitution to do so. In fact, previous initiatives have explicitly excluded new tax revenues from the limit, such as tobacco taxes enacted under Prop. 10 (1998) and Prop. 56 (2016). However, legal challenges are possible and there is no certainty on how courts would rule.
State policymakers already lack the authority to exclude new tax revenues from the spending cap without voter approval because the cap is enshrined in the state Constitution.
There are some existing state revenue streams that could potentially be affected by Prop. 41, but there are many complications and uncertainties and any conflicts would ultimately be decided by the courts. For example, some health care financing sources that must be occasionally reauthorized — such as the Managed Care Organization (MCO) tax and the Hospital Quality Assurance fee, which both allow the state to draw down additional federal funding for Medi-Cal — could potentially be impacted by Prop. 41. This, in turn, would jeopardize billions of dollars in federal funding for Medi-Cal at a time when Californians are already experiencing the harms of the deep federal cuts to health care resulting from H.R. 1.
Who Supports and Opposes Prop. 41?
The top contributor to the Prop. 41 campaign is a group called “Building a Better California,” which is largely funded by Google cofounder Sergey Brin and other billionaires. This same group is also opposing Prop. 40 and supporting Prop. 42. Prop. 41 is also endorsed by the California Republican Party, the California Chamber of Commerce, and the California Taxpayers Association.
There is no official campaign against Prop. 41. However, prominent opponents include the Service Employees International Union – United Health Workers West (SEIU–UHW) — the main proponent of the Prop. 40 billionaire tax measure — as well as other labor groups including the California Federation of Teachers and the California Federation of Labor Unions. The California Democratic Party and the League of Women Voters also oppose Prop. 41.
Curious About Other Ballot Propositions?
Browse our collection of resources covering California’s statewide ballot measures to help you understand what’s at stake for California this November.
SACRAMENTO, CA — A new publication from the California Budget & Policy Center (Budget Center) examines Proposition 39, a measure on the November ballot that would establish new voter identification and citizenship verification requirements in California and impose additional responsibilities and costs on state and local election officials. The analysis finds that Prop. 39 would … Continued
key takeaway
Proposition 39 on the November ballot would impose unnecessary, harmful, and costly new identification (ID) requirements on millions of California voters. It would harm US citizens by making it harder for them to vote, exposing them to identity theft, and putting them at risk of being erroneously removed from voter rolls. Prop. 39 is part of broader national efforts to create new barriers to voting, which primarily impact people with low incomes, young people, and people of color, limiting Californians’ say in how public tax dollars are raised and spent.
Prop. 39 would amend California’s Constitution to add new voter ID requirements that would affect current and future voters. The measure would also impose new responsibilities on state and local officials related to election administration. Specifically, Prop. 39:
Requires Elections Officials to “Use Best Efforts” to Verify Every Registered Voter’s Citizenship Status
Current Law
Californians are required to be US citizens to vote.1California Elections Code, Section 2101(a). There are two exceptions: Oakland and San Francisco allow certain noncitizens to vote in local school board elections. To register to vote, a person must declare in writing, under penalty of perjury, that they meet all voter eligibility requirements, including that they are a US citizen.2California Elections Code, Section 2150(b). Under federal law, state motor vehicle agencies — like California’s Department of Motor Vehicles (DMV) — must provide residents with the opportunity to register to vote when they apply for or renew a driver’s license or state ID card and/or change their address. In California, this is known as Motor Voter. DMV customers who indicate that they are eligible to vote are registered to vote by the Secretary of State (SOS) unless they opt out. However, the DMV does not send to the SOS information regarding customers who indicate they are not eligible to vote. Falsely claiming to be a US citizen on a voter registration application and attempting to vote would expose a person to state felony charges as well as the possibility of deportation under federal law.3For example, see California Elections Code, Section 18560(a), 8 U.S.C. Section 1227(a)(6)(a), and 18 U.S.C. Section 611.
In addition, state law makes it a crime to:
Vote or attempt to vote more than once in an election,
Impersonate or attempt to impersonate a voter in an election, or
Apply for or cast a vote-by-mail ballot by fraudulently signing the name of a fake person, another qualified voter, or a person who is not qualified to vote.4California Elections Code, Section 18560(b)-(c) and Section 18578.
A person who is convicted of any of these crimes could be imprisoned for up to three years.
Prop. 39
Prop. 39 would require state and county election officials to “use best efforts” to verify, using “government data,” that registered voters are US citizens. The measure does not define “best efforts” or what constitutes “government data.” In addition, election officials would have to annually report the share of registered voters in each county whose citizenship status has been verified.
Requires Voters to Present Additional Identifying Information When They Cast Their Ballot
Current Law
All states, including California, already have voter ID requirements as required by federal law. For example, to register to vote, Californians must provide a California driver’s license or state ID number or the last four digits of their Social Security Number (SSN) if they lack a driver’s license or ID card. Californians who lack a driver’s license, a state ID card, or a SSN are assigned a unique identifier to validate their registration. Californians generally are not required to present an ID when voting.5Californians may need to show an acceptable form of ID when they vote by mail or in person if all of the following apply: 1) they’re voting for the first time in a federal election, 2) they registered by mail or online, and 3) they did not provide a California ID or SSN when registering. Acceptable forms of ID include, but aren’t limited to, a California driver’s license or state ID card, a US passport, a student or military ID, a utility bill, and a bank statement.
When voting by mail, California voters sign the outside of their ballot envelope, and elections officials verify the signature before counting the ballot.6California Elections Code, Section 3011(a)(7) and Section 3019. Voters must be given an opportunity to correct or “cure” their ballot if they failed to sign the envelope or if their signature does not match the signature on file.7California Elections Code, Sections 3019(c)-(e).
When voting in person, California voters state their name and address and sign a list of registered voters under penalty of perjury.8California Elections Code, Section 14216(a). While election officials do not verify the signatures of in-person voters before counting their ballots, counties have procedures in place to prevent voter fraud.9For example, in many counties, poll workers are able to look up voting records in real time to ensure that a voter has not already cast a ballot in the election. This applies to counties that participate in California’s Voter’s Choice Act as well as to counties that have adopted the Sign, Scan, and Go option. As noted above, it is a crime in California to fraudulently vote in an election, to vote more than once, or to impersonate another voter. Penalties range from up to one year in a county jail to up to three years in state prison.
Prop. 39
Prop. 39 would impose new requirements on Californians to cast a ballot in person or mail a ballot.
To vote in person:
Voters would have to present a “government-issued” ID when they arrive at their polling place. Prop. 39 does not specifically define what “government-issued” ID means, so the Legislature would need to clarify which types of ID a voter could present to prove their identity.10Prop. 39 says broadly that “government-issued” ID “means documentation that allows conclusive verification of the voter’s identity.”
To vote by mail:
All new and existing voters would have to select a “government-issued” ID that would be reflected in their “voter registration record.” This requirement effectively means that people who are currently registered to vote would have to re-register to provide their chosen ID to election officials.
When voting, voters would have to write on the outside of their ballot envelope the last four digits of a “unique identifying number” from the “government-issued” ID that they selected for the purpose of voting.11The government-issued ID that voters choose for this purpose would have to subsequently be made available to them “on request by phone or electronically.”
Election officials would verify that the four digits written on the envelope match the last four digits of the ID number in the voter’s registration record.
Requires the State to Create a New Voter ID Card
Current Law
California currently allows Californians to apply for three types of ID cards in addition to drivers’ licenses that are used to prove identity or age.12The ID cards are issued by the California Department of Motor Vehicles as alternatives to a driver’s license and cannot be used to operate a motor vehicle.
Prop. 39
Prop. 39 would require the state to provide a voter ID card to eligible voters who request one. Voters could use this optional ID as their “government-issued” ID for voting by mail or in person. This card would be provided to voters free of charge.
Requires Ongoing State Audits of How the State and Counties Are Complying with Prop. 39
Current Law
California’s independently elected Secretary of State oversees all elections in the state, including ensuring election laws are enforced, testing and approving voting equipment, compiling election returns, and certifying election results.
In addition, California’s independent, nonpartisan State Auditor conducts performance audits and investigations of various state and local government agencies and recommends solutions for improving services. However, the State Auditor currently does not have a formal, ongoing role in auditing California’s elections or evaluating election administration.
Prop. 39
Prop. 39 would require the State Auditor, in odd-numbered years, to audit state and county compliance with Prop. 39 and report any recommendations for improvement.
Requires the State Legislature to Pass Laws to Implement Prop. 39
Prop. 39 would require the Legislature to “promptly enact laws” to implement the measure. For example, legislators would have to define which kinds of “government-issued” ID would be acceptable for voting as well as clarify what it means to make a “best effort” to verify a voter’s citizenship status. Prop. 39 would also require the Legislature to establish rules for military and overseas voters that are consistent with federal law.
Allows Citizens to Sue the State or Any County for Not Complying with Prop. 39
Prop. 39 would allow private citizens to sue the state and/or any county for any alleged noncompliance with the initiative. The measure does not specify what kind of evidence would be required to file a lawsuit.
How Would Prop. 39 Affect Californians and the State?
Prop. 39 Would Waste Resources By Addressing a Nonexistent Problem
The voter ID requirements that Prop. 39 would establish provide a “solution” to a nonexistent problem. This measure is based on the false premise that voter fraud — casting a ballot when one is not eligible to vote — is undermining election integrity. However, research shows that voter fraud is exceedingly rare. For example:
Using a comprehensive database tracking election fraud that was created by the right-wing think tank Heritage Foundation, the Brookings Institute found across more than 200 federal elections held in recent decades, the share of fraudulent votes cast were infinitesimally small — ranging from roughly 3 to 15 votes out of 10 million in seven states with close election outcomes. The study concluded that “isolated instances of fraud do not constitute a widespread trend” and that “no election outcome in the US has ever been altered by ballot fraud.”
Summarizing findings across numerous academic studies and investigative reports, the Brennan Center for Justice concludes that cases of voter impersonation fraud are extremely rare and do not happen “on a scale even close to that necessary to ‘rig’ an election.” For instance, their seminal report, The Truth About Voter Fraud, concluded that “it is more likely that an individual will be struck by lightning than that [they] will impersonate another voter at the polls.”
Voter fraud among noncitizens is also extremely rare. The Brennan Center synthesized findings from comprehensive studies, state investigations, and nationwide surveys across more than two decades and concluded that “actual incidents of noncitizens voting is not a significant occurrence.” For instance:
One national survey of 44 election administrators representing 42 jurisdictions in 12 states, including officials in eight of the 10 jurisdictions with the largest populations of noncitizens nationally, found that in the 2016 election, officials referred only about 30 incidents of suspected noncitizen voting for further investigation or prosecution — amounting to 0.0001% of votes cast.
The Bipartisan Policy Institute concluded that “there is no evidence that noncitizen voting has ever been significant enough to impact an election’s outcome.” Allegations of noncitizens voting often come out of voter registration audits, but further investigation into these claims often shows that individuals were flagged as noncitizens erroneously.
The libertarian think tank Cato Institute found that “there is no good evidence that noncitizens voted illegally [in the 2020 election] in large enough numbers to actually shift the outcome of elections or even change the number of electoral votes.”
Additionally, while proponents of Prop. 39 argue that imposing additional ID requirements will strengthen voters’ trust in California’s election process, evidence for this claim is lacking. One study found that registered voters had roughly equal confidence that votes were counted accurately whether they were in states with strict voter ID laws or states with the minimum ID requirements mandated by federal law.
Subsequent studies by researchers at the University of California Riverside and Western Washington University looking at voter perceptions in 2014 and following the 2020 US presidential election found that strict voter ID laws and the quality of election administration more generally had little to no effect on voter confidence. This and other research suggests this may be because voters view election laws through a partisan lens and their confidence may be more heavily influenced by partisan rhetoric and whether their preferred candidate wins or loses an election.13See Lonna Rae Atkeson, Eli McKown-Dawson, and Robert M. Stein, “The Costs of Voting and Voter Confidence,” Political Research Quarterly 78, no. 1 (2025); Shaun Bowler and Todd Donovan, “A Partisan Model of Electoral Reform: Voter Identification Laws and Confidence in State Elections,” State Politics & Policy Quarterly 16, no. 3 (January 11, 2016); and Shaun Bowler and Todd Donovan, “Confidence in US Elections After the Big Lie,” Political Research Quarterly 77, no. 1 (October 23, 2023).
Prop. 39 would impose additional voter ID requirements when robust voter safeguards are already in place, needlessly lengthening the process of voting without adding any extra security. For example, California currently requires individuals to verify their identity when registering to vote and when voting in-person and by mail:
To register, individuals must show a California Driver’s License or state ID or the last four digits of their Social Security number (SSN) and certify under penalty of perjury that their voter registration information is correct and that they are a US citizen. Additionally, these forms of ID are securely verified by officials using Department of Motor Vehicle or Social Security Administration records. If individuals do not have these forms of ID, they can verify their identity with election officials using other forms of identification, such as bank statements, paychecks, or government checks.
To vote in-person or by mail, individuals may need to show proof of identity if it’s their first time voting in a federal election and they did not provide a California ID or SSN when registering. Otherwise, election officials verify the identity of individuals who vote in person by checking individuals’ names and addresses against a list of registered voters and requiring voters to sign a roster. For those who vote by mail, voters are required to sign their ballot envelope, used for signature verification, and declare under penalty of perjury that they are who they claim to be and reside within the precinct in which they are voting. Federal and state law also impose requirements designed to promote the maintenance of accurate lists of eligible voters.
In addition to these voter identification safeguards, voter fraud is a felony under state law that could result in imprisonment if convicted. Falsely claiming to be a US citizen on a voter registration application and attempting to vote could also result in deportation under federal law. These costs far outweigh the minimal benefit of adding an additional vote, as one-vote margin elections are rare and the probability that one vote will change an election outcome, particularly when the electorate is large, is extremely low.
Prop. 39 Would Create Barriers to Voting for Millions of Eligible Voters
The voter ID requirement in Prop. 39 would create roadblocks to voting for millions of voting-age Californians. For example:
Millions of Voting-Age Californians Lack an Up-to-Date Driver’s License
A driver’s license is one of the most common forms of ID. However, a survey conducted by VoteRiders and the Center for Democracy and Civic Engagement (CDCE) found that among voting-age Californians who are US citizens:
About 2.7 million (10.8%) do not have a driver’s license.
More than 3 million (12.6%) have a driver’s license that is expired, is from another state, and/or lacks updated information such as a current address or name.
People of color, young people, people with less education, people with lower incomes, and people with disabilities are less likely to have a driver’s license.
About One-Quarter of Voting-Age Californians Without a Driver’s License Also Lack an Official California State ID Card
Nearly one-fourth (24%) of Californians without a driver’s license also lack a state ID card, according to VoteRiders and CCDE. This same group of voting-age citizens is very likely to lack other forms of ID as well:
Only 29% of voting-age Californians without a driver’s license or a state ID have a current passport that is readily accessible, and
Only 13% of these Californians have a current public school ID (high school or college) as a form of identification.
Navigating ID Requirements Can Be Confusing and Costly
Voter ID laws assume voters have the resources and knowledge to understand that they lack qualifying ID. However, VoteRiders and CDCE report that among voting-age citizens in California:
6 out of 10 express confusion about the state’s current in-person voter ID requirements.
Many are also concerned about the cost and wait time to obtain an ID.
Voter ID Requirements Disproportionately Impact Communities of Color
A study published in The Journal of Politics that analyzed voter registrants in Texas who voted without ID in 2016 found that:
Registrants voting without ID were disproportionately Black and Latinx compared to voters casting ballots with ID.
Registrants without ID were less likely to vote when a strict ID mandate was in place, and more likely to be Black and Latinx, than those voting with ID.
Voter ID Requirements Would Disproportionately Impact Young Californians
Young Californians (ages 18-34) make up 30% of the state’s adult population, but only 21% of likely voters, according to the Public Policy Institute of California. Additionally, compared to older adults, young Californians were more likely to be people of color, less likely to own a home, and more likely to have an annual income below $60,000.
Prop 39’s voter ID barriers would disproportionately affect young Californians. This is because:
Young people are far more likely to movethan older adults, meaning that any ID they do possess is likely to be out of date unless they consistently re-register to vote.
Young Californians aremore likely to cast provisional ballots, which are required when voters are not on the official registration list at a polling location.
Prop. 39 would make navigating the voting process more challenging for a significant portion of California’s voters, and would especially impact Californians who already face barriers to voting. In a state where voter turnout has recently been lower than the national average, adding new, costly, and unnecessary administrative hurdles could lead to many more Californians opting out of voting altogether.
Prop. 39 Would Increase the Risk of Identity Theft
If Prop. 39 passes, Californians who vote by mail would have to write on the outside of their ballot envelope the last four digits of an identifying number from a government-issued ID. These four digits would have to match the ID on file with the county election office in order for their ballot to be counted.
Writing sensitive numbers on a ballot envelope could increase the risk of identity theft. Envelopes already include the voter’s name, address, and signature. Adding a partial number from a voter’s Social Security card or driver’s license, for example, would expose that number to fraudsters. These bad actors would have an additional — and consequential — data point to work with in creating a fraudulent profile to use in phishing and other scams.
The risk of identity theft would continue long after a ballot is mailed or dropped off. State and federal law require election materials, including ballot envelopes, to be stored for six to 22 months.14See California Elections Code, Section 17301 and Section 17302. This lengthy storage period increases the potential for sensitive numbers to be accessed and misused.
More broadly, Prop. 39’s requirement to write sensitive numbers on the outside of the ballot envelope is out of step with expert security guidelines. The federal government, for example, urges organizations to minimize the collection and retention of personally identifiable information “to what is strictly necessary to accomplish their business purpose and mission.”15US Department of Commerce, National Institute of Standards and Technology, Guide to Protecting the Confidentiality of Personally Identifiable Information (PII) (April 2010), ES-2. These same guidelines note that “[p]artial identifiers, such as the first few digits or the last few digits of SSNs, are also often considered [personally identifiable information] because they are still nearly unique identifiers and are linked or linkable to a specific individual.”16Protecting the Confidentiality, 2-2, endnote 21.
If Prop. 39 is approved, the legitimate fear of identity theft could deter many Californians from voting by mail. This could suppress voter turnout since voting by mail is the easiest and most common way for Californians to cast a ballot, and some Californians may not be willing or able to travel to a polling place to vote in person.
Prop. 39 Would Add Burdensome Citizenship Verification Requirements
If Prop. 39 passes, election officials would be required to “use best efforts” — currently undefined — to verify the citizenship status of registered voters, using “government data” — also lacking specifics — for this purpose. (The Legislature would have to define these terms in state law.) In addition, election officials would have to annually report the percentage of registered voters in each county whose citizenship status was verified. These requirements are burdensome, unnecessary, and harmful.
First, as noted above, voting by noncitizens is extremely rare. Numerous safeguards currently exist to ensure that noncitizens do not register to vote, and any non-citizen who tried to vote would face stiff penalties, including fines, imprisonment, and deportation. Prop. 39 would add needless, burdensome, and costly requirements to California’s rigorous voter verification process.
Curious About Other Ballot Propositions?
Browse our collection of resources covering California’s statewide ballot measures to help you understand what’s at stake for California this November.
Second, requiring citizenship verifications is nearly guaranteed to result in some citizens being incorrectly flagged as noncitizens and potentially removed from the voter rolls. Federal databases that election officials would likely use to verify voters’ citizenship are riddled with errors, inconsistencies, and outdated information. For example, an individual’s name may appear differently across various databases, possibly due to a name change following marriage or a simple spelling error. Furthermore, naturalized US citizens’ current citizenship status may not be accurately reflected in all government records.
Even under the best circumstances, federal agencies make “mistakes when identifying people’s citizenship or immigration status.” Moreover, a key government database that President Trump has tried to compel states to use to verify voters’ citizenship status has produced “persistent” errors. As one election official in Missouri put it: “It really does not help my confidence … that the information we are trying to use to make really important decisions, like the determination of voter eligibility, is so inaccurate.”
Incorrectly identifying California voters as noncitizens would:
Deeply harm the specific individuals involved. Voters whose citizenship is mistakenly cast in doubt would need to navigate burdensome processes at multiple levels of government to fix a problem that was not of their making. In addition, US citizens who are mistakenly identified as noncitizens could lose their ability to vote if they miss or don’t receive a notice from their county election office and run out of time to correct the error before an upcoming election.
Undermine public confidence in elections. Given the flaws in federal databases and the “errors inherent in any large-scale data-matching,” election officials would likely end up finding data discrepancies — discrepancies that would wrongfully call into question the citizenship status of some registered voters. Under this scenario, Prop. 39 would require counties to report that they could not verify some voters’ citizenship, even if this outcome was entirely due to defective federal data rather than fact. This, in turn, would needlessly undermine public confidence in California’s elections.
Fuel baseless conspiracy theories and frivolous lawsuits. Election deniers and other critics could use flawed citizenship findings to prop up baseless claims about “widespread” voter fraud. They could also use Prop. 39’s private right of action to file lawsuits aimed at forcing election officials to act on flawed data, potentially blocking citizens from exercising their right to vote. Prohibiting certain US citizens from voting could change the result of a close election — precisely the kind of illegitimate outcome that Prop. 39’s proponents claim they are trying to prevent.
Proposition 39 Would Create Substantial Costs at the State and Local Levels Without New Revenue to Pay for Them
Prop. 39 would impose substantial costs on state and local governments, but includes no new revenue to pay for these expenses. While the magnitude of the fiscal impact is uncertain, Prop. 39 is expected to increase annual state and local costs by tens of millions of dollars to low hundreds of millions of dollars, according to estimates from California’s nonpartisan Legislative Analyst’s Office (LAO).
State and local leaders would face the prospect of shifting funding from existing public services to make room in their budgets for the costs imposed by Prop. 39. These costs would hit just as state and local budgets are absorbing the impact of massive federal funding cuts to health care and food assistance imposed by H.R. 1, which President Trump signed into law in 2025. For example, counties have to implement more stringent federal work requirements for the Medi-Cal and CalFresh programs that will require hiring more staff and implementing complex rules. Overall, H.R. 1 is estimated to raise counties’ annual costs by $6 billion to $9.5 billion.
The LAO suggests that Prop. 39 could produce some “savings” if fewer Californians were registered to vote due to the measure’s changes. In other words, savings would result from reduced voter participation as Prop. 39’s barriers to voting were implemented. Even so, any budget savings “likely would not exceed the costs of the measure,” according to the LAO.
Ultimately, the fiscal impact of Prop. 39 would depend on choices made by the state, counties, and voters. For example:
The cost of the new state-issued voter ID would depend on the complexity of the card’s design, which would be determined by state leaders, as well as on how many voters request a card.
Staffing for the State Auditor’s office would need to expand substantially due to the new requirement for ongoing, bi-annual audits of all 58 counties and the state.
Staffing for the Secretary of State’s office would need to grow to provide additional oversight and support for county election offices and implement various requirements of Prop. 39, such as verifying that registered voters are US citizens. However, the magnitude of any staffing growth would depend on how the state chooses to implement Prop. 39.
Staffing for county election offices would need to grow due to the mandate to verify registered voters’ citizenship status. However, the magnitude of any staffing growth would depend on the requirements of the state’s implementing legislation.
Informational technology systems at the state and local levels could need to be created or upgraded to verify registered voters’ citizenship status. The cost of these changes could be substantial, but would depend on the requirements of the state’s implementing legislation.
Regardless of the magnitude of Prop. 39’s costs, the result would be the same: elected officials would face difficult choices about how to accommodate these new expenses in their budgets without any new revenue to pay for them. Redirecting existing revenue to Prop. 39 would leave less funding for other vital public services, including services for Californians with low incomes and communities of color — the same voters who would most likely be impacted by Prop. 39’s new, and unnecessary, voting requirements.
Prop. 39 Is Part of a Nationwide Effort to Restrict Voting and Limit People’s Say in Policymaking
Prop. 39 Is Aligned with Broader Efforts to Restrict Voting
Prop. 39 is part of a national wave of proposals — including strict voter ID laws — that would make it more difficult for Americans to exercise their constitutional right to vote, even as voter fraud, including voting by noncitizens, is virtually nonexistent and inconsequential. These efforts have accelerated as unsubstantiated voter fraud rhetoric has increased, particularly following President Trump’s lies about a “stolen” 2020 presidential election that he has continued to perpetuate throughout his second term.
This fall, voters in six states, including California, will consider measures to impose stricter voter ID laws. Already this year, eight states have approved more stringent requirements and one other state enshrined voter ID requirements in the state’s constitution.
Last year marked the first year since 2011 that states enacted more laws to restrict voting rights than to expand them. At least 17 states in 2025 enacted 32 laws that restrict voting rights — tying with 2021 for the largest number of restrictive voting rights laws passed since the Brennan Center for Justice began tracking such legislation in 2011. This included more than a dozen states that imposed harsher voter ID rules between 2021 and 2025, including six states that did so last year alone — efforts typically led by Republicans.
Additionally, House Republicans, with strong support from President Trump, have been working to advance federal legislation, the SAVE Act, which would require people to show documents demonstrating US citizenship, like a passport or birth certificate, to register to vote, even though voting by noncitizens is extremely rare and inconsequential for election outcomes.
Investigative reporting by professor Ese Olumhense has also found a surge in legislation across states to increase the involvement of law enforcement in the voting process following the 2020 election. These state-led efforts, alongside federal court rulings that have continued to dismantle the Voting Rights Act in recent years, disproportionately threaten the voting rights of communities of color and represent “the latest chapter in the long history of US voter suppression.”
Restricting Voting Rights Limits People’s Say in How Public Resources Are Raised and Spent
Voting is the cornerstone of democracy. It allows citizens to have a say in public policies that affect their lives and communities, giving them a voice in one of core functions of government — determining how public resources are raised and spent. In her book, The Price of Democracy, Dr. Vanessa Williamson documents how democracy and taxation developed together throughout US history. This is because citizens who have a voice in policymaking are more willing to pay taxes, as they have a stake in how those taxes are used. Likewise, governments that depend on taxation have an incentive to listen to their voting — and taxpaying — citizens.
Dr. Williamson’s work shows that throughout US history, “the battles over the breadth of our democracy are, with startling regularity, fights about taxes.”17Vanessa S. Williamson, The Price of Democracy: The Revolutionary Power of Taxation in American History (New York, NY: Basic Books), 6. She explains that “the possibility that people of moderate means would have a say over the tax system has persistently led wealthy people to undermine governments’ democratic practices and fiscal capacity,” especially “when they could play on racial animus” to divide the working class.18Price of Democracy, 248 and 8.
This history is important for understanding current efforts across the nation to erect barriers to voting. Although policies like strict voter ID requirements may appear equitable because they apply to all voters universally, they disproportionately threaten to make it harder for young people, people with low incomes, and people of color to vote.
The surge of such policies comes at a time when massive, unprecedented federal budget cuts are taking health care and food assistance away from people with low and moderate incomes to help pay for trillions of dollars in tax breaks for corporations and the wealthy. Many other pending federal actions, if successful, could also undercut families’ access to affordable housing, early care and education, and other essential public services.
To counter federal cuts to vital services, impacted communities are increasingly looking to state and local leaders to make taxes more fair and raise revenue for public investments. Yet the very people who would benefit the most from such investments are those inhibited the most by new hurdles to voting.
California Should Continue to Promote Voter Participation and Improve the Election Process
By focusing on a non-existent problem, Prop. 39 fails to address real election issues that California voters are concerned about. Recent polling by UC Berkeley’s Institute of Governmental Studies found that 8 in 10 California likely voters considered “defending democracy and protecting voting rights” very important when deciding who to support for governor in the June primary. Similarly, more than 7 in 10 California registered voters found it important for candidates running for president in 2028 and state leaders to prioritize efforts to “defend democracy and make voting more accessible.”
Prop. 39 fails to address these significant concerns. Instead, it would make voting less accessible for eligible voters, undercutting democracy. Rather than advancing harmful and unnecessary ID requirements, California should promote more robust voter participation while also continuing to improve the state’s election process.
Promoting Voter Participation
California has made strides to encourage voter participation, offering many avenues to make registration and voting more accessible. These include:
Despite these strong pro-voter policies, California still sees gaps in voter turnout, likely voters, and registration rates among people with lower incomes, communities of color, and young people. California’s leaders can continue to strengthen the state’s voter policies by:
Exploring options for moving towardsautomatic voter registration, such as by revamping the Motor Voter program to register all eligible individuals. Currently, people can opt-out of voter registration at the DMV.19In 2024, the Legislature passed Senate Bill 299 to further streamline voter registration by building on the current system, but it was vetoed by Governor Newsom.
California has many options for improving voter accessibility, but Prop. 39 is not one of them. California’s current laws make registering and voting easy, enabling more eligible citizens to participate in elections, whereas Prop. 39 would make voting more difficult, increase the likelihood that people legally able to vote are erroneously blocked from doing so, decrease participation in California elections, and limit Californians’ say in how public tax dollars are raised and spent.
Improving the Election Process
State leaders can adopt commonsense reforms to promote more timely election results while maintaining California’s solid track record of election security, accurate counts, and robust voter access.
California takes longer than many states to count ballots and certify elections largely due to pro-voting policies and strict ballot-verification requirements designed to ensure accuracy and integrity. However, lengthy ballot-counting allows bad-faith critics to promote baseless conspiracy theories and undermine confidence in elections.
State leaders should consider several changes to speed up ballot counting and improve transparency of the vote count without undercutting election integrity and voter access. For example, state leaders could:20For details about these and other recommendations, see California Voter Foundation, Ten Recommendations to Accelerate California’s Vote Count (July 27, 2026).
Provide additional funding to county election offices for equipment, staff, and facilities,
Help voters across the state to more quickly “cure” (correct) issues with the signature on their vote-by-mail (VBM) ballot envelope by developing a statewide electronic curing system,21Typical issues addressed through the “curing” process include missing signatures or a signature that does not compare to the signature associated with the voter’s registration record. As allowed by state law, some counties have implemented a “text-to-cure” system that allows voters to address signature issues by signing the screen of their phone or tablet and submitting it using a secure platform. Establishing a statewide electronic curing system — as proposed by AB 2604 (Berman) — would streamline the signature-curing process and help to cure more signatures faster, thereby speeding up ballot counting.
Encourage more counties to offer “Sign, Scan, and Go” voting, which allows Californians to cast their VBM ballot in person without the ballot envelope for faster processing,22This voting option, also known as “Sign and Go” voting, was offered by 31 of California’s 58 counties in the June 2026 primary election. This option speeds up ballot processing because voters cast their ballot directly into a ballot scanner or ballot box without the ballot envelope, eliminating the need for the ballot to be counted later. Voters using this option must provide their name and address and sign the roster for the voting location, and election officials verify in real time that the voter has not already cast a vote-by-mail ballot without the envelope. Some election officials remain concerned about how to securely and effectively implement this voting method. SB 1420 (Richardson) — passed by the Legislature on August 27, 2026 — aims to address these concerns by requiring the Secretary of State to develop uniform procedures for Sign, Scan and Go voting, which could encourage more counties to adopt this option.
Educate voters about the importance of returning mail ballots earlier or voting in person in order to reduce the number of last-minute ballots requiring time-intensive signature verification, and
Improve how the Secretary of State reports unofficial election results.
These and other reforms could help to accelerate ballot-counting and promote transparency while maintaining pro-voter policies that encourage a diverse range of Californians to make their voices heard in the electoral process.
Prop. 39 Supporters and Opponents
Prop. 39’s leading proponent is Republican State Assemblymember Carl DeMaio. Prominent supporters include the California Republican Party, Reform California, and Uline CEO Richard Uihlein.
Prominent opponents include California gubernatorial candidate Xavier Becerra, US Senator Alex Padilla, the American Civil Liberties Union (ACLU), Common Cause, the League of Women Voters, and the California Democratic Party.
California Elections Code, Section 2101(a). There are two exceptions: Oakland and San Francisco allow certain noncitizens to vote in local school board elections.
2
California Elections Code, Section 2150(b). Under federal law, state motor vehicle agencies — like California’s Department of Motor Vehicles (DMV) — must provide residents with the opportunity to register to vote when they apply for or renew a driver’s license or state ID card and/or change their address. In California, this is known as Motor Voter. DMV customers who indicate that they are eligible to vote are registered to vote by the Secretary of State (SOS) unless they opt out. However, the DMV does not send to the SOS information regarding customers who indicate they are not eligible to vote.
Californians may need to show an acceptable form of ID when they vote by mail or in person if all of the following apply: 1) they’re voting for the first time in a federal election, 2) they registered by mail or online, and 3) they did not provide a California ID or SSN when registering. Acceptable forms of ID include, but aren’t limited to, a California driver’s license or state ID card, a US passport, a student or military ID, a utility bill, and a bank statement.
For example, in many counties, poll workers are able to look up voting records in real time to ensure that a voter has not already cast a ballot in the election. This applies to counties that participate in California’s Voter’s Choice Act as well as to counties that have adopted the Sign, Scan, and Go option.
10
Prop. 39 says broadly that “government-issued” ID “means documentation that allows conclusive verification of the voter’s identity.”
11
The government-issued ID that voters choose for this purpose would have to subsequently be made available to them “on request by phone or electronically.”
12
The ID cards are issued by the California Department of Motor Vehicles as alternatives to a driver’s license and cannot be used to operate a motor vehicle.
13
See Lonna Rae Atkeson, Eli McKown-Dawson, and Robert M. Stein, “The Costs of Voting and Voter Confidence,” Political Research Quarterly 78, no. 1 (2025); Shaun Bowler and Todd Donovan, “A Partisan Model of Electoral Reform: Voter Identification Laws and Confidence in State Elections,” State Politics & Policy Quarterly 16, no. 3 (January 11, 2016); and Shaun Bowler and Todd Donovan, “Confidence in US Elections After the Big Lie,” Political Research Quarterly 77, no. 1 (October 23, 2023).
Vanessa S. Williamson, The Price of Democracy: The Revolutionary Power of Taxation in American History (New York, NY: Basic Books), 6.
18
Price of Democracy, 248 and 8.
19
In 2024, the Legislature passed Senate Bill 299 to further streamline voter registration by building on the current system, but it was vetoed by Governor Newsom.
Typical issues addressed through the “curing” process include missing signatures or a signature that does not compare to the signature associated with the voter’s registration record. As allowed by state law, some counties have implemented a “text-to-cure” system that allows voters to address signature issues by signing the screen of their phone or tablet and submitting it using a secure platform. Establishing a statewide electronic curing system — as proposed by AB 2604 (Berman) — would streamline the signature-curing process and help to cure more signatures faster, thereby speeding up ballot counting.
22
This voting option, also known as “Sign and Go” voting, was offered by 31 of California’s 58 counties in the June 2026 primary election. This option speeds up ballot processing because voters cast their ballot directly into a ballot scanner or ballot box without the ballot envelope, eliminating the need for the ballot to be counted later. Voters using this option must provide their name and address and sign the roster for the voting location, and election officials verify in real time that the voter has not already cast a vote-by-mail ballot without the envelope. Some election officials remain concerned about how to securely and effectively implement this voting method. SB 1420 (Richardson) — passed by the Legislature on August 27, 2026 — aims to address these concerns by requiring the Secretary of State to develop uniform procedures for Sign, Scan and Go voting, which could encourage more counties to adopt this option.
You may also be interested in the following resources:
Proposition 2 on the November 2026 ballot would change the rules for California’s rainy day fund to build a larger reserve and better protect core public services during budget emergencies, such as an economic downturn. Prop. 2 also would expand the types of state debt that could be repaid with General Fund revenues that must be set aside each year. In addition, Prop. 2 would modify the relationship between certain reserves and California’s state spending cap, or “Gann Limit” — a change that would allow policymakers to build up reserves in years when revenues are strong and the state is at risk of exceeding the limit. The Legislature placed Prop. 2, a constitutional amendment, on the ballot by passing ACA 20.
Prop. 2 would amend the state Constitution to change several of the rules that govern California’s rainy day fund — the state’s primary budget reserve, known as the Budget Stabilization Account (BSA).1California voters created the BSA in 2004 by passing Prop. 58 and reformed the BSA a decade later by approving Prop. 2 of 2014. For an analysis of Prop. 2 of 2014, see California Budget & Policy Center, Proposition 2: Should California Prioritize Paying Down Debt and Significantly Change State Budget Reserve Policies? (September 2014). In addition, Prop. 2 would modestly change the interaction between state reserves and the state spending cap, commonly called the Gann Limit. This section highlights the key changes that Prop. 2 would make if approved by voters in November.
Increases the Maximum Size of the Rainy Day Fund (BSA) to 20% of General Fund Revenues
Current Law
The state Constitution limits the size of the BSA to 10% of estimated General Fund tax revenues.2Specifically, the amount transferred to the BSA in any fiscal year may not result in a balance that exceeds 10% of estimated General Fund “proceeds of taxes.” Proceeds of taxes are estimated for the purpose of calculating the State Appropriations Limit (or Gann Limit) and tend to differ slightly from total General Fund revenues and transfers. When this limit is reached, any dollars that otherwise would go into the BSA must be spent on infrastructure.
Proposition 2
Prop. 2 would double the BSA cap to 20% of estimated General Fund tax revenues. If the 20% cap were ever reached, the dollars that would otherwise be deposited into the BSA would instead be spent on infrastructure, as under current law.
Changes How “Excess” Capital Gains Revenues Are Calculated to Save More in Strong Revenue Years
Current Law
The state Constitution requires some General Fund revenues to be set aside annually and requires additional General Fund revenues to be set aside when certain conditions are met. Generally speaking, 50% of these set-aside revenues are deposited into the rainy day fund, and the other 50% are used to pay down certain state debts.3As noted below, some set-aside revenues are owed to TK-14 education through the Prop. 98 minimum funding guarantee. This portion of set-aside revenues is governed by different rules and does not go toward the rainy day fund or state debt payments. These set-aside revenues are determined in two ways:
1.5% of General Fund revenues are automatically set aside every year. For example, if General Fund tax revenues were estimated to total $250 billion for a fiscal year, the state would need to set aside a total of $3.75 billion (1.5%), with half deposited into the rainy day fund (BSA) and the other half used to pay down certain state debts. Prop. 2 would not change this required annual transfer.
In addition to this fixed annual transfer, the state is required to set aside “excess” capital gains revenues. This requirement is triggered in years when estimated General Fund tax revenues that come from personal income taxes on capital gains exceed a specified target: 8% of total General Fund tax revenues.4Capital gains are the profits realized from selling assets that have increased in value, such as stock shares or real estate. Revenues from capital gains can be volatile from year to year depending on market conditions. When this occurs, a portion of these “excess” capital gains revenues — specifically, the share that is not owed to TK-14 education through the Proposition 98 minimum funding guarantee — is split equally between building the BSA balance and paying down certain state debts.5The share of “excess” capital gains revenues that are owed to TK-14 education via Prop. 98 is subject to a different set of rules. See California Budget & Policy Center, Proposition 2: Should California Prioritize Paying Down Debt and Significantly Change State Budget Reserve Policies? (September 2014), p. 2.
Proposition 2
Prop. 2 would change how “excess” capital gains revenues are calculated in order to set aside more revenue for the rainy day fund and state debt payments. Under Prop. 2, there would be two categories of “excess” capital gains revenues, as follows:
The first category of “excess” revenues would include capital gains revenues that total between 8% and 10% of General Fund tax revenues.
The second category of “excess” revenues would equal 1.5 times the portion of capital gains revenues that are above 10% of General Fund tax revenues. For example, if there are $2 billion in capital gains revenues above the 10% threshold, the state would have to set aside a total of $3 billion ($2.0 billion * 1.5) — $1 billion more than is required under current law.
As under current law, the portion of these “excess” revenues that are not owed to TK-14 education through Prop. 98 would be split equally between the rainy day fund and certain state debt payments.
Expands the Types of State Debt That May Be Paid with Set-Aside Revenues
Current Law
The state Constitution requires that half of General Fund revenues set aside each year be used to repay certain state debts.6The revenues used to calculate this 50% requirement exclude set-aside revenues that are owed to TK-14 education through California’s Prop. 98 minimum funding guarantee. Currently, the state may only use these set-aside revenues to 1) prefund state retiree health benefits and/or 2) pay down unfunded liabilities associated with state‑level pension plans. In prior years, the state was allowed to use these set-aside revenues to pay down certain types of budgetary debt. This included payments owed to K-12 schools and community colleges as of July 1, 2014.7These payments went toward unfunded prior-year Prop. 98 obligations, including so-called “settle-up” obligations, which reflect the reconciliation of estimates of the annual Prop. 98 minimum funding level and the actual Prop. 98 guarantee. However, by 2019-20, the state had repaid all of the outstanding budgetary debt.
Proposition 2
Prop. 2 would update and expand the list of state debts that could be paid with set-aside revenues. Specifically, these funds could be used to:
Repay federal unemployment insurance (UI) loans. Under Prop. 2, revenues set aside for state debt could be used to repay “federal loans made to the Unemployment Fund.” The measure does not specify whether Prop. 2 funds could be used to pay the interest as well as the principal on federal UI loans.
Repay certain TK-14 education obligations. Under Prop. 2, the state could once again use set-aside revenues, during any fiscal year, to make certain payments owed to TK-12 schools and community colleges.8Specifically, Prop. 2 would allow revenues set aside for state debt payments to be used for “unfunded prior fiscal year General Fund obligations” pursuant to the Prop. 98 minimum funding guarantee. These include so-called “settle-up” obligations, which reflect the reconciliation of estimates of the annual Prop. 98 minimum funding level and the actual Prop. 98 guarantee. Under the original Prop. 2 (2014), the state was allowed to use set-aside revenues to pay down unfunded prior fiscal year General Fund obligations pursuant to Prop. 98, but only for debt accrued prior to July 1, 2014. That debt was repaid by the 2019-20 fiscal year. In addition, set-aside revenues could be used to help accelerate the phase-out of an outstanding debt tied to an accounting maneuver that state leaders adopted in the 2023-24 budget to address an issue related to the Prop. 98 minimum funding guarantee.9For a discussion of this accounting maneuver, see Legislative Analyst’s Office, The 2024-25 Budget: The Governor’s Proposition 98 Funding Maneuver (February 15, 2024).
Repay General Fund loans to the Medi-Cal program. The 2025-26 budget transferred $4.4 billion from the state General Fund to the Medical Providers Interim Payment Fund to help cover higher-than-expected Medi-Cal costs. The budget delayed repayment of this loan, with payments starting in 2027-28 and potentially continuing for several years. Under Prop. 2, revenues set aside for state debt could be used to accelerate the paydown of the 2025-26 Medi-Cal loan or other Medi-Cal loans.
Extends the Debt-Paydown Requirement by 10 Years, to 2039-40
Current Law
The state Constitution requires 50% of set-aside revenues to be used to pay down certain state debts through the 2029-30 state fiscal year.10The revenues used to calculate this 50% requirement exclude set-aside revenues that are owed to TK-14 education through California’s Prop. 98 minimum funding guarantee. Starting in 2030-31, these payments become optional, and any set-aside revenues that are not used to pay down debt must be deposited into the rainy day fund.
Proposition 2
Prop. 2 would require 50% of set-aside revenues to go toward paying down state debts for an additional 10 years ending in 2039-40.11The revenues that would be used to calculate this 50% requirement would continue to exclude set-aside revenues that are owed to TK-14 education through California’s Prop. 98 minimum funding guarantee. Starting in 2040-41, these payments would become optional, and any set-aside revenues that were not used to pay down debt would have to be deposited into the rainy day fund.
Changes the Relationship Between Deposits/Withdrawals and the Gann Limit
Current Law
The state Constitution requires that deposits into state reserves be counted as spending for the purpose of calculations required by California’s spending cap. This is the case even though tax dollars transferred to a reserve clearly will not immediately be spent through the budget. This rule was put in place by Prop. 4 of 1979, which created the state spending cap.12For simplicity, this discussion uses the word “spending.” However, Prop. 4 uses the technical phrase “appropriations subject to limitation.” See California Constitution, Article XIIIB, Section 5. This cap is formally known as the State Appropriations Limit, but is more commonly called the Gann Limit.13The spending cap applies to the state as well as to local governments.
In contrast, withdrawals from state reserves as well as expenditures of withdrawn funds do not count as spending for the purpose of the Gann Limit.14California Constitution, Article XIIIB, Section 5. In other words, under current constitutional rules, tax dollars count toward the spending cap when they go into a reserve, but do not count toward the cap when they come out.
As a result, in years when state revenues are growing rapidly and the state is at risk of exceeding the spending cap, state leaders cannot bolster California’s fiscal resilience by further building up reserves, because doing so would put the state over the spending limit.15Revenues that are projected to exceed the spending limit can only be used in a few narrow ways if state leaders want to avoid going over the cap. If the state exceeds the cap for two consecutive years, half must go to taxpayers and the other half must go to TK-14 education on a per-pupil basis.
Proposition 2
Prop. 2 would alter the relationship between deposits/withdrawals and the Gann Limit for two state reserves: the rainy day fund (BSA) and the Projected Surplus Temporary Holding Account.
Prop. 2 would change the interaction between the BSA and the Gann Limit. Under Prop. 2, revenues would not count toward the state spending cap when they go into the rainy day fund, but would count when they are withdrawn.
Prop. 2 would change the interaction between the Projected Surplus Temporary Holding Account and the Gann Limit. The holding account is used to temporarily set aside anticipated surplus revenues for up to one year. Under Prop. 2, revenues deposited into the holding account — up to a cap — would not count toward the Gann Limit, but they would count when they come out. This cap would be equal to 10% of total General Fund tax revenues in the year the transfer is made. For example, if General Fund tax revenues were estimated to total $250 billion, then up to $25 billion could go into the holding account without counting toward the Gann Limit (but would count toward the Gann Limit when withdrawn). However, if the holding account deposit exceeded $25 billion, then the excess amount would count toward the Gann Limit (but would not count when withdrawn).
Changes How a Budget Emergency May Be Declared
Current Law
The state Constitution requires the governor to declare a budget emergency in order to:
Suspend or reduce a required deposit into the rainy day fund (BSA) or the Public Schools System Stabilization Account (PSSSA), or
To declare a budget emergency, the governor signs a proclamation. It may be signed very late in the fiscal year, including after the June 15 constitutional deadline for the Legislature to pass the budget. For example, in 2025, Governor Newsom issued a budget emergency proclamation on June 27 — well after the Legislature passed the budget and just three days before the end of the 2024-25 fiscal year.
This misaligned timing puts the Legislature in the awkward position of passing a budget that assumes a budget emergency before the governor has made it official.
Proposition 2
Prop. 2 would create a simplified pathway for declaring a budget emergency. This alternative pathway is intended to prevent a situation where the governor suggests a budget emergency will be declared, but then fails to issue a proclamation before the Legislature’s June 15 constitutional deadline to pass the budget.
Prop. 2 would allow the governor’s May Revision, which is due out by May 14, to constitute the proclamation of a budget emergency if two conditions were met:
Second, the May Revision would have to propose suspending or reducing a required transfer to the BSA or PSSSA and/or withdrawing funds from one or both of these reserves.
In other words, if voters approve Prop. 2, the governor would no longer have to issue a formal proclamation in order for a budget emergency to be operative.
What Would Proposition 2 Not Do?
While Prop. 2 would make a few changes to California’s rainy day fund as well as modestly revise how the Gann Limit works, the measure would largely leave the current rules in place. In addition, Prop. 2 would not touch the state’s constitutional funding requirement for TK-14 schools and community colleges, known as Prop. 98. For example, Prop. 2:
Maintains the requirement to set aside 1.5% of state General Fund tax revenues each year. Half of these revenues would continue to go into the rainy day fund (BSA), and the other half would continue to be used to pay down certain state debts.
Continues to allow state leaders to reduce or suspend deposits into the rainy day fund to address a budget emergency, and maintains the current definition of “emergency.” BSA deposits could continue to be reduced or suspended in the event of a budget emergency, which would continue to be defined as 1) a disaster or extreme peril or 2) insufficient General Fund revenues to meet a prior-year spending level.
Continues to limit the amount of money that may be withdrawn from the rainy day fund to address a budget emergency. State leaders could continue to withdraw only the amount needed to address a budget emergency, and no more than half of the funds could be taken out in the first year of an emergency.
Continues to prohibit state leaders from suspending debt payments to address a budget emergency. State leaders would continue to be prevented from reducing or canceling required debt payments, even if the state faced a disaster or a severe budget shortfall.
Does not make any changes to the Prop. 98 minimum funding guarantee for TK-14 education. Under the state Constitution, the state is required to set aside a portion of revenues for schools and community colleges each year based on various inputs and formulas. Prop. 2 does not make any changes to the formulas or inputs that determine the annual minimum guarantee calculation.
Maintains the current rules for California’s TK-14 education reserve. Prop. 2 does not change the rules governing the PSSSA, the state’s reserve for TK-12 schools and community colleges. For example, all of the conditions required to trigger a deposit into the PSSSA would remain intact. This includes strong capital gains-related income tax revenue, General Fund revenue growth that translates to strong growth in the Prop. 98 minimum funding guarantee, and no legislative suspension of the guarantee.
Leaves California’s arbitrary spending cap largely untouched. Other than modestly changing the relationship between two state reserves and the Gann Limit, Prop. 2 leaves in place the complex rules that structure California’s spending cap. This cap hinders state leaders’ ability to respond to the needs of Californians even as these needs have changed dramatically since the Gann Limit was created in 1979.
What Would Proposition 2 Mean for California?
This section explores the implications of several key provisions of Prop. 2, specifically:
Raising the rainy day fund cap to from 10% to 20% of General Fund tax revenues,
Setting aside more General Fund revenues during “boom” years,
Expanding the types of state debt that may be paid down with set-aside revenues, including unemployment insurance loans and certain TK-14 education obligations, and
Changing the relationship between two state reserves and the state spending cap (the Gann Limit).
This section also considers the implications of maintaining two current rainy day fund provisions that Prop. 2 would leave in place, specifically:
Continuing to prohibit state leaders from reducing or suspending required debt payments during a budget emergency, and
Maintaining the current definition of what qualifies as a budget emergency.
What Are the Implications of Raising the Rainy Day Fund (BSA) Cap to 20% of General Fund Tax Revenues?
Under Prop. 2, the maximum size of the rainy day fund would double, rising from 10% to 20% of General Fund tax revenues. With a higher cap, the rainy day fund would have the potential to grow substantially larger. This, in turn, would provide a larger “cushion” for the state budget, helping state leaders to better protect vital services when revenues drop during economic downturns and reducing the need for draconian spending cuts that harm Californians.
If the BSA balance were ever to reach the higher 20% cap, the annual General Fund revenues that would otherwise be deposited into the fund (“spillover” revenue) would instead be spent on infrastructure, as under current law. However, with a higher cap, the state would reach the BSA limit less frequently than is currently the case with a 10% cap. Consequently, over time there would be less spillover revenue available for infrastructure investments. On the other hand, the rainy day fund would likely hold a larger balance to help address a budget emergency.
Curious About Other Ballot Propositions?
Browse our collection of resources covering California’s statewide ballot measures to help you understand what’s at stake for California this November.
What Are the Implications of Setting Aside More Revenue in “Boom” Years?
Prop. 2 would require the state to set aside more revenue in years when capital gains revenues spike. This change would allow the state to build up the rainy day fund and pay down certain debts faster, reducing future General Fund cost pressures, while modestly curtailing General Fund revenue available for immediate spending needs.
If Prop 2’s “excess” capital gains provisions had been in place between 2010-11 and 2023-24, California would have had to set aside more General Fund revenue in six of those 14 years. This additional set-aside would have amounted to less than 1% or 2% of total General Fund revenue in each of those six years. Capital gains revenue is difficult to project. However, if a similar pattern held going forward, Prop. 2 could take hundreds of millions of dollars — or even more than $1 billion — in revenue “off the table” in some years. This would reduce resources available to address urgent needs that arise, but would also help to pay down additional state debt and further build reserves to address future emergencies.
Although “excess” capital gains revenue, by definition, is not a predictable and reliable revenue source and cannot be counted on to fund ongoing services, it could be reasonable to use it to temporarily meet critical needs. For example, the state could provide more funding for food banks in the wake of federal food assistance cuts, boost support for local governments to address homelessness, and pay child care providers before or at the time of service delivery (rather than after) — a change that would increase providers’ financial solvency.
In certain years, Prop. 2 would modestly reduce revenue that could otherwise be used to support vital services as communities across the state are reeling from deep federal cuts and mounting affordability pressures that are compounding long-standing unmet needs.
However, meaningfully addressing Californians’ needs requires significant and sustained new revenue — well beyond the relatively modest revenue that Prop. 2 would occasionally divert to reserves and debt payments. This underscores the need to reform California’s outdated tax base whether or not voters approve Prop. 2.
What Are the Implications of Expanding the Types of Debt That May Be Paid Down with Set-Aside Revenues?
The state Constitution requires a portion of General Fund revenues to be set aside each year for certain debt payments (unfunded pension and state retiree health liabilities). This requirement cannot be reduced or suspended even in a budget emergency — a provision that Prop. 2 would leave in place. In recent years, for example, roughly $1 billion to $2 billion in General Fund revenues each year remained “off the table” and were not available to support urgent spending needs.
Prop. 2 would broaden the allowable uses of set-aside revenues to include unemployment insurance (UI) debt. If policymakers were to use these debt-paydown funds to repay the principal on the state’s federal UI loans, then a cost currently borne by businesses would be shifted to the state.
Prop. 2 would also allow set-aside revenues to be used to pay down certain obligations related to TK-14 education and Medi-Cal that otherwise would be paid out of the General Fund. If policymakers were to use debt-paydown funds for these purposes, then General Fund revenue would be freed up for other purposes.
However, set-aside revenues are limited. If state leaders were to use more of these debt-paydown funds for the new purposes allowed by Prop. 2, then fewer (or no) funds would be available to reduce unfunded pension and state retiree health liabilities — costs that would eventually be borne by the General Fund.
What Are the Implications of Using Set-Aside Revenues to Repay Unemployment Insurance Loans?
Prop. 2 would allow state leaders to use set-aside revenues for “federal loans made to the Unemployment Fund.” California owes the federal government roughly $20 billion it borrowed to cover the cost of workers’ unemployment insurance (UI) benefits beginning during the COVID-19 pandemic, when unemployment spiked. Using debt-paydown funds to reduce the principal on California’s UI debt would shift a cost currently borne by businesses to the state and do nothing to fix California’s broken UI system.
Shifting a Cost Currently Borne by Businesses to the State
California’s state government is not required to repay the principal on federal UI loans. Instead, federal law requires businesses to repay the principal through automatic increases in their federal payroll taxes. This makes sense: California’s UI debt is the result of a broken system. For decades, state leaders have not required businesses to contribute enough to cover the true cost of the unemployment benefits their workers need.
Using set-aside revenues to repay the principal on California’s UI loans would shift a cost currently covered by businesses to the state. Moreover, this approach would reduce the amount of debt-paydown funds available for other purposes, such as reducing unfunded pension liabilities — costs that would eventually be borne by the General Fund. As a result, to the extent that state leaders were to use set-aside revenues to pay down UI debt, then more General Fund revenue would be needed to reduce other state debts, diverting dollars away from providing services to Californians.
Doing Nothing to Fix California’s Broken UI System
The UI system is chronically underfunded because California has failed to modernize the system’s financing to ensure that it generates sufficient revenue to cover the cost of the unemployment benefits workers need.
Consequently, federal loans are expected to become “a permanent feature” of the program, with significant implications for the state’s budget. California typically uses General Fund dollars to pay the interest on these loans, which could total around $1 billion annually in the coming years. Using state dollars to pay the interest on UI loans reduces resources that could otherwise be used to address Californians’ affordability challenges or other needs.
Using debt-paydown funds to reduce the principal on California’s UI debt could modestly reduce the state’s annual interest payments in the near term. However, until state leaders address the broken UI financing system, California is expected to remain locked in a perpetual cycle of debt, necessitating ongoing federal loans and putting constant pressure on the state’s General Fund to cover the annual interest owed.
What Are the Implications of Using Set-Aside Revenues to Repay Certain School and Community College (TK-14) Education Obligations?
Prop. 2 would give state leaders a new option to use set-aside revenues to repay certain TK-14 education obligations. Specifically, the measure would allow state leaders to use these funds to 1) cover Prop. 98 “settle up” payments, as needed, and 2) more quickly phase out an outstanding debt tied to an accounting maneuver that state leaders adopted in the 2023-24 budget to address an issue related to the Prop. 98 minimum funding guarantee. These new options mean that:
State Leaders Could Use Debt-Paydown Funds to Help Address Increases in Prop. 98 Funding Estimates
When state leaders enact a budget, they provide an estimate of the Prop. 98 minimum funding guarantee for that fiscal year. This initial estimate is updated in subsequent years to reflect changes in revenue estimates and other inputs. The updated inputs sometimes increase the Prop. 98 guarantee, which requires the state to provide additional funding through “settle-up” payments.
The state usually recognizes any increases to the Prop. 98 guarantee in subsequent years and provides the required settle-up payments from the state’s General Fund at that point. In some years, however, settle-up payments have been delayed, most recently for fiscal years 2024-25 and 2025-26, partly due to the state’s limited General Fund capacity to fund that growth.
Prop. 2 would allow set-aside revenues to be used to cover any current or future Prop. 98 settle-up obligations. This change would provide state leaders with an additional funding source for making these payments, which they could use at their discretion, potentially in combination with General Fund dollars. However, using debt-paydown funds for this purpose would compete with other allowable uses, such as prefunding state retiree health benefits.
In addition, using debt-paydown funds to make settle-up payments would not necessarily retire this obligation more quickly. Under current law, there is no required schedule for making settle-up payments, and Prop. 2 does not create one. If set-aside revenues were treated as the sole or primary source for settle-up payments, it could take longer to fully pay down these obligations because the amount of set-aside revenues may not align with the size of the obligation in a given year, especially when state revenues decline and the set-aside shrinks.
State Leaders Could Accelerate the State’s Recognition of $6.2 Billion in TK-14 Costs Incurred in 2022-23
In 2023, tax filing deadlines were extended due to winter storms, and state leaders overestimated the amount of tax revenue that would be received later in the year. As a result, the state provided $6.2 billion more to schools and community colleges than the Prop. 98 minimum funding guarantee actually required.
State leaders did not reduce the minimum guarantee to account for the lower revenues. Instead, they set up a schedule to recognize those dollars for accounting purposes in future budgets, starting in 2027-28 and ending in 2039-40. The annual cost is $500 million for the first 12 years, with a smaller amount in the 13th year.
Recognizing these costs will directly reduce General Fund revenues that would otherwise be available in those years for state funding priorities outside of the Prop. 98 guarantee. The sooner this $6.2 billion debt is recognized, the sooner the annual General Fund cost ends and those dollars become available for other purposes.
Prop. 2 would allow state leaders to use set-aside revenues to recognize this $6.2 billion debt, which would mitigate the General Fund impact as well as potentially clear the outstanding balance more quickly. However, using debt-paydown funds for this purpose would compete with other allowable uses, such as reducing state retiree pension liabilities.
What Are the Implications of Changing the Relationship Between Reserves and the State Spending Cap (Gann Limit)?
Prop. 2 would allow state policymakers to save more in strong revenue years to better protect vital public services during economic downturns. This is because deposits into two key reserves would no longer count as spending for the purpose of calculations required by California’s spending cap (the Gann Limit). Instead, these deposits would count toward the Gann Limit only when they are withdrawn.
This change would allow state leaders to build up reserves in years when revenues are strong and the state is close to reaching the spending cap, removing a key drawback of the Gann Limit. This change would also modestly increase “room” under the cap by up to a few billion dollars a year, potentially delaying how long it takes for the state to surpass the limit.
These changes are important. The Gann Limit is an arbitrary cap that hinders state leaders’ ability to respond to the needs of Californians, which have changed dramatically since late 1970s when the cap was established. Meeting the essential needs of residents and building up reserves to address future needs should not be hamstrung by an arbitrary spending cap approved by an earlier generation of voters.
Prop. 2 would allow policymakers to keep the state under the Gann Limit by making deposits into two reserves — the BSA and the Projected Surplus Temporary Holding Account (“holding account”). Several factors, including which of these accounts were used for this purpose, would determine when the deposited funds could be withdrawn and how they could be spent. Specifically:
For deposits into the holding account, state law currently requires the funds to be withdrawn within a year — a rule that could be changed by the Legislature.
If withdrawing funds from the holding account would cause the state to exceed the spending cap, then policymakers would lose flexibility over how the funds could be used (their use would be governed by the Gann Limit’s restrictive rules).
Otherwise, if withdrawing the funds would not cause the state to exceed the limit, policymakers would have full control over the funds.
For deposits into the BSA, the portion that was constitutionally required to be deposited could not be withdrawn unless a budget emergency was operative. Any discretionary deposits, on the other hand, could be withdrawn at any time.
If withdrawing funds from the BSA would cause the state to exceed the spending limit, then policymakers would lose flexibility over how the funds could be used (their use would be governed by the Gann Limit’s restrictive rules).
Otherwise, if withdrawing the funds would not cause the state to exceed the limit, policymakers would have full control over the funds.
Although Prop. 2 would take a modest step toward loosening the constraints of the Gann Limit, the limit itself would remain in place and continue to artificially restrict policymakers’ ability to meet state residents’ needs and create an equitable California.
What Are the Implications of Continuing to Prohibit State Leaders from Reducing or Suspending Debt Payments During a Budget Emergency?
Prop. 2 would leave in place the rules that prevent state leaders from reducing or canceling required annual debt payments.17In contrast, under current law, required deposits into the rainy day fund can be reduced or suspended during a budget emergency — a flexibility that Prop. 2 would maintain. In other words, paying down debt would continue to be prioritized over using those funds to address a disaster or to meet Californians’ basic needs during tough budget years when state revenues are down.
Moreover, under Prop. 2, this prohibition on reducing or suspending debt payments would remain in place for an additional 10 years, through 2039-40, after which these payments would be optional. Under current law, debt payments are required through 2029-30, after which they become optional.
The current rules unreasonably constrain state leaders’ options when there is a budget deficit. As recently as 2025, for example, the state faced a $15 billion budget problem. However, state leaders could not pause the required debt payments, taking a potential budget-balancing tool off the table. As a result, additional budget “solutions,” like freezing Medi-Cal enrollment for certain immigrants and reducing payments to health care clinics, were enacted to close the budget gap, even as the debt payments went forward.
By failing to allow state leaders to reduce or suspend required debt payments, Prop. 2 misses an opportunity to create another budget-balancing tool that could help to close deficits without resorting to harmful cuts.
What Are the Implications of Maintaining the Current Definition of “Budget Emergency”?
Under Prop. 2, state leaders could continue to reduce or suspend a required deposit into the rainy day fund and/or withdraw funds to help address a budget emergency. Prop. 2 also maintains the current definition of a “budget emergency,” which reflects either 1) a disaster or extreme peril or 2) insufficient resources to meet a specified prior-year General Fund spending level.
The current definition of “budget emergency” leaves out federal funds. As such, it fails to recognize the impact of federal funding cuts on California’s ability to support vital public services. For example, H.R. 1, the 2025 federal budget reconciliation bill — the so-called “One Big Beautiful Bill Act” signed into law by President Trump — slashed federal funding for basic needs to help offset the cost of tax breaks for the wealthy and profitable corporations.
Millions of Californians will lose health care and food assistance due to H.R. 1. Yet, these massive federal cuts to vital public services do not count as a “budget emergency.” As a result, state leaders cannot tap the rainy day fund to help mitigate — if only temporarily — the impact of these federal funding losses and reduce the harm that H.R. 1 is inflicting on Californians.
By failing to broaden the definition of a “budget emergency” to include federal funding losses, Prop. 2 misses an opportunity to help state leaders reduce the harm of substantial federal cuts to vital public services.
The California Budget & Policy Center is a nonpartisan research and analysis nonprofit and does not endorse or oppose ballot measures. This analysis reflects the institutional position of the Budget Center, developed and reviewed by our policy leadership team.
Specifically, the amount transferred to the BSA in any fiscal year may not result in a balance that exceeds 10% of estimated General Fund “proceeds of taxes.” Proceeds of taxes are estimated for the purpose of calculating the State Appropriations Limit (or Gann Limit) and tend to differ slightly from total General Fund revenues and transfers.
3
As noted below, some set-aside revenues are owed to TK-14 education through the Prop. 98 minimum funding guarantee. This portion of set-aside revenues is governed by different rules and does not go toward the rainy day fund or state debt payments.
4
Capital gains are the profits realized from selling assets that have increased in value, such as stock shares or real estate. Revenues from capital gains can be volatile from year to year depending on market conditions.
The revenues used to calculate this 50% requirement exclude set-aside revenues that are owed to TK-14 education through California’s Prop. 98 minimum funding guarantee.
7
These payments went toward unfunded prior-year Prop. 98 obligations, including so-called “settle-up” obligations, which reflect the reconciliation of estimates of the annual Prop. 98 minimum funding level and the actual Prop. 98 guarantee.
8
Specifically, Prop. 2 would allow revenues set aside for state debt payments to be used for “unfunded prior fiscal year General Fund obligations” pursuant to the Prop. 98 minimum funding guarantee. These include so-called “settle-up” obligations, which reflect the reconciliation of estimates of the annual Prop. 98 minimum funding level and the actual Prop. 98 guarantee. Under the original Prop. 2 (2014), the state was allowed to use set-aside revenues to pay down unfunded prior fiscal year General Fund obligations pursuant to Prop. 98, but only for debt accrued prior to July 1, 2014. That debt was repaid by the 2019-20 fiscal year.
The revenues used to calculate this 50% requirement exclude set-aside revenues that are owed to TK-14 education through California’s Prop. 98 minimum funding guarantee.
11
The revenues that would be used to calculate this 50% requirement would continue to exclude set-aside revenues that are owed to TK-14 education through California’s Prop. 98 minimum funding guarantee.
12
For simplicity, this discussion uses the word “spending.” However, Prop. 4 uses the technical phrase “appropriations subject to limitation.” See California Constitution, Article XIIIB, Section 5.
13
The spending cap applies to the state as well as to local governments.
14
California Constitution, Article XIIIB, Section 5.
15
Revenues that are projected to exceed the spending limit can only be used in a few narrow ways if state leaders want to avoid going over the cap. If the state exceeds the cap for two consecutive years, half must go to taxpayers and the other half must go to TK-14 education on a per-pupil basis.
In contrast, under current law, required deposits into the rainy day fund can be reduced or suspended during a budget emergency — a flexibility that Prop. 2 would maintain.
You may also be interested in the following resources:
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
key takeaway
Proposition 43 on the November ballot would require that at least two-thirds of local voters approve any local initiative that would create, extend, or increase a special tax, starting on January 1, 2027. As communities across California are facing substantial challenges and uncertainties, this measure would make it harder for local voters to raise revenues to support local public services and give outsized power to a small share of voters. Approval of the measure would decrease the likelihood that local governments meet the needs of their residents and could increase hardship in some communities throughout the state.
This measure would require at least two-thirds of local voters to approve any local initiative that would create, extend, or increase a special tax. The measure would apply to initiatives placed on a local ballot on or after January 1, 2027.
This new supermajority vote requirement would apply to special tax voter initiatives raising revenue for many types of local governments, including cities, counties, special districts, and other local or regional government entity.1Under California’s Constitution, all taxes levied by special districts are considered “special taxes,” so Prop. 43’s two-thirds vote requirement would apply to any taxes placed on the ballot by voters to generate revenues for special districts as well as city and county taxes for dedicated purposes.
A tax that is levied by a city or county and that may be spent on any program or service. All non-property taxes that cities and counties may levy can be imposed as general taxes. A general tax may be approved by a simple majority of local voters, regardless of whether it is placed on the ballot by the local government entity or by a local voter initiative.
Local voter initiative process
Gives residents of a city or a county the power to propose changes to local ordinances. This process involves a number of steps, including drafting a ballot measure, circulating petitions, and gathering the required signatures.
Parcel tax
A tax on a parcel of property that is not based on the property value. This tax is generally levied at a flat rate per parcel, but can also be levied on a per-square-foot or per-room basis. Parcel taxes can be levied by cities, counties, school districts, community college districts, and most special districts. Parcel taxes are always considered to be special taxes for the purpose of determining voter-approval requirements.
Simple majority vote
A requirement that a state or local ballot measure receive support from at least half of voters plus one additional voter (50%+1) in order to be approved.
Special tax
Includes1) parcel taxes, 2) city or county taxes (excluding property taxes) dedicated to specific purposes, and 3) taxes (excluding property taxes) levied by special purpose districts — that is, special districts, K-12 school districts, and community college districts.
Supermajority vote
A requirement that a state or local ballot measure receive more than a simple majority vote, such as three-fifths or two-thirds, in order to be approved.
What Are the Current Vote Requirements for Local Revenue Increases in California?
California’s Constitution has a complex set of rules governing how local governments can raise taxes and other types of revenue. These rules were put in place by statewide ballot measures over the past several decades, beginning with Prop. 13 in 1978 and followed by other measures creating additional restrictions on local revenue-raising capacity, including Prop. 62 (1986) and Prop. 218 (1996).
These rules apply to local measures to create new taxes as well as to increase or extend any existing tax.
Tax measures proposed by local governments — such as city councils or county boards of supervisors — must go on the ballot and be approved by voters. Current voter-approval thresholds differ depending on the type of tax that would be raised:
A general tax requires only a simple majority vote to pass, with the revenue available for any program or service.
A special tax requires a two-thirds vote to pass, and includes a tax dedicated to a specific purpose.
Special taxes proposed through the local voter initiative process are subject to different rules. In recent years, a series of court decisions have clarified that the two-thirds vote requirement for special taxes in the state Constitution does not apply to special tax measures placed on the ballot by local voter initiative. Therefore, both general taxes and special taxes proposed by voters can be approved with a simple majority vote.2Several cases involving special tax voter initiatives that were approved with a simple majority vote were appealed to the California Supreme Court, but the Supreme Court denied review of the appellate court decisions, allowing these decisions to stand. A variety of special tax initiatives have been approved over the past several years with a simple majority vote, such as:
San Francisco’s Measure C in November 2018, creating a tax on commercial landlords to raise funds for child care and early education, which passed with 51% of the vote.
Fresno’s Measure P in November 2018, increasing the local sales tax rate to fund community parks, which passed with 52% of the vote.
Los Angeles’ Measure ULA in November 2022, creating a property transfer tax on sales of high-value property to raise funds for affordable housing development and homelessness service, which passed with 58% of the vote.
Madera County’s Measure T in November 2024, renewing a local sales tax rate to fund transportation projects, which passed with 52% of the vote.
Certain types of local taxes are always classified as special taxes for the purposes of voter approval requirements. This includes:
Taxes levied by special-purpose districts, including school districts, community college districts, and special districts.
Parcel taxes, which are taxes on parcels of property that are not based on the property value. These taxes are generally levied at a flat rate per parcel, but can also be levied on a per-square foot or per-room basis.
What Services Do Local Governments in California Provide?
Californians in every community across the state benefit from services provided by local governments. Local services help keep people safe and healthy by providing fire protection, law enforcement, public health services, hospitals and emergency services, road safety, and more. Local governments also provide educational and recreational spaces like public libraries, public parks, and playgrounds.
Californians experiencing economic insecurity, food security, or who don’t have access to private health insurance can access financial assistance, food assistance, and health care because counties are there to administer public health and economic security programs. Cities can support the development of affordable housing to ensure more of their residents can afford a safe place to live.
Counties administer health and human services programs such asMedi-Cal health coverage, CalFresh food assistance, and CalWORKs cash assistance for families. Counties also provide public health, behavioral health, and child welfare services. Additionally, counties are responsible for overseeing the local justice system and courts, administering elections, and providing municipal services like sewer systems and trash pick-up in unincorporated areas.
Cities provide a variety of municipal services such as fire protection, housing and urban planning, parks and recreation, libraries, street repair, water and sewer systems, and law enforcement — although some of these services may be provided by special districts in some areas.
Special districts provide specialized services such as fire protection, water, electricity, parks and recreation, transit, hospitals, and other health care services.
Regional entities such as Joint Powers Authorities and Councils of Government coordinate policy and service provision across regions spanning multiple cities or counties, such as regional transportation authorities.
How Do Local Governments Raise Revenue?
Local governments in California rely on a variety of revenue sources, including transfers from the state and federal governments, allocations of local property taxes, and various other taxes, service charges, assessments, and fees.
Most types of local governments receive some revenues from the local property tax, capped at 1% by Prop. 13 (1978). Property taxes are collected by counties and the revenues are allocated to support city and county governments, school districts, community college districts, and special districts in accordance with formulas established in state law. Local governments and voters cannot increase property taxes beyond the 1% rate, except to finance infrastructure bonds.3Property tax increases to support school infrastructure bonds can generally be approved by 55% of local voters. All other property taxes for infrastructure bonds must be approved by two-thirds of voters.
Curious About Other Ballot Propositions?
Browse our collection of resources covering California’s statewide ballot measures to help you understand what’s at stake for California this November.
Other common types of taxes supporting local services include sales taxes (known as transactions and use taxes at the local level), taxes on hotel stays (known as transient occupancy taxes), property transfer taxes, utility user taxes, and business license taxes.
The revenues that make up local government budgets vary by the type of entity, and the legal authority to raise taxes also differs by government type. Cities and counties have fairly broad authority to raise a variety of taxes — with voter approval — while special districts have more limited authority. These districts are largely limited to parcel taxes — a tax on parcels of land not based on their value — as a source of discretionary revenue, although some can levy district sales taxes and certain other types of taxes.
More than half of county-level revenues statewide come from the state and federal governments and local property taxes. Other types of taxes make up a small share of total county revenues — generally less than 3%. Common types of taxes levied by counties include sales taxes, property transfer taxes, taxes on hotel stays, and utility user taxes.
City-level revenues primarily come from service charges for municipal functions — such as electricity, water, and sewer services — and various taxes. These two categories generally each make up around one-third of total city revenues statewide. Local property tax revenues and sales taxes are the largest sources of tax revenues for cities, each representing about one-quarter of tax revenues. Other major tax revenue sources for cities include taxes on hotel stays, utility user taxes, and business license taxes.
Special district revenues come largely from customer service charges for the service provided by the district, local property taxes, and certain other taxes and assessments, depending on the type of district.4The composition of special district revenues depends on the type of special district. Enterprise districts provide services to customers for a charge and operate similar to businesses, being largely financed by user charges. Examples of enterprise districts include health care districts, airport districts, water districts, and other utility districts. Non-enterprise districts provide benefits to entire communities — such as fire protection and road repair services — and are primarily funded by property taxes and other types of taxes and assessments. As noted above, taxes levied by special districts are always considered special taxes so they require approval of two-thirds of voters in the district, unless they are placed on the ballot by voters.
How Would Proposition 43 Affect California Communities?
Proposition 43 Would Make It More Difficult for Communities to Generate Revenues to Meet Local Needs
California already imposes high barriers to raising local revenues by requiring all special taxes levied by local governments to be approved by two-thirds of voters instead of a simple majority, and by classifying certain types of taxes — parcel taxes and taxes levied by special districts and school districts — as special taxes subject to higher vote requirements. Extending the two-thirds vote requirement to voter-initiated special tax proposals, as Prop. 43 proposes, would decrease the likelihood that these measures would pass, even if a significant majority of local voters support the measure and the services that the new revenues would fund.
In contrast to the high bar for raising taxes, local governments do not need voter approvalto reduce services— and cuts to services often result when localities face revenue shortfalls. Yet, communities also have the option of raising revenues to help close budget gaps. If Prop. 43 passes, counties and cities would still have the ability to raise general taxes with approval from a simple majority of voters to shore up local services. However, local voters’ ability to propose new special taxes to protect or strengthen key services would be limited as local voter initiatives would become much more challenging to pass. Additionally, voters in special districts would face a higher bar to increase revenues to preserve and expand services, regardless of whether the funds would be targeted to specific programs.
Proposition 43’s Constraints on Local Revenues Would Make Things Harder for Communities Already Struggling
Governments across the board have felt the impacts of inflation on the costs of providing public services, and the state’s aging population increasing the cost of providing some services such as health care. The impacts of the 2025 federal budget reconciliation law, H.R. 1 — also known as the “One Big Beautiful Bill Act” — along with the effects of climate change, the labor market and broader economic impacts of arrests and deportations of immigrants, and other federal policy changes such as tariffs, are also creating challenges for localities.
H.R. 1 will deeply harm Californians by cutting funding for essential health care and food assistance programs, primarily Medi-Cal and CalFresh, pushing more people into poverty and widening racial and economic inequities across the state. This is already increasing the level of need in communities as people lose health coverage and food assistance benefits while increasing costs for some local governments. The pressures on local governments will continue to increase substantially in the coming years as additional H.R. 1 policies go into effect.
Counties
Counties will be the most impacted by H.R. 1 and will see higher costs due to a combination of direct funding reductions and cost shifts, workload increases, and increases in uninsured individuals seeking basic care at county hospitals, which counties are legally required to provide. In addition to the direct impacts of H.R. 1, the increase in hardship created by the federal cuts will likely increase the demand for other county services such as housing and homelessness supports, and counties will have difficulty meeting this demand with less funding.
Local Health Districts
Local health care districts — a type of special district that can provide hospital care, ambulance services, health clinics, skilled nursing facilities, and other health-related services — will likely also be strained as individuals lose health coverage. Many of these districts are located in rural or underserved areas.
Public Hospitals
Many California public hospitals — including those operated by counties and local health care districts — have already been facing financial strain in recent years, particularly rural hospitals and others that serve high shares of patients with coverage through Medi-Cal and or Medicare. H.R. 1’s Medi-Cal cuts will compound these challenges. Nationwide, there are concerns about how rural hospitals and clinics will stay afloat as the cuts continue to go into effect. If health care providers cut services or close down, many individuals in those communities would be left without adequate health care.
Cities
While cities will be less directly impacted by H.R. 1, the federal law did rescind some funding related to transportation and climate-related programs. In addition, cities will likely be impacted by some downstream effects of the health care and food assistance cuts. For example, local economies may be impacted by the strains on household budgets, and the need for city services such as affordable housing and homelessness services may increase as more residents are faced with the choice between paying for food and medical care or paying rent.
These challenges would come on top of existing financial pressures such as increasingly frequent climate disasters (such as the devastating January 2025 Los Angeles wildfires) and the increasing cost of providing city services due to inflation and other factors, including rising health care costs driving up expenses for health benefits for city workers and retirees.
Proposition 43 Would Give Disproportionate Power to a Small Share of Voters
Supermajority vote requirements allow a small share of voters to block policies favored by a large majority of voters. For example, Prop. 43 would allow 35% of local voters to block an initiative that 65% of voters support. In other words, a minority of voters could prevent the community from raising revenues to support services that the vast majority of community members say are needed.
Proposition 43 Would Allow Statewide Voters to Restrict Local Control to Raise Revenue
Statewide ballot measures require just a simple majority vote to pass, even if the measure proposes to amend the state Constitution. Prop. 43 would allow a bare majority of statewide voters to impose a supermajority vote requirement on local voters, limiting the ability of local voters to raise revenues to fund public services — even though different communities in the state have different needs and preferences.
Proposition 43 Supporters and Opponents
Prop. 43 is supported by the Howard Jarvis Taxpayers Association and Reform California, a political action committee headed by State Assemblymember Carl DeMaio. It is opposed by Evolve California, a grassroots organization focused on public education funding and Prop. 13 reform, and State Assemblymember Buffy Wicks.
The California Budget & Policy Center is a nonpartisan research and analysis nonprofit and does not endorse or oppose ballot measures. This analysis reflects the institutional position of the Budget Center, developed and reviewed by our policy leadership team.
Kayla Kitson and Scott Graves contributed to this publication.
Under California’s Constitution, all taxes levied by special districts are considered “special taxes,” so Prop. 43’s two-thirds vote requirement would apply to any taxes placed on the ballot by voters to generate revenues for special districts as well as city and county taxes for dedicated purposes.
2
Several cases involving special tax voter initiatives that were approved with a simple majority vote were appealed to the California Supreme Court, but the Supreme Court denied review of the appellate court decisions, allowing these decisions to stand.
3
Property tax increases to support school infrastructure bonds can generally be approved by 55% of local voters. All other property taxes for infrastructure bonds must be approved by two-thirds of voters.
4
The composition of special district revenues depends on the type of special district. Enterprise districts provide services to customers for a charge and operate similar to businesses, being largely financed by user charges. Examples of enterprise districts include health care districts, airport districts, water districts, and other utility districts. Non-enterprise districts provide benefits to entire communities — such as fire protection and road repair services — and are primarily funded by property taxes and other types of taxes and assessments.
You may also be interested in the following resources:
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
This website uses cookies to analyze site traffic and to allow users to complete forms on the site. The California Budget & Policy Center does not share, trade, sell, or otherwise disclose personal information. By using our website you agree to our Privacy Policy.