Skip to content

Why We Focus on the State Budget

Every year, California’s governor and Legislature adopt a state budget that provides a framework and funding for vital public services and systems — from child care and health care to housing and the safety net to colleges and TK-12 schools (transitional kindergarten through 12th grade).

But the state budget is about more than dollars and cents.

The budget expresses our values as well as our priorities for Californians and as a state. At its best, the budget should reflect our collective efforts to expand economic opportunities, promote well-being, and improve the lives of Californians who are denied the chance to share in our state’s wealth and who deserve the dignity and support to lead thriving lives.

State budget choices have an impact on all Californians. These decisions affect the quality of our schools and health care, the cost of a college education, families’ access to affordable child care and housing, the availability of services and financial support to help older adults age in place, and so much more.

Because the state budget touches so many services and our everyday lives, it is critical for Californians to understand and participate in the annual budget process to ensure that state leaders are making the strategic choices needed to allow every Californian — from different races, backgrounds, and places — to thrive and share in our state’s economic and social life.

This report sheds light on the state budget and the budget process with the goal of giving Californians the tools they need to effectively engage decision makers and advocate for fair and just policy choices.

Key Takeaways

The Bottom Line

  1. The state spending plan is about more than dollars and cents.
    • Crafting the budget provides an opportunity for Californians to express our values and priorities as a state.
  2. The state Constitution establishes the rules of the budget process.
    • Among other things, these rules allow lawmakers to approve spending with a simple majority vote, but require a two-thirds vote to increase taxes. Voters periodically revise the budget process by approving constitutional amendments.
  3. The governor has the lead role in the budget process.
    • Proposing a state budget for the upcoming fiscal year gives the governor the first word in each year’s budget deliberations.
    • The May Revision gives the governor another opportunity to set the budget and policy agenda for the state.
    • Veto power generally gives the governor the last word.
  4. The Legislature reviews and revises the governor’s proposals.
    • Lawmakers can alter the governor’s proposals and advance their own initiatives as they craft their version of the budget prior to negotiating an agreement with the governor.
  5. Budget decisions are made throughout the year.
    • The public has various opportunities for input during the budget process.
    • This includes writing letters highlighting their budget priorities, providing public comment at legislative hearings, and meeting with officials from the governor’s administration as well as with legislators and members of their staff.
    • In short, Californians have ample opportunity to stay engaged and involved in the budget process year-round.

Key Facts About California’s State Budget

The State Budget = State Funds + Federal Funds

Three Kinds of State Funds

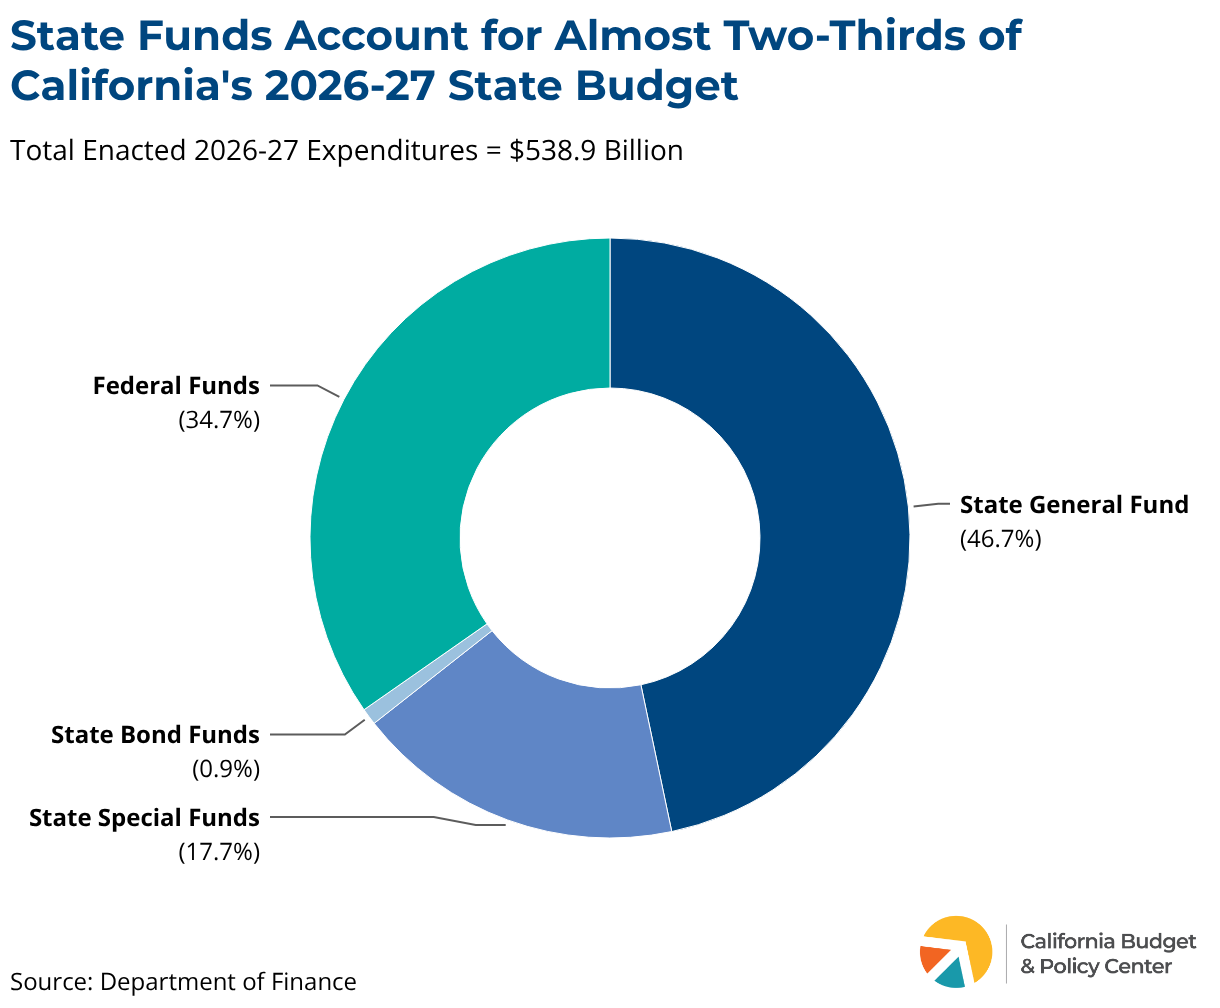
Three kinds of state funds account for almost two-thirds ($351.7 billion, or 65.3%) of California’s $538.9 billion budget for 2026-27, the fiscal year that began on July 1, 2026. Specifically:

  1. General Fund — The state General Fund accounts for revenues that are not designated for a specific purpose. Most state support for education, health and human services, and state prisons comes from the General Fund.
  2. Special Funds — Over 500 state special funds account for taxes, fees, and licenses that are designated for a specific purpose.
  3. Bond Funds — State bond funds account for the receipt and disbursement of general obligation (GO) bond proceeds.

Federal funds comprise the rest ($187.2 billion, or 34.7%) of the state’s 2026-27 budget.
Most State General Fund and Special Fund Revenue Comes from Three Sources

California’s “big three” taxes

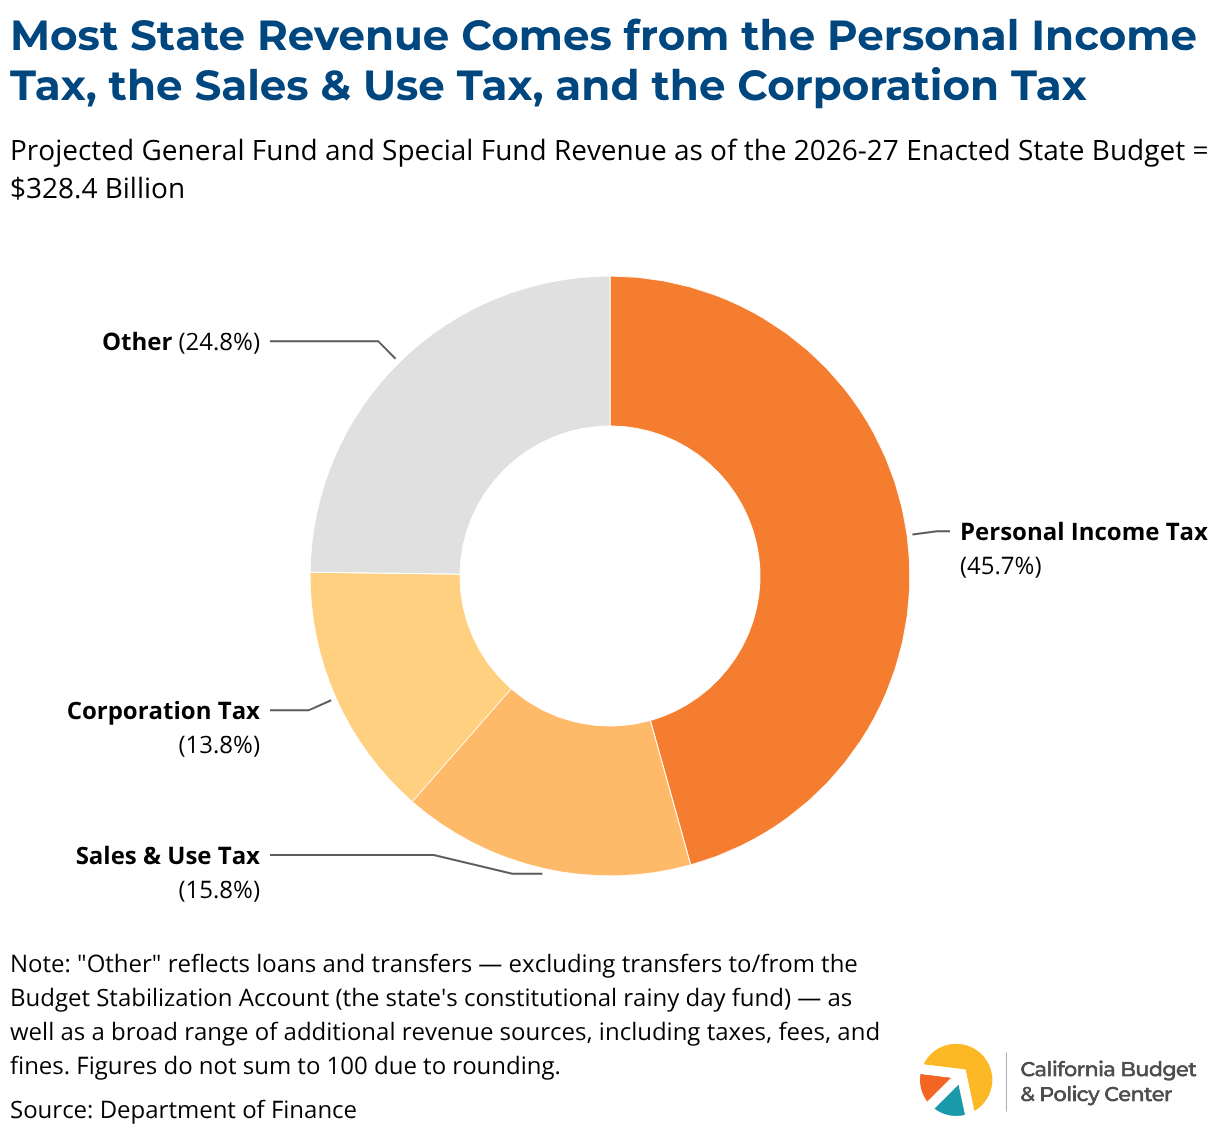
Most state revenue comes from California’s “Big Three” taxes. In 2026-27, General Fund and special fund revenue combined is estimated to total $328.4 billion, with more than three-quarters ($247.0 billion, or 75.3%) expected to come from the Big Three. California’s Big Three taxes are the:

  1. Personal income tax — This is a tax on the income of California residents as well as the income of nonresidents derived from California sources. It is California’s largest source of revenue.
  2. Sales & use tax — This is a tax on the purchase of tangible goods in California (the sales tax) or on the use of tangible goods in California that were purchased elsewhere (the use tax). Services are excluded from the sales and use tax, as are other items exempted by law, including groceries and medications. The sales and use tax is California’s second-largest source of revenue.
  3. Corporation tax — This is a tax imposed on corporations that do business in or derive income from California, with the exception of insurance companies, which instead pay the insurance tax. The corporation tax is California’s third-largest source of revenue.

Other state revenue is estimated to make up nearly one-quarter ($81.4 billion) of total projected General Fund and special fund revenue in 2026-27. This other revenue comes from a broad range of sources, including taxes, fees, and fines.
State Funds Primarily Support Health and Human Services or Education

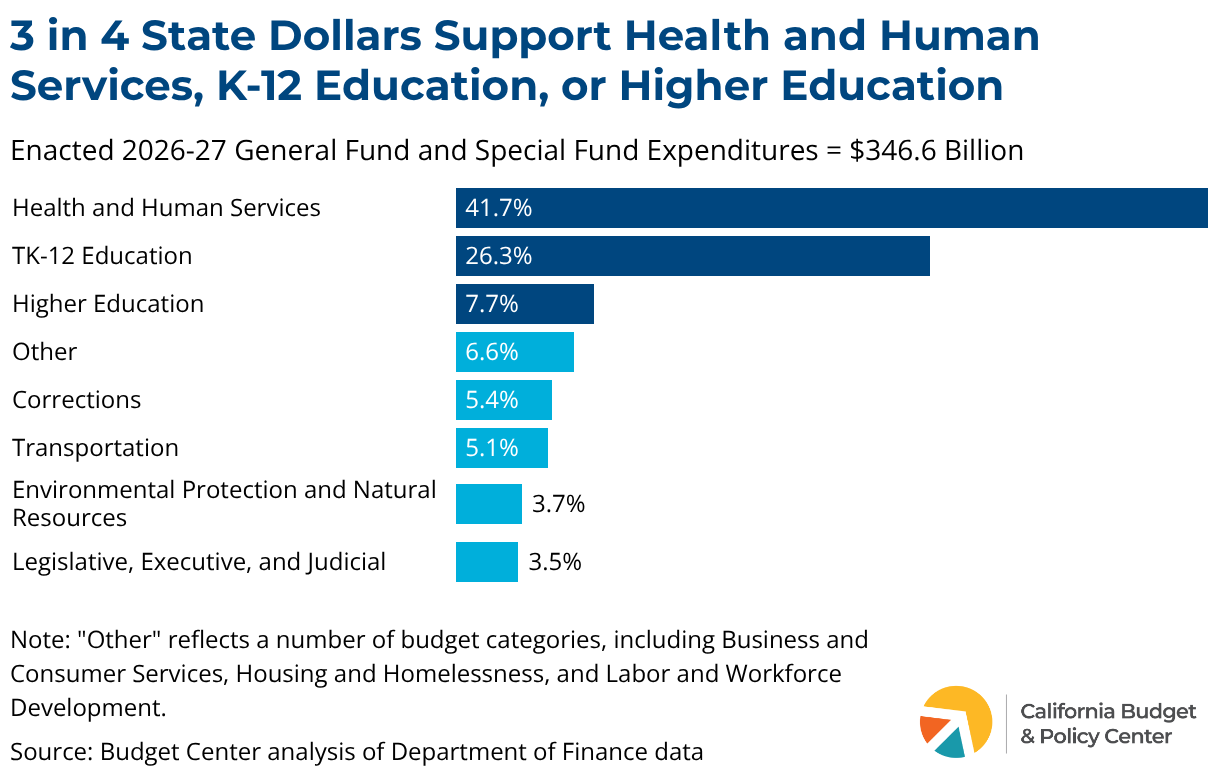
Under the enacted 2026-27 state budget:

  • 3 in 4 General Fund and special fund dollars support three categories of spending:
    • Health and human services (41.7%),
    • TK-12 education (26.3%), and
    • Higher education (7.7%).
  • More than 5% of General Fund and special fund dollars go to corrections, primarily the state prison system.
  • The balance of these dollars supports other essential services (such as transportation and environmental protection) and institutions (such as the state’s court system).
Federal Funds Primarily Support Health and Human Services

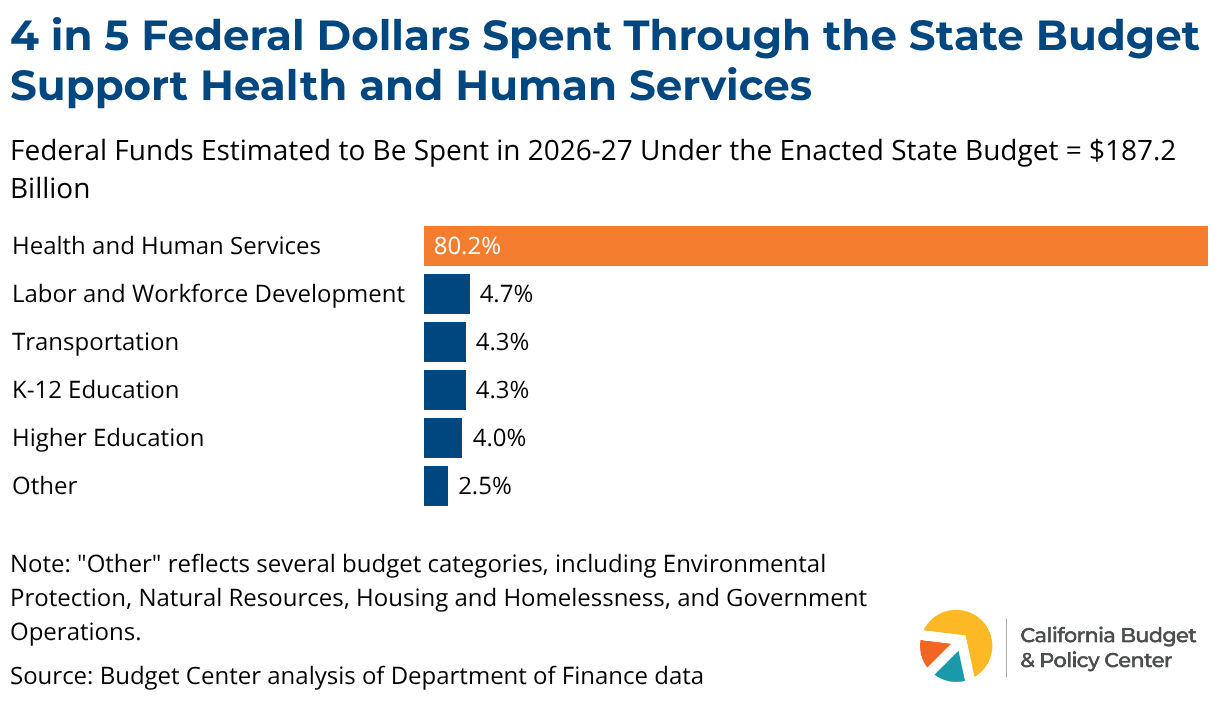
Under the enacted 2026-27 state budget:

  • Four-fifths of federal dollars (80.2%) support health and human services programs.
  • The balance of federal dollars supports other essential services, including labor and workforce development, K-12 education, higher education, and transportation.
The State Budget Is Part of a Package of Bills

The state budget never stands alone. Instead, it moves as part of a package of legislation that typically includes two to three dozen bills, and sometimes many more — particularly in years when there is a budget shortfall and state leaders need to make multiple changes to balance the budget. In 2026, Governor Newsom signed more than 40 budget-related bills.
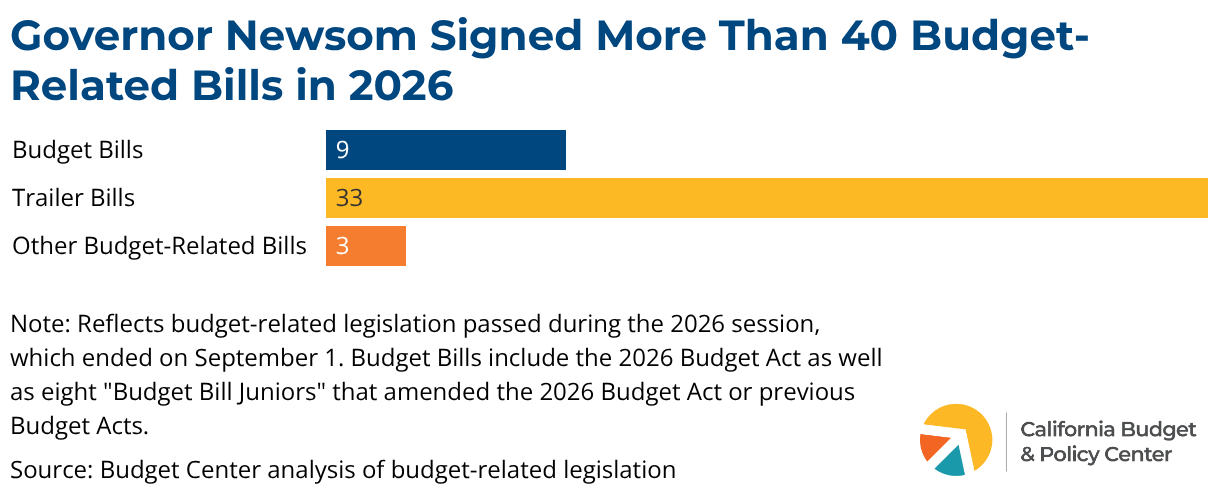
The budget package consists of two types of budget bills along with trailer bills and other budget-related legislation.

  1. Budget Act — The state budget is formally known as the Budget Act. The Budget Act is the initial budget bill passed by the Legislature and signed into law by the governor. In general, budget bills:
    • Provide authority to spend money (“appropriations”) across an array of public services and systems for a single year.
    • Move through the Legislature’s budget committees on their own timeline.
  2. Budget Bill Juniors — This is the informal term for any budget bill that amends the Budget Act, such as by increasing or reducing authorized expenditures. There is no limit on the number of Budget Bill Juniors that may be included in a budget package. This means state leaders can revise the Budget Act as many times as they wish by passing additional budget bills.
  3. Trailer bills — The state budget package also includes trailer bills. Trailer bills generally make changes to state law related to the Budget Act and, like budget bills, move through the Legislature’s budget committees. In addition, trailer bills:
    • Must contain at least one appropriation and be listed in the Budget Act — a requirement that directly links trailer bills to the state budget.
    • Are organized by major policy areas in the budget. For example, health-related changes would be included in a “health” trailer bill, housing-related changes would be included in a “housing” trailer bill, etc.
  4. Other budget-related bills — Other bills may be included in the budget package from time to time. These are bills that move independently of the Budget Act (and therefore are not trailer bills) but are still considered part of the state budget framework. This could include, for example, legislation to increase taxes or to place constitutional amendments before the voters as well as bills passed in a special session of the Legislature. This other budget-related legislation can move either through the Legislature’s policy committees or through budget committees.

State Budget Terms That Every Budget Advocate Should Know

Understanding budget lingo is crucial to effectively navigating California’s state budget process. This section highlights 10 key definitions drawn from the Budget Center’s glossary of state budget terms, which includes almost 100 budget-related words and phrases.


The Constitutional Framework

The State Constitution Establishes the Rules of the Budget Process

The governor and legislators craft the state’s annual spending plan according to rules outlined in the state Constitution.

California voters periodically revise these rules by approving constitutional amendments that appear on the statewide ballot.

  • Proposals to amend the state Constitution can be placed on the ballot through a citizens’ initiative or by the Legislature.
  • A constitutional amendment takes effect if approved by a simple majority of voters.

Three Key Budget Deadlines

Two in the State Constitution (January 10 and June 15), One in State Law (May 14)


The governor must propose a budget for the upcoming fiscal year on or before January 10. The budget must be balanced: Estimated revenues (as determined by the governor) must meet or exceed the governor’s proposed spending.


The governor must release the May Revision on or before May 14.


The Legislature must pass a budget bill for the upcoming fiscal year by midnight on June 15. The budget bill must be balanced: Estimated General Fund revenues (as set forth in the budget bill passed by the Legislature) must meet or exceed General Fund spending.

Prop. 25: Simple Majority Vote for Budget Bills and Trailer Bills

The budget package generally may be passed by a simple majority vote of each house of the Legislature.

  • Prop. 25 of 2010 allows lawmakers to pass, by a simple majority vote, budget bills as well as trailer bills that may take effect as soon as the governor signs them.
  • Under the rules of Prop. 25, trailer bills must (1) be listed in the Budget Act and (2) contain an appropriation of any amount.
  • Even with Prop. 25, some types of trailer bills that could be included in a budget package will require a supermajority — generally two-thirds — vote of each house. This includes, for example, bills that would raise taxes or amend a state law that was approved by voters via a ballot initiative. However, most trailer bills in the budget package will need only a simple majority vote to pass.

Prop. 25: Penalties for a Late Budget

Lawmakers face penalties if they fail to pass the budget bill on or before June 15.

  • Prop. 25 requires lawmakers to permanently forfeit both their pay and their reimbursement for travel and living expenses for each day after June 15 that the budget bill is not passed and sent to the governor.
  • These penalties do not apply to budget-related bills, which do not have to be passed on or before June 15.

Prop. 26: Supermajority Vote for Tax Increases

Any tax increase requires a two-thirds vote of each house of the Legislature.

  • Under the state Constitution, “any change in state statute which results in any taxpayer paying a higher tax” requires a two-thirds vote of each house.
  • This standard was imposed by Prop. 26 of 2010. This measure expanded the definition of a tax increase and thus the scope of the two-thirds vote requirement, which was originally imposed by Prop. 13 of 1978.
  • Prior to Prop. 26, only bills changing state taxes “for the purpose of increasing revenues” required a two-thirds vote. Bills that increased some taxes but reduced others by an equal or larger amount could be passed by a simple majority vote of each house.

Prop. 26: Supermajority Vote for Tax Increases

Prop. 26 of 2010 also expanded the definition of a tax to include some fees.

  • Prior to Prop. 26, lawmakers could create or increase fees by a simple majority vote. These majority-vote fees included regulatory fees intended to address health, environmental, or other problems caused by various products, such as alcohol, oil, or hazardous materials.
  • Prop. 26 reclassified regulatory and certain other fees as taxes. As a result, a two-thirds vote of each house of the Legislature is now required for many charges that previously were considered fees and could be passed by a simple majority vote.

Additional Supermajority Vote Requirements

The state Constitution requires a two-thirds vote of each house of the Legislature in order to:

  • Appropriate money from the General Fund, except for appropriations that are for public schools or that are included in budget bills or in trailer bills.
  • Pass bills that take effect immediately (urgency statutes), except for budget bills and trailer bills.
  • Place constitutional amendments or general obligation bond measures before the voters.
  • Override the governor’s veto of a bill or an item of appropriation.

Prop. 54: A Bill Must Be Published for At Least 72 Hours Before the Legislature Can Act on It

Prop. 54 of 2016 requires bills to be distributed to legislators and published on the Internet, in their final form, at least 72 hours before being passed by the Legislature.

This rule applies to all bills, including the budget bill and other legislation included in the budget package.

This mandatory review period can be waived for a bill if:

  • The governor declares an emergency in response to a disaster or extreme peril, and
  • Two-thirds of legislators in the house considering the bill vote to waive the review period.

Prop. 98: A Funding Guarantee for TK-12 Schools and Community Colleges

Prop. 98 of 1988 guarantees a minimum annual level of funding for TK-14 education.

  • The amount of the guarantee is calculated each year based on one of three tests that apply under varying fiscal and economic conditions. Two of these tests include adjustments for changes in statewide TK-12 attendance. Prop. 98 funding comes from the state General Fund and local property tax revenues.
  • The Legislature can suspend the guarantee for a single year by a two-thirds vote of each house and provide less funding. Following a suspension, the state must increase Prop. 98 funding over time to the level that it would have reached absent the suspension.
  • While the Legislature can provide more funding than Prop. 98 requires, the guarantee has generally served as a maximum funding level.

Prop. 2: Saving for a Rainy Day, Paying Down Debt

Prop. 2 of 2014 revised the rules that apply to the Budget Stabilization Account (BSA) — the state’s constitutional rainy day fund — and also established a new requirement to pay down state budgetary debt.

  • The state is required to set aside 1.5% of General Fund revenues each year, plus additional dollars in years when tax revenues from capital gains are particularly strong.
  • Until 2029-30, half of the revenues go into the BSA and the other half must be used to pay down state budgetary debt, which includes unfunded pension liabilities. Starting in 2030-31, the entire annual transfer goes into the BSA.
  • State policymakers may suspend or reduce the BSA deposit and withdraw funds from the reserve, but only under limited circumstances that qualify as a “budget emergency.”

Prop. 2: A Budget Reserve for TK-14 Education

Prop. 2 of 2014 also created a state budget reserve for TK-12 schools and community colleges called the Public School System Stabilization Account (PSSSA).

  • Deposits come from state capital gains tax revenues in years when those revenues are particularly strong.
  • However, various conditions must be met before these dollars could be transferred to the PSSSA. For example, transfers may occur only in so-called “Test 1” years under Prop. 98, which have been relatively rare.

Prop. 55: Potential New Funding for Medi-Cal From a Tax on the Wealthiest Californians

Prop. 55 of 2016 extends, through 2030, personal income tax rate increases on very high-income Californians and establishes a formula to boost funding for Medi-Cal, which provides health care services to Californians with low incomes.

  • Starting in 2018-19, General Fund revenues — including those raised by Prop. 55 — must first be used to fund (1) the annual Prop. 98 guarantee for K-12 schools and community colleges and (2) the cost of other services that were authorized as of January 1, 2016, as adjusted for population changes, federal mandates, and other factors.
  • If any Prop. 55 revenues remain after meeting these required expenditures, Medi-Cal would receive 50% of this excess, up to a maximum of $2 billion in any fiscal year.
  • Prop. 55 has not yet resulted in any additional funding for Medi-Cal.

Prop. 4: State Appropriations Limit (SAL) — A Cap on Spending

Appropriations are subject to a limit established by Prop. 4 of 1979, as modified by later initiatives. This spending cap is known as the Gann Limit.

  • The SAL limits the amount of state tax proceeds that can be appropriated each year. This limit is adjusted annually for changes in population and per capita personal income.
  • Some appropriations from tax proceeds do not count toward the limit, including debt service and spending that is needed to comply with court or federal mandates.
  • Revenues that exceed the SAL over a two-year period are divided equally between Prop. 98 spending and taxpayer rebates. The state last exceeded the SAL in 2020-21 (but did not do so in the prior year).

State Mandates: Pay for Them or Suspend Them

The state must pay for or suspend mandates that it imposes on local governments.

  • Prop. 4 of 1979 requires the state to reimburse local governments for costs related to a new program or a higher level of service that is mandated by the state.
  • Prop. 1A of 2004 expanded the definition of a mandate to include the transfer of
    financial responsibility from the state to local governments.
  • Prop. 1A also requires the state to suspend a mandate in any year in which local
    governments’ costs are not fully reimbursed.

What Do the Governor and the Legislature Do?

The governor and state legislators play key roles in the state budget process.

The Governor’s Role

California has long had an executive-centered budget process that gives significant authority and power to the governor and the Department of Finance (DOF), which leads the development of the governor’s budget proposals. The governor:

  • Approves, modifies, or rejects spending proposals prepared by state departments and agencies through an internal process coordinated by the DOF.
  • Proposes a spending plan for the state each January, which is introduced as the budget bill in the Legislature.
  • Updates and revises the proposed budget each May (the “May Revision”).
  • Signs or vetoes the bills included in the budget package.
  • Can veto all or part of individual appropriations (line items), but cannot increase any appropriations above the level approved by the Legislature.

The Legislature’s Role

Legislators also play a key role in the budget process by reviewing, revising, and adding to the governor’s proposals, with help from the Legislative Analyst’s Office, commonly known as the LAO. The Legislature:

  • Approves, modifies, or rejects the governor’s budget proposals.
  • Can add new spending or make other changes that substantially revise the governor’s proposals.
  • Needs a simple majority vote of each house to pass budget bills and most trailer bills.
  • Needs a two-thirds vote to pass certain other bills that may be part of the budget package, including bills that increase taxes or that propose constitutional amendments.
  • Needs a two-thirds vote of each house to override the governor’s veto of a bill or an appropriation.

What Is the Role of the Legislature’s Budget Subcommittees in the State Budget Process?

The work of the Assembly Budget Committee and the Senate Budget and Fiscal Review Committee largely happens through subcommittees. Each subcommittee — seven in the Assembly and five in the Senate — focuses on a specific policy area or set of policy areas, like health, housing, or education.

Budget subcommittees have a number of roles in the state budget process. For example, they:

  • Hold dozens of hearings from February to May to review the governor’s proposals, which they can approve, modify, or reject.
  • Meet with policy advocates to understand their priorities and gather intel on what’s happening in a specific policy space.
  • Evaluate budget requests (or “asks”) submitted by advocates and legislators and decide which to include in their own budget plans that they work on throughout the spring.
  • Finalize the Assembly and Senate versions of the budget, which are later combined into a unified legislative budget plan that is typically unveiled in late May or early June.

What Happens When?

The state budget process is cyclical, with no clear stop and start dates. State leaders develop and revise the budget during three distinct periods: July to December, January to mid-May, and mid-May to June. The following sections highlight major budget-related events and activities during each of these periods.

July to December

Work on the state budget during July to December is focused on two areas: 1) revising the June budget package (that is, the budget-related bills signed into law by the governor early in the summer), and 2) preparing for the next state fiscal year.

January to Mid-May

The release of the governor’s proposed budget is the signature event of this period. The Legislature convenes dozens of public hearings to review the governor’s plan.

Mid-May to June

The unveiling of the governor’s revised budget (the May Revision) kicks off this period, which also includes the release of the joint Assembly-Senate budget plan and the announcement of a three-way budget deal between the governor and legislative leaders.


How Can Californians Participate in the State Budget Process?

Californians can inform and influence budget choices by engaging with legislators and their staff as well as with executive branch officials.

Building Relationships Is Key to Effective Advocacy

Building relationships with policymakers and staffers in the Legislature and in the governor’s administration is the foundation of effective budget advocacy.

The Capitol runs on relationships: Who you know is critical to advancing your budget priorities, so it’s important to lay the groundwork for influence by building familiarity and trust with key players in the process by reaching out and scheduling a time to meet in person or virtually. Autumn can be the best time to reach out because workloads tend to be lighter, but it’s never too late to start.

Because turnover can be high in the Legislature and in the governor’s administration, it’s important to pay constant attention to relationship-building. There are always new faces to become acquainted with, so the work of relationship-building never ends.

Californians Have Many Ways to Make Their Voices Heard

With relationships as a foundation, there are a range of tactics that advocates can use to ensure that their voices are heard in the state budget process. For example, you can:

Submit “budget letters” to policymakers outlining your budget priorities.

  • The public’s role includes writing letters that highlight your budget priorities and providing them to legislators and the governor’s administration.
  • Budget letters and other comments should be submitted to the Assembly Budget Committee and the Senate Budget and Fiscal Review Committee using the dedicated email addresses shown at the top of each committee’s home page.
  • While it’s acceptable to send information directly to budget committee consultants’ work emails, advocates should use this option prudently given the high volume of emails that committee consultants receive.
  • However, advocates should never send “spam” emails directly to budget committee consultants. These are email templates that hundreds or thousands of people can use to send the same message to policymakers and staff. Those kinds of emails should go to the dedicated budget committee email addresses instead.

Schedule meetings with key policymakers and staff in the Legislature and in the governor’s administration.

  • Building relationships is crucial to effective advocacy, so it’s important to lay the groundwork for influence by reaching out and scheduling times to meet with key legislators and their staff — particularly on the budget committees and in leadership positions — as well as with key contacts in the governor’s administration.

Provide public comments and — if invited — testify as part of a panel at budget subcommittee hearings.

  • You can share your views during public comment periods at budget subcommittee hearings.
  • Committee chairs set time limits for each public comment. Sometimes the limit is 1 minute, but it’s often shorter and may only include enough time for you to deliver a “me too” comment — name, organization, and position on the issue.
  • In addition, when invited by committee staff, you can provide testimony at a budget subcommittee hearing, which provides more time to share expertise on an issue as well as personal stories, which can be very impactful.

Participate in “lobby days” at the Capitol, joining forces with a broad range of advocates.

  • Lobby days can be impactful — these events bring together hundreds or even thousands of advocates who join forces to focus media and policymakers’ attention on key policy issues, including those affecting health, child care, economic security, and housing.

Advocacy Opportunities During Each Phase of the State Budget Process

Californians can press for their budget priorities throughout the year. This section outlines what you can do during each phase of the state budget process: July to December, January to mid-May, and mid-May to June.

Advocacy Opportunities: July to December

quick take: quietest period of the state budget process

Much happens behind the scenes from July to December, particularly in the governor’s administration, but advocates still have opportunities to make their voices heard

Watch for budget developments in August that affect the issues you work on and be prepared to weigh in on any new proposals.

Schedule introductory meetings with staffers in the Legislature and in the governor’s administration who will be helpful to know for your advocacy.

  • For the Legislature, check the Assembly and Senate websites to see which budget committee consultants focus on your issues and get their email addresses.
  • For the governor’s administration, start with organizational charts that show who works in the Governor’s Office (the governor’s “inner circle” of advisers) and in key positions in the state departments and agencies. For contacts in the Department of Finance, see this chart of responsibilities.

Share your budget priorities with:

  • Key contacts in the Governor’s Office and in state departments, asking for your priorities to be included in the governor’s January 10 budget proposal.
  • Budget committee consultants as well as staff who work for legislative leadership (Assembly Speaker and the Senate President pro Tem).

Advocacy Opportunities: January to Mid-May

quick take: heart of the budget process

January to mid-May is the period with the most consistent and transparent opportunities for public engagement.

Write letters outlining your priorities, including weighing in on the governor’s January proposed budget. Deliver budget letters to the Assembly and Senate budget committee members and staff, legislative leadership, and the Governor’s Office.

Meet with contacts in the Governor’s Office and state departments to discuss the January proposed budget’s approach to education funding and policy and share your ideas for how to improve the governor’s proposals in the May Revision.

Look for opportunities to meet with key contacts in the Legislature to share your priorities and perspectives, including key staff and the chairs of the budget subcommittees.

Draw attention to your issues by:

  • Taking advantage of public comment periods during budget hearings,
  • Focusing on storytelling (including highlighting real-world impacts of policy actions/inaction), and
  • Organizing public actions to raise awareness and garner local and statewide media coverage.

Advocacy Opportunities: Mid-May to June

quick take: fastest-moving period of the budget process

The quick pace during the mid-May to June period can make advocacy challenging as policymakers make major decisions in a short period of time.

Share your views on the May Revision (the governor’s revised budget) during the public comment periods at budget subcommittee hearings.

Urge key legislative staff and members to include your budget priorities in the joint Assembly-Senate budget plan — assuming your idea hasn’t already been embraced by either house or by the governor.

If the Legislature adopts your idea but the governor’s position is questionable or negative, look for ways to move the governor to yes. This could include bringing grassroots pressure to bear, publishing op-eds in key media outlets, and garnering favorable media attention for your cause.


State Budget Resources

  • Department of Finance: The governor’s budget proposals and related documents.
  • Legislative Analyst’s Office: Budget and policy analyses, budget recommendations, and historical budget data.
  • Legislative Counsel: Bills and bill analyses, a free bill-tracking service, the state codes, and the state Constitution.
  • State Assembly and Senate: Committee agendas and other publications, floor session and committee schedules, the annual legislative calendar, and live and archived video streaming of legislative proceedings.
Stay in the know.

Join our email list!

Where Do Things Stand with the 2026-27 State Budget?

Last week, the Legislature passed 16 bills that adjust the spending and policies in the 2026-27 budget package, which Governor Newsom signed into law earlier this summer. The new budget-related legislation passed last week includes: These bills next go to Governor Newsom’s desk. The governor is expected to sign them all — the final budget-related … Continued


Introduction

Every year, California’s governor and Legislature adopt a state budget that provides a framework and funding for vital public services and systems — from child care and health care to housing and the safety net to colleges and TK-12 schools (transitional kindergarten through 12th grade).

But the state budget is about more than dollars and cents.

The budget expresses our values as Californians and as a state. At its best, the budget should reflect our collective efforts to expand economic opportunities, promote well-being, and improve the lives of Californians who are denied the chance to share in our state’s wealth and who deserve the dignity and support to lead thriving lives.

State budget choices impact all Californians, including the 5.7 million students in California’s TK-12 public schools. The state budget provides most of the funding for TK-12 education, which includes more than 1,000 school districts, county offices of education, and charter schools.

While the total size of the state budget helps to determine the amount of annual funding TK-12 schools receive, the Legislature and governor decide how these state funds are allocated across the state. Therefore, it’s important for Californians to participate in the annual budget process to ensure that state leaders are making the strategic choices needed to allow every TK-12 student — from different races, backgrounds, and places — to thrive and share in our state’s economic and social life.

Understanding the financial resources available to TK-12 schools requires familiarity with the state budget, school funding, and the state budget process. To this end, this guide:

  • Highlights key school funding sources,
  • Puts school funding into the larger state budget context,
  • Describes key components of the state budget process, and
  • Shows how Californians can work to shape the state’s TK-12 funding decisions.

The goal is to provide Californians with the tools they need to effectively engage decision makers and advocate for fair and just TK-12 funding and policy choices.

The state spending plan is about more than dollars and cents.

  • The state budget process allows Californians to express our values and priorities for our state as well as for California’s TK-12 system, which educates well over 5 million students from transitional kindergarten through 12th grade.


State dollars are the primary source of funding for California’s TK-12 schools.

  • TK-12 education receives the second-largest share of General Fund dollars, after health and human services.
  • The state distributes school funding in multiple ways, including through a formula as well as through additional programs targeting students’ specific needs.


The governor has the lead role in the budget process.

  • Proposing a state budget for the upcoming fiscal year gives the governor the first word in each year’s budget deliberations.
  • The May Revision gives the governor another opportunity to set the budget and policy agenda for the state.
  • Veto power generally gives the governor the last word in budget decisions.


The Legislature reviews and revises the governor’s proposals.

  • Lawmakers both build on and revise the governor’s proposals as they craft their version of the state budget prior to negotiating an agreement with the governor.


Budget decisions are made throughout the year, and TK-12 education advocates have many ways and opportunities to make their voices heard.

  • Every year, advocates have multiple opportunities to build relationships with policymakers and staffers and work to influence budget decisions.
  • This includes submitting letters to policymakers outlining key budget priorities, providing public comment at budget committee hearings, and meeting with committee staffers, legislators, and officials in the governor’s administration.
  • In short, TK-12 advocates have ample opportunity to stay engaged and involved in the budget process year-round.

Understanding the California State Budget

California’s state budget funds a wide range of public services, from schools to health care to higher education. Understanding where the dollars come from and how they are allocated is essential context for understanding how schools are funded.

the state budget consists of three types of state funds

Three kinds of state funds account for almost two-thirds (65.3%) of California’s $538.9 billion budget for 2026-27, the fiscal year that began on July 1, 2026. Specifically:


Federal funds comprise the rest (34.7%) of the state’s 2026-27 budget.

Most General Fund Revenue Comes from Three State Taxes

Under the enacted 2026-27 state budget, General Fund revenue is estimated to total $230.3 billion, with more than 98% expected to come from California’s “Big Three” taxes:

  • Personal income tax (63.2%) — This is a tax on the income of California residents as well as the income of nonresidents derived from California sources. 
  • Corporation tax (19.6%) — This is a tax imposed on corporations that do business in or derive income from California, with the exception of insurance companies, which instead pay the insurance tax. 
  • Sales & use tax (15.5%) — This is a tax on the purchase of tangible goods in California (the sales tax) or on the use of tangible goods in California that were purchased elsewhere (the use tax).

Other state revenue is estimated to make up about 2% of total projected General Fund revenue in 2026-27. This revenue comes from a broad range of sources, including taxes, fees, and fines.

More Than a Third of State General Fund Spending Supports TK-12 Education

Under the enacted 2026-27 state budget:

  • TK-12 education accounts for more than a third (36.2%) of General Fund spending. 
  • The largest share (37.1%) of General Fund spending supports health and human services. 
  • About 1 out of every 10 General Fund dollars (10.6%) funds higher education, which includes the California Community Colleges, the California State University, and the University of California.

Understanding TK-12 Education Funding

California’s TK-12 schools are funded primarily through Proposition 98 (see box below), a constitutional funding guarantee that sets a minimum funding level for the state’s public schools and community colleges each year. This section explains where funding for TK-12 education comes from and how it is distributed to schools across the state.

what is proposition 98?

Prop. 98 is a constitutional amendment adopted by California voters in 1988 that establishes an annual minimum funding level for schools each fiscal year, commonly referred to as the minimum guarantee. Prop. 98 funding comes from a combination of state General Fund revenue and local property taxes. Prop. 98 spending supports TK-12 schools, community colleges, county offices of education, the state preschool program, and state agencies that provide direct TK-14 instructional programs. While Prop. 98 establishes a required minimum funding level for programs falling under the guarantee as a whole, it does not protect individual programs from spending cuts or elimination.

The Majority of TK-12 Education Funding Comes from the State

In the 2024-25 fiscal year, TK-12 school districts (excluding charter schools) and county offices of education received funding from a broad range of sources, with state funds making up the largest share. Specifically:

  • Almost 60% ($63.8 billion) came from the state.
  • Over a third came from local sources, including 25.6% ($27.9 billion) from local property taxes and 10.2% ($11.1 billion) from other local revenues such as parcel taxes and fees for the use of school buildings.
  • Nearly 6% ($6.4 billion) came from the federal government through a number of federal programs.

Most TK-12 Education Funding Is Allocated Through the Local Control Funding Formula

In the 2024-25 fiscal year, schools received $72.3 billion through the Local Control Funding Formula (LCFF), the primary funding mechanism for TK-12 school districts, charter schools, and county offices of education. This formula:

  • Is funded through a combination of General Fund and local property taxes. 
  • Primarily uses an attendance measure, average daily attendance (ADA), to calculate a funding allocation for each district, charter school, or county office of education. 
  • Sets a per-ADA base grant, which is adjusted by grade level spans (TK-3, 4-6, 7-8, 9-12). The base grants are also annually adjusted for increases in the cost of living. 
  • Includes additional grants to more equitably distribute LCFF dollars across schools. These grants are based on a school district’s enrollment of students in the foster system, students identified as English learners, students from families with low incomes, or students experiencing homelessness. 
  • Mechanically generates funding amounts, but the governor and the Legislature ultimately determine LCFF allocations in the annual state budget by approving any growth in cost of living or other changes that impact funding.

The formula also provides a greater level of local autonomy in TK-12 spending decisions compared to the previous school finance system, which the LCFF replaced in 2013-14. However, TK-12 districts must demonstrate how spending decisions increase or improve services to students with the highest needs.

Schools Also Receive Funding Through Categorical Programs

In addition to LCFF dollars, schools also receive funding through a growing number of categorical programs. Unlike discretionary funding provided through the LCFF, categorical programs fund specific purposes. Each program has its own allocation formulas that differ from the LCFF; therefore, the amounts schools receive vary by program.

As of the 2025-26 state budget, the largest categorical programs were Special Education, the Expanded Learning Opportunities Program, Child Nutrition, State Preschool, and Arts and Music funding (Proposition 28 of 2022).

As with the LCFF, the governor and the Legislature decide each year whether to create categorical programs and increase or decrease funding for existing ones. In recent years, programs such as the Expanded Learning Opportunities Program have been created, directing Prop. 98 dollars to schools earmarked for that specific purpose. Creating new categorical programs comes with a trade-off: more money directed to categoricals means less is available to expand LCFF funding, which gives districts more spending flexibility.


State Budget Process: Terms Every TK-12 Advocate Should Know

Understanding key budget-related terms will help advocates more effectively navigate the state budget process. This section features a dozen definitions drawn from the Budget Center’s glossary of state budget terms, which includes around 100 budget-related words and phrases.


State Budget Process: Three Key Deadlines

There are three key budget-related deadlines. Two of these deadlines are included in the state Constitution, and the third is outlined in state law.

  • January 10: The constitutional deadline for the governor to propose a state budget for the upcoming fiscal year.
  • May 14: The statutory deadline for the governor to release a revised budget, known as the “May Revision” or “May Revise.” The revised budget updates the governor’s January revenue estimates and spending proposals.
  • June 15: The constitutional deadline for the Legislature to pass the initial budget bill for the upcoming fiscal year. This is the bill that becomes the Budget Act once the governor signs it into law.

Three Key Budget Deadlines

Two in the State Constitution (January 10 and June 15), One in State Law (May 14)


The governor must propose a budget for the upcoming fiscal year on or before January 10. The budget must be balanced: Estimated revenues (as determined by the governor) must meet or exceed the governor’s proposed spending.


The governor must release the May Revision on or before May 14.


The Legislature must pass a budget bill for the upcoming fiscal year by midnight on June 15. The budget bill must be balanced: Estimated General Fund revenues (as set forth in the budget bill passed by the Legislature) must meet or exceed General Fund spending.

State Budget Process: What Do the Governor and the Legislature Do?

The governor and state legislators play key roles in the state budget process.

The Governor’s Role

California has long had an executive-centered budget process that gives significant authority and power to the governor and the Department of Finance, which leads the development of the governor’s budget proposals. The governor:

  • Approves, modifies, or rejects spending proposals prepared by state departments and agencies through an internal process coordinated by the Department of Finance.
  • Proposes a spending plan for the state each January, which is introduced as the budget bill in the Legislature.
  • Updates and revises the proposed budget each May (the “May Revision”).
  • Signs or vetoes the bills included in the budget package.
  • Can veto all or part of individual appropriations (line items), but cannot increase any appropriations above the level approved by the Legislature.

The Legislature’s Role

Legislators also play a key role in the budget process by reviewing, revising, and adding to the governor’s proposals, with help from the Legislative Analyst’s Office, commonly known as the LAO. The Legislature:

  • Approves, modifies, or rejects the governor’s budget proposals.
  • Can add new spending or make other changes that substantially revise the governor’s proposals.
  • Needs a simple majority vote of each house to pass budget bills and most trailer bills.
  • Needs a two-thirds vote to pass certain other bills that may be part of the budget package, including bills that increase taxes or that propose constitutional amendments.
  • Needs a two-thirds vote of each house to override the governor’s veto of a bill or an appropriation.

What Is the Role of the Legislature’s Budget Subcommittees in the State Budget Process?

The work of the Assembly Budget Committee and the Senate Budget and Fiscal Review Committee largely happens through subcommittees. Each subcommittee — seven in the Assembly and five in the Senate — focuses on a specific policy area or set of policy areas, like health, housing, or education.

The education-related budget is overseen by these two subcommittees:

  • Senate Budget Subcommittee 1 on Education (known as “Sub 1”), and
  • Assembly Budget Subcommittee 3 on Education Finance (known as “Sub 3”).


Budget subcommittees have a number of roles in the state budget process. For example, they:

  • Hold dozens of hearings from February to May to review the governor’s proposals, which they can approve, modify, or reject.
  • Meet with policy advocates to understand their priorities and gather intel on what’s happening in a specific policy space.
  • Evaluate budget requests (or “asks”) submitted by advocates and legislators and decide which to include in their own budget plans that they work on throughout the spring.
  • Finalize the Assembly and Senate versions of the budget, which are later combined into a unified legislative budget plan that is typically unveiled in late May or early June.

State Budget Process: What Happens When?

The state budget process is cyclical, with no clear stop and start dates. State leaders develop and revise the budget during three distinct periods: July to December, January to mid-May, and mid-May to June. The following sections highlight major budget-related events and activities during each of these periods.

July to December

Work on the state budget during July to December is focused on two areas: 1) revising the June budget package (that is, the budget-related bills signed into law by the governor early in the summer), and 2) preparing for the next state fiscal year.

January to Mid-May

Mid-May to June


How Can TK-12 Advocates Participate in the State Budget Process?

TK-12 advocates can inform and influence budget choices by engaging with legislators and their staff as well as with executive branch officials.

Building Relationships Is Key to Effective Advocacy

Building relationships with policymakers and staffers in the Legislature and in the governor’s administration is the foundation of effective budget advocacy.

The Capitol runs on relationships: Who you know is critical to advancing your budget priorities, so it’s important to lay the groundwork for influence by building familiarity and trust with key players in the process by reaching out and scheduling a time to meet in person or virtually. Autumn can be the best time to reach out because workloads tend to be lighter, but it’s never too late to start.

Because turnover can be high in the Legislature and in the governor’s administration, it’s important to pay constant attention to relationship-building. There are always new faces to become acquainted with, so the work of relationship-building never ends.

Advocates Have Many Ways to Make Their Voices Heard

With relationships as a foundation, there are a range of tactics that advocates can use to ensure that their voices are heard in the state budget process. For example, you can:

Submit “budget letters” to policymakers outlining your budget priorities.

  • The public’s role includes writing letters that highlight your budget priorities and providing them to legislators and the governor’s administration.
  • Budget letters and other comments should be submitted to the Assembly Budget Committee and the Senate Budget and Fiscal Review Committee using the dedicated email addresses shown at the top of each committee’s home page.
  • While it’s acceptable to send information directly to budget committee consultants’ work emails, advocates should use this option prudently given the high volume of emails that committee consultants receive.
  • However, advocates should never send “spam” emails directly to budget committee consultants. These are email templates that hundreds or thousands of people can use to send the same message to policymakers and staff. Those kinds of emails should go to the dedicated budget committee email addresses instead.

Schedule meetings with key policymakers and staff in the Legislature and in the governor’s administration.

  • Building relationships is crucial to effective advocacy, so it’s important to lay the groundwork for influence by reaching out and scheduling times to meet with key legislators and their staff — particularly on the budget committees and in leadership positions — as well as with key contacts in the governor’s administration.

Provide public comments and — if invited — testify as part of a panel at budget subcommittee hearings.

  • You can share your views during public comment periods at budget subcommittee hearings on education funding and policy (the education subcommittees are “Sub 1” in the Senate and “Sub 3” in the Assembly).
  • Committee chairs set time limits for each public comment. Sometimes the limit is 1 minute, but it’s often shorter and may only include enough time for you to deliver a “me too” comment — name, organization, and position on the issue.
  • In addition, when invited by committee staff, you can provide testimony at a budget subcommittee hearing, which provides more time to share expertise on an issue as well as personal stories, which can be very impactful.

Participate in “lobby days” at the Capitol, joining forces with a broad range of TK-12 advocates.

  • Lobby days can be impactful — these events bring together hundreds or even thousands of advocates who join forces to focus media and policymakers’ attention on key policy issues, including those affecting TK-12 education.

Advocacy Opportunities During Each Phase of the State Budget Process

TK-12 advocates can press for their budget priorities throughout the year. This section outlines what you can do during each phase of the state budget process: July to December, January to mid-May, and mid-May to June.

Advocacy Opportunities: July to December

quick take: quietest period of the state budget process

Much happens behind the scenes from July to December, particularly in the governor’s administration, but advocates still have opportunities to make their voices heard.

Watch for budget developments in August that affect the issues you work on and be prepared to weigh in on any new proposals affecting TK-12 education.

Schedule introductory meetings with staffers in the Legislature and in the governor’s administration who will be helpful to know for your advocacy.

  • For the Legislature, check the Assembly and Senate websites to see which budget committee consultants focus on TK-12 education and get their email addresses.
  • For the governor’s administration, start with organizational charts that show who works in the Governor’s Office (the governor’s “inner circle” of advisers) and in key positions in the state departments and agencies. For contacts in the Department of Finance, see this chart of responsibilities.

Share your budget priorities with:

  • Key contacts in the Governor’s Office and in state departments, asking for your priorities to be included in the governor’s January 10 budget proposal.
  • Budget committee consultants as well as staff who work for legislative leadership (Assembly Speaker and the Senate President pro Tem).

Advocacy Opportunities: January to Mid-May

quick take: heart of the budget process

January to mid-May is the period with the most consistent and transparent opportunities for public engagement.

Write letters outlining your priorities, including weighing in on the governor’s January proposed budget. Deliver budget letters to the Assembly and Senate budget committee members and staff, legislative leadership, and the Governor’s Office.

Meet with contacts in the Governor’s Office and state departments to discuss the January proposed budget’s approach to education funding and policy and share your ideas for how to improve the governor’s proposals in the May Revision.

Look for opportunities to meet with key contacts in the Legislature to share your priorities and perspectives, including key staff and the chairs of the budget subcommittees, especially the education subcommittees: “Sub 1” in the Senate and “Sub 3” in the Assembly.

Draw attention to your issues by:

  • Taking advantage of public comment periods during budget hearings,
  • Focusing on storytelling (including highlighting real-world impacts of policy actions/inaction), and
  • Organizing public actions to raise awareness and garner local and statewide media coverage.

Advocacy Opportunities: Mid-May to June

quick take: fastest-moving period of the budget process

The quick pace during the mid-May to June period can make advocacy challenging as policymakers make major decisions in a short period of time.

Share your views on the May Revision (the governor’s revised budget) during the public comment periods at budget subcommittee hearings.

Urge key legislative staff and members to include your budget priorities in the joint Assembly-Senate budget plan — assuming your idea hasn’t already been embraced by either house or by the governor.

If the Legislature adopts your idea but the governor’s position is questionable or negative, look for ways to move the governor to yes. This could include bringing grassroots pressure to bear, publishing op-eds in key media outlets, and garnering favorable media attention for your cause.


State Budget Resources

  • Department of Finance: The governor’s budget proposals and related documents.
  • Legislative Analyst’s Office: Budget and policy analyses, budget recommendations, and historical budget data.
  • Legislative Counsel: Bills and bill analyses, a free bill-tracking service, the state codes, and the state Constitution.
  • State Assembly and Senate: Committee agendas and other publications, floor session and committee schedules, the annual legislative calendar, and live and archived video streaming of legislative proceedings.
  • Budget Academy: The Budget Center’s essential resources for understanding and navigating the California state budget.

Stay in the know.

Join our email list!


key takeaway

California’s state budget reserves, including the “rainy day fund” and other reserve accounts, serve as a financial safety net for services like education, health care, and child care during economic downturns. The rules for depositing and withdrawing funds are complex, and policymakers should consider reforms, such as excluding reserve deposits from the Gann Limit spending cap, to strengthen the state budget’s resilience during a recession.

Introduction

California has several state budget reserves. These reserves help to maintain essential public services — like education, health care, and child care — when revenues fall short, such as during recessions. Reserves aren’t for everyday spending, but rather a financial safety net for the state.

This report describes California’s state budget reserves, explains how funds can be accessed and used, and discusses proposals to reshape these reserves that have been floated in recent years.

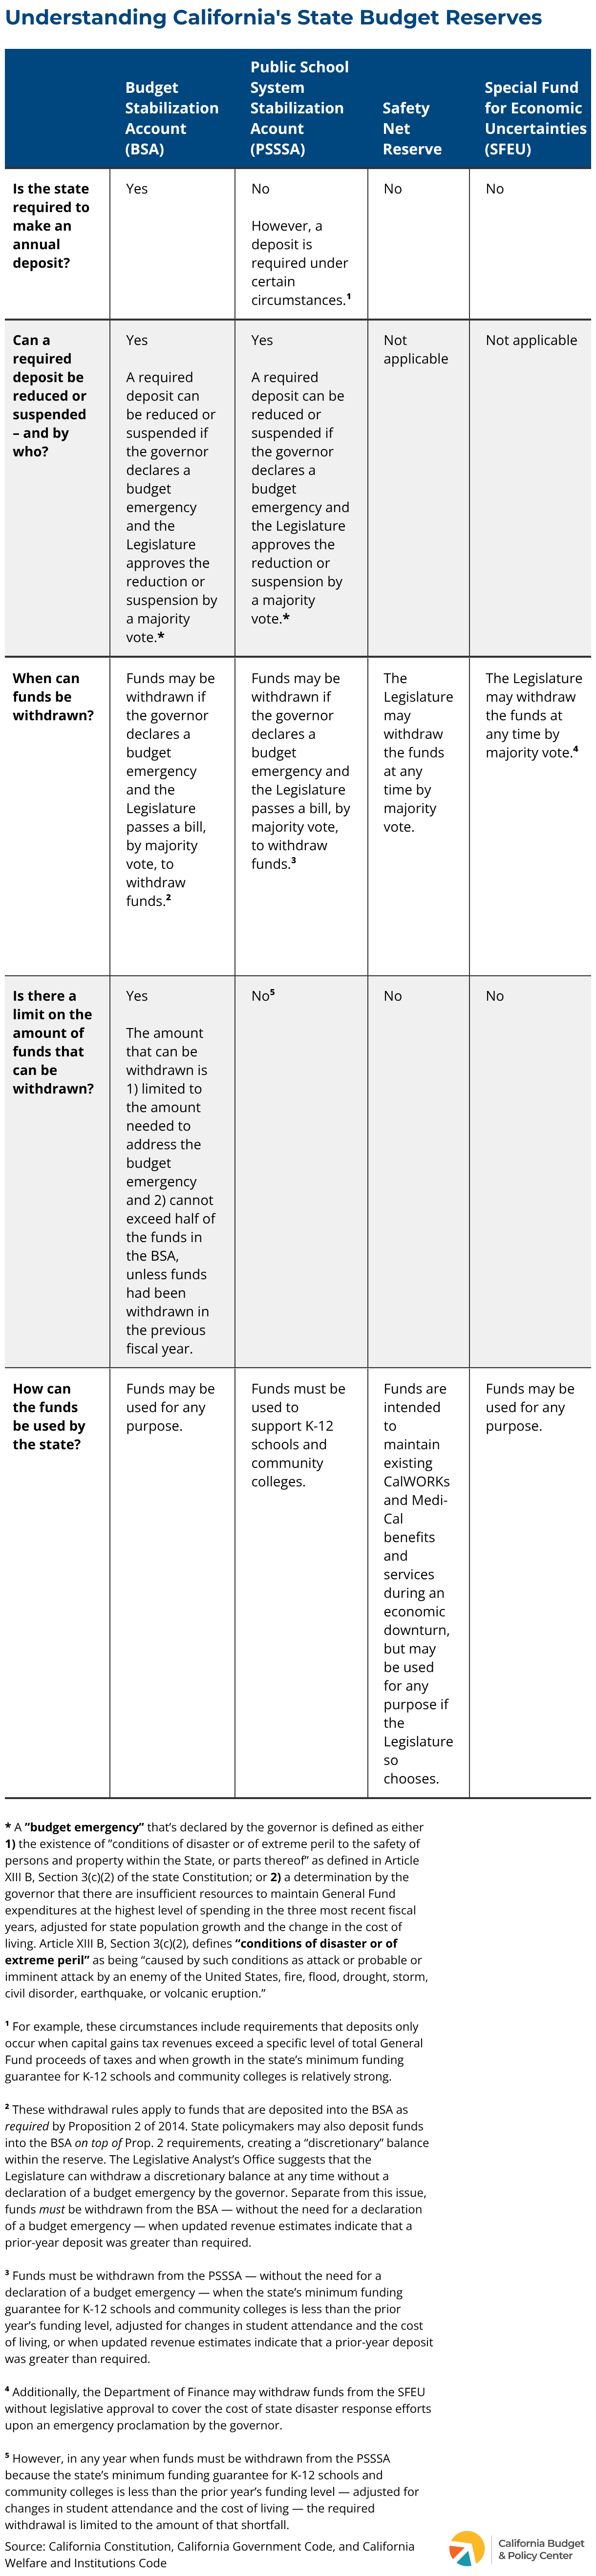
state budget Reserves in a nutshell

Budget Stabilization Account (BSA): California’s Largest Reserve

The BSA is California’s largest state budget reserve. Deposits into and withdrawals from this “rainy day fund” are based on complex rules that were added to the state Constitution by Proposition 2 of 2014.1Prop. 2 was placed on the November 2014 statewide ballot by the Legislature; voters approved the measure by a more than 2-to-1 margin. Prop. 2’s rules are found in the California Constitution (Article XVI, Sections 20 to 22). Key rules include the following:

An annual deposit is required. Prop. 2 requires that 1.5% of General Fund revenues be set aside every year. Until 2029-30 half of these revenues must be deposited into the BSA and the other half must be used to pay down certain state debts.2Revenues that are set aside for paying down state debts may be used for several types of debt, including reducing unfunded liabilities associated with state-level pension plans and prefunding other retirement benefits, such as retiree health care. Beginning in 2030-31, the entire amount must be deposited into the BSA, although state leaders will have the option of redirecting up to one-half of each year’s deposit to pay down debts.

In some years, the state must set aside additional General Fund revenues. This occurs in years when estimated General Fund revenues that come from personal income taxes on capital gains exceed 8% of total General Fund proceeds of taxes.3A capital gain is the increase in the value of an asset — like stock market shares — between the date of purchase and the date of sale. This increase represents income to the asset holder and is subject to the personal income tax in California. The share of these “excess” capital gains revenues that is not owed to K-12 schools and community colleges under the state’s Prop. 98 funding guarantee must be used for BSA deposits and debt repayments, following the same requirements as the mandatory 1.5% deposit.  Since Prop. 2 was enacted, capital gains tax revenues have exceeded the 8% threshold in most years, but could fall below the threshold in years when there are downturns in the stock market.

State leaders may also make discretionary deposits. In addition to the mandatory annual deposits required by Prop. 2, policymakers have the option of saving additional, discretionary revenue in the BSA.

The required annual deposit may be reduced or suspended in the event of a “budget emergency. If the governor declares a budget emergency, the state may reduce or suspend the required BSA deposit with a majority vote of each house of the Legislature.4In contrast, the portion of General Fund revenues that is required to be used for debt payments cannot be reduced or suspended under any circumstances. Prop. 2 defines a budget emergency as a situation where:

  • Conditions of disaster or extreme peril are present5A budget emergency that is declared in response to a disaster or extreme peril must meet the definition provided in Article XIII B, Section 3(c)(2) of the state Constitution. This section refers to the existence of “conditions of disaster or of extreme peril to the safety of persons and property within the State, or parts thereof” and defines these conditions as being “caused by such conditions as attack or probable or imminent attack by an enemy of the United States, fire, flood, drought, storm, civil disorder, earthquake, or volcanic eruption.”; or
  • The state has insufficient resources to maintain General Fund expenditures at the highest level of spending in the three most recent fiscal years, adjusted for state population growth and the change in the cost of living.6General Fund expenditures for the prior three fiscal years would be based on the level of spending “estimated at the time of enactment” of the budget bill for each fiscal year. The change in the “cost of living” would be measured using the California Consumer Price Index.

BSA funds may be withdrawn in the event of a budget emergency, but the entire balance cannot be removed at once. If the governor declares a budget emergency and the Legislature agrees with a majority vote of each house, funds may be taken out of the BSA.7The BSA balance may be reduced for another reason unrelated to a budget emergency. Specifically, Prop. 2 requires revisions to prior calculations of “excess” capital gains revenues — once in each of the two subsequent years — as updated revenue estimates become available. If a revision of “excess” capital gains revenues determines that a prior-year deposit to the BSA was greater than required, then the amount of funds equal to the over-deposit must be withdrawn from the reserve and returned to the General Fund. Alternatively, if a prior-year deposit was smaller than required, then funds must be added to the BSA to make up the difference. This after-the-fact “true-up” process  does not apply to the portion of “excess” capital gains revenues that is used to pay down state debts each year. The true-up process also does not apply to the 1.5% of General Fund revenues that are required to be set aside each year. However, the entire balance cannot be removed immediately. Only the amount needed to address the budget emergency may be withdrawn, subject to the additional limitation that a withdrawal may not exceed 50% of the BSA balance in the first year of a budget emergency. In the second consecutive year of a budget emergency, all of the funds remaining in the BSA may be withdrawn.

Funds that are taken out of the BSA may go toward any purpose determined by the Legislature. For example, these dollars could be used for health care services, subsidized child care for working families, cash assistance for people with low incomes, K-12 schools, and any number of other public services and systems.

Funds in the BSA cannot exceed 10% of General Fund tax revenues. Prop. 2 caps the balance of the BSA. Once the balance — excluding any discretionary deposits — reaches 10% of General Fund tax revenues, any revenue that would otherwise have been required to go into the reserve must be instead spent on infrastructure, which includes housing. Prior to 2026, the BSA balance reached the cap twice — in 2022-23 and 2023-24 — but then dropped below the cap as state leaders withdrew funds in some years to address budget shortfalls.

Public School System Stabilization Account (PSSSA): The Reserve for K-12 Schools & Community Colleges

Prop. 2 of 2014 also established the PSSSA, the state’s budget reserve for California’s K-12 schools and community colleges. Prop. 2 does not require an annual deposit into this reserve. Moreover, Prop. 2 restricts the circumstances under which transfers to the PSSSA can occur. For a PSSSA deposit to be required, all of the following conditions must be met:

  • General Fund revenues that come from personal income taxes on capital gains are relatively strong;8Specifically, capital gains revenues must exceed 8% of total General Fund proceeds of taxes.
  • Growth in General Fund revenues leads to relatively strong growth in the state’s annual minimum funding guarantee for K-12 schools and community colleges;9A PSSSA deposit can only occur in so-called “Test 1” years under the state’s Prop. 98 minimum funding guarantee for K-12 schools and community colleges. Test 1, which guarantees K-14 education a percentage of General Fund revenues. However, even in certain Test 1 years, the amount of growth in state per capita personal income from the prior year can prevent a deposit to the PSSSA. and
  • The Legislature does not suspend the annual K-14 education minimum funding guarantee.

Even under these restricted circumstances, Prop. 2 limits the size of the deposit to the schools reserve when such a deposit is required.10For example, Prop. 2 specifies that transfers to the PSSSA may not exceed the difference between the Test 1 funding level under Prop. 98 and the “Test 2” funding level, which is determined by year-to-year growth in state per capita personal income. Prop. 2 also limits the size of the deposits to the PSSSA by prioritizing funding for K-14 education cost-of-living adjustments over deposits to the PSSSA.

Deposits to the PSSSA may be reduced or suspended in the event of a budget emergency under the same rules that govern reductions or suspensions of deposits to the BSA (see the prior section of this report). Similarly, funds may be withdrawn from the schools reserve if the governor declares a budget emergency and the Legislature agrees with a majority vote of each house.11Prop. 2 requires funds to be withdrawn from the PSSSA, even without a declaration of a budget emergency, when prior-year PSSSA deposits were greater than required. Prop. 2 also requires a withdrawal of funds from the PSSSA in any year when the Prop. 98 minimum funding guarantee is less than the prior-year Prop. 98 funding level, adjusted for changes in student attendance and the cost of living. In this case, the required withdrawal would be limited to the amount needed to reach the prior year’s funding level. Prop. 2 defines change in “cost of living” as the higher of 1) the percent change in California per capita personal income from the preceding year or 2) the cost-of-living adjustment applied to school district and community college district general purpose apportionments.

In contrast to the rules governing the withdrawal of funds from the BSA, all of the PSSSA funds may be withdrawn in one year. Moreover, funds withdrawn from the PSSSA must be used to support K-12 schools and community colleges.

Safety Net Reserve: Funds to Protect the Medi-Cal and CalWORKs Programs

The Safety Net Reserve was created in 2018 to set aside funds to help cover the costs of two programs that often see increases in enrollment during recessions: Medi-Cal and California Work Opportunity and Responsibility to Kids (CalWORKs).12The Safety Net Fund is authorized in California Welfare and Institutions Code, Section 11011. Both of these programs serve Californians with low incomes — with Medi-Cal delivering health coverage, and CalWORKs providing modest cash assistance to families with children. During economic downturns, more people become unemployed and temporarily rely on these programs to cover their basic needs, increasing state costs.

The Safety Net Reserve is not a constitutional reserve, so there are no binding requirements governing deposits or withdrawals. This means that funds can be transferred into and withdrawn from the reserve at the discretion of the Legislature. In fact, state policymakers voluntarily deposited $900 million in the Safety Net Reserve before draining all of those funds in 2024 to help address a $55 billion state budget problem.

Moreover, while state law specifies that the funds are to be used only for Medi-Cal and CalWORKs costs during economic downturns, state policymakers could decide to modify this language and use the funds for other purposes. However, in establishing this reserve, policymakers clearly recognized the need to protect critical services for Californians with low incomes from budget cuts — cuts that would undermine Medi-Cal and CalWORKs at the very time that these programs are needed most.

Dive Deeper Into California’s Budget Reserves

For a deeper understanding of California’s reserve accounts, explore the Budget Center’s companion resources:

Special Fund for Economic Uncertainties (SFEU): The Discretionary Reserve

The SFEU is the state’s discretionary General Fund budget reserve, meaning policymakers have a great deal of latitude in spending the funds in the reserve.13The SFEU (originally called the “Reserve for Economic Uncertainties”) was created through the 1980-81 Budget Act and is authorized in California Government Code, Section 16418. The amount of money in the SFEU is equal to the difference between General Fund resources and General Fund spending in a given fiscal year.14Specifically, the SFEU balance is equal to the General Fund balance carried over from the prior year, plus revenues and transfers, minus expenditures and encumbrances. Legislative Analyst’s Office, The 2020-21 Budget: Structuring the Budget (February 10, 2020), p. 11.

The SFEU acts as a buffer against unanticipated revenue shortfalls or spending increases. Due to California’s constitutional balanced-budget requirement, which requires the state to enact a budget in which spending does not exceed available resources, the projected SFEU balance cannot be less than zero at the time the annual budget is adopted. However, if state revenues come in lower than projected and/or spending unexpectedly rises, the SFEU balance will decline, and may become negative as spending begins to exceed revenues.

The Legislature can appropriate funds from the SFEU at any time and for any purpose. Additionally, in the event of a disaster, the governor can allocate funds from the SFEU without the prior approval of the Legislature. Specifically, when the governor declares a state of emergency, the Department of Finance (DOF) can transfer funds from the SFEU into a subaccount called the Disaster Response-Emergency Operations Account (DREOA).15The amount that may be transferred to the DREOA is limited to the amount necessary to cover disaster-related claims that exceed the available balance in the account. California Government Code, Section 8690.6(d). These funds are allocated to state agencies for costs that are “immediate and necessary to deal with an ongoing or emerging crisis.”16The DOF is required to notify the Joint Legislative Budget Committee as well as the fiscal committees in each house before any funds may be allocated from the SFEU in response to a disaster. Funds in the DREOA can be spent for disaster response costs that occur within 120 days of the Governor’s emergency proclamation. The DOF can extend this time period in up to 120-day increments upon notifying the Legislature, subject to certain limitations. California Government Code, Section 8690.6.

Projected Surplus Temporary Holding Account: A Place to Set Aside Anticipated Surplus Revenues

State leaders created the Projected Surplus Temporary Holding Account in 2024. This account gives policymakers a place to temporarily set aside anticipated surplus revenues, “ensuring that funds are only spent once they are realized.”17Office of Governor Gavin Newsom, press release (September 30, 2024).

State leaders have broad authority to determine whether or how to use this holding account. The only requirement is that revenues that go into the account cannot remain there for longer than one year. If state revenues materialize as projected, the revenues in the account may be spent for any purpose or transferred back to the General Fund for future use.18California Government Code, Section 16418.7.

This holding account is a “pilot budgeting project” that expires at the end of 2030, although state leaders could approve an extension as well as potentially modify the rules.

What’s Next for California’s State Budget Reserves?

The rules that govern California’s budget reserves can be amended by voters or state policymakers. Changing the reserve rules established by Prop. 2 (2014) would require voters to approve a constitutional amendment.19Amendments can be placed on a statewide ballot through a citizens initiative or by the Legislature. Other reserve rules can be changed by state policymakers without the need for voter approval.

In recent years, state policymakers and others have advanced proposals to revise California’s reserve policies, although none have moved beyond the conceptual stage. Common proposals for changing state reserve policies include the following:

Changes to the rainy day fund or the Gann Limit would require amending the state Constitution. This means that voters would have the last word on the most significant proposals to modify California’s state budget reserves.

  • 1
    Prop. 2 was placed on the November 2014 statewide ballot by the Legislature; voters approved the measure by a more than 2-to-1 margin. Prop. 2’s rules are found in the California Constitution (Article XVI, Sections 20 to 22).
  • 2
    Revenues that are set aside for paying down state debts may be used for several types of debt, including reducing unfunded liabilities associated with state-level pension plans and prefunding other retirement benefits, such as retiree health care.
  • 3
    A capital gain is the increase in the value of an asset — like stock market shares — between the date of purchase and the date of sale. This increase represents income to the asset holder and is subject to the personal income tax in California.
  • 4
    In contrast, the portion of General Fund revenues that is required to be used for debt payments cannot be reduced or suspended under any circumstances.
  • 5
    A budget emergency that is declared in response to a disaster or extreme peril must meet the definition provided in Article XIII B, Section 3(c)(2) of the state Constitution. This section refers to the existence of “conditions of disaster or of extreme peril to the safety of persons and property within the State, or parts thereof” and defines these conditions as being “caused by such conditions as attack or probable or imminent attack by an enemy of the United States, fire, flood, drought, storm, civil disorder, earthquake, or volcanic eruption.”
  • 6
    General Fund expenditures for the prior three fiscal years would be based on the level of spending “estimated at the time of enactment” of the budget bill for each fiscal year. The change in the “cost of living” would be measured using the California Consumer Price Index.
  • 7
    The BSA balance may be reduced for another reason unrelated to a budget emergency. Specifically, Prop. 2 requires revisions to prior calculations of “excess” capital gains revenues — once in each of the two subsequent years — as updated revenue estimates become available. If a revision of “excess” capital gains revenues determines that a prior-year deposit to the BSA was greater than required, then the amount of funds equal to the over-deposit must be withdrawn from the reserve and returned to the General Fund. Alternatively, if a prior-year deposit was smaller than required, then funds must be added to the BSA to make up the difference. This after-the-fact “true-up” process  does not apply to the portion of “excess” capital gains revenues that is used to pay down state debts each year. The true-up process also does not apply to the 1.5% of General Fund revenues that are required to be set aside each year.
  • 8
    Specifically, capital gains revenues must exceed 8% of total General Fund proceeds of taxes.
  • 9
    A PSSSA deposit can only occur in so-called “Test 1” years under the state’s Prop. 98 minimum funding guarantee for K-12 schools and community colleges. Test 1, which guarantees K-14 education a percentage of General Fund revenues. However, even in certain Test 1 years, the amount of growth in state per capita personal income from the prior year can prevent a deposit to the PSSSA.
  • 10
    For example, Prop. 2 specifies that transfers to the PSSSA may not exceed the difference between the Test 1 funding level under Prop. 98 and the “Test 2” funding level, which is determined by year-to-year growth in state per capita personal income. Prop. 2 also limits the size of the deposits to the PSSSA by prioritizing funding for K-14 education cost-of-living adjustments over deposits to the PSSSA.
  • 11
    Prop. 2 requires funds to be withdrawn from the PSSSA, even without a declaration of a budget emergency, when prior-year PSSSA deposits were greater than required. Prop. 2 also requires a withdrawal of funds from the PSSSA in any year when the Prop. 98 minimum funding guarantee is less than the prior-year Prop. 98 funding level, adjusted for changes in student attendance and the cost of living. In this case, the required withdrawal would be limited to the amount needed to reach the prior year’s funding level. Prop. 2 defines change in “cost of living” as the higher of 1) the percent change in California per capita personal income from the preceding year or 2) the cost-of-living adjustment applied to school district and community college district general purpose apportionments.
  • 12
    The Safety Net Fund is authorized in California Welfare and Institutions Code, Section 11011.
  • 13
    The SFEU (originally called the “Reserve for Economic Uncertainties”) was created through the 1980-81 Budget Act and is authorized in California Government Code, Section 16418.
  • 14
    Specifically, the SFEU balance is equal to the General Fund balance carried over from the prior year, plus revenues and transfers, minus expenditures and encumbrances. Legislative Analyst’s Office, The 2020-21 Budget: Structuring the Budget (February 10, 2020), p. 11.
  • 15
    The amount that may be transferred to the DREOA is limited to the amount necessary to cover disaster-related claims that exceed the available balance in the account. California Government Code, Section 8690.6(d).
  • 16
    The DOF is required to notify the Joint Legislative Budget Committee as well as the fiscal committees in each house before any funds may be allocated from the SFEU in response to a disaster. Funds in the DREOA can be spent for disaster response costs that occur within 120 days of the Governor’s emergency proclamation. The DOF can extend this time period in up to 120-day increments upon notifying the Legislature, subject to certain limitations. California Government Code, Section 8690.6.
  • 17
    Office of Governor Gavin Newsom, press release (September 30, 2024).
  • 18
    California Government Code, Section 16418.7.
  • 19
    Amendments can be placed on a statewide ballot through a citizens initiative or by the Legislature.

Stay in the know.

Join our email list!

California has several budget reserves that help to manage annual state revenues and protect services when the state faces a budget deficit. California’s Constitution and state law govern when funds may be withdrawn from the state’s reserves, the amount that can be withdrawn, and how funds may be used.

TWO RESERVE ACCOUNTS ARE ESTABLISHED IN THE STATE CONSTITUTION:

Three reserve accounts are established in state law:

The following table answers five key questions about California’s budget reserves:

  1. Is the state required to make an annual deposit?
  2. Can a required deposit be reduced or suspended — and by who?
  3. When can the funds be withdrawn?
  4. Is there a limit on the amount of funds that can be withdrawn?
  5. How can the funds be used by the state?

Dive Deeper Into California’s Budget Reserves

For a deeper understanding of California’s reserve accounts, explore the Budget Center’s companion resources:

Stay in the know.

Join our email list!

Watch to learn more

Just like households save for emergencies, California sets aside money in budget reserves. Budget reserves are California’s way of preparing for the unexpected, saving a little today to protect vital public services tomorrow.

Dive Deeper Into California’s Budget Reserves

For a deeper understanding of California’s reserve accounts, explore the Budget Center’s companion resources:

In this video, we break down how California’s state reserves work, including the four main reserve accounts: the Budget Stabilization Account (the state’s “rainy day fund”), the Public School System Stabilization Account, the Safety Net Reserve, and the Special Fund for Economic Uncertainties.

Learn how these reserves are funded, when they can be used, and why balancing savings with current investments is key to supporting Californians’ well-being.

The Budget Center’s essential resources for understanding and navigating the California state budget — all in one place.

Stay in the know.

Join our email list!

What’s the difference between income and wealth? Taxes for individuals and corporations in California? Tax credits and deductions? Corporate revenues and corporate profits? Understanding these key terms is critical to navigating the state budget and its intersection with California’s tax and revenue system to generate ongoing resources and provide quality education, affordable health care, child care, housing, and other services for communities.

Key Terms

5 Facts to Know About Corporate Taxes in California

Corporate tax breaks and profit shifting reduce state revenues by billions annually. Reining in corporate tax breaks and strengthening California’s revenue base is long overdue.

Did you know? Closing the water’s edge loophole would address offshore tax avoidance and raise $3 Billion in state revenues.

Portrait of a black woman in front of her apartment

Building an Affordable California Requires Public Investment

Strengthening California’s revenue base is long overdue — and now, as the federal government abandons its responsibility to support the health and well-being of all Americans, it is more urgent than ever.

Stay in the know.

Join our email list!

Dollars & Democracy: An Introduction to California’s State Budget Process is an introductory training slide deck that breaks down how California’s state budget works. Designed to be clear, engaging, and accessible, this slide deck explains the fundamentals of the state budget, the rules that shape the process, the key decision-makers involved, and the advocacy opportunities available at each stage of the budget cycle. This training is designed for advocates, community organizers, students, journalists, and anyone looking to better understand how California’s budget decisions are made.

The Budget Center’s essential resources for understanding and navigating the California state budget — all in one place.

Stay in the know.

Join our email list!