Prop. 42 would prohibit new taxes on the ownership of certain assets as well as taxes that apply retroactively. The primary intent of the measure is to invalidate Prop. 40 — the one-time billionaire tax measure also appearing on the November ballot — if it receives more votes, and it would also create new barriers to raising progressive state revenue in the future to adequately meet the needs of Californians.
What Would Prop. 42 Do?
Prop. 42 would amend the state Constitution to prohibit taxes on the ownership of certain assets and on certain retroactive taxes.
Prohibition on New Taxes on Assets
Prop. 42 would prohibit the imposition of any new state tax — enacted on or after January 1, 2026 — on the ownership of financial assets (such as bank accounts, stocks, bonds, or mutual funds), retirement accounts, interests in businesses, intellectual property, and other personal property (such as vehicles, jewelry, artwork, and other movable, physical property).
Prohibition on Retroactive Taxes
Prop. 42 would prohibit the imposition of new retroactive taxes, specifically any tax that is based on “conduct, activities, or a status” that preceded the effective date of the tax. The measure also explicitly prohibits taxes based on someone’s residency status prior to the tax going into effect. An exception would be made for retroactive taxes in cases where the revenues would be used to respond to a governor-declared emergency and the tax does not apply retroactively for more than one year before the effective date.
What Would Prop. 42 Mean for Californians and the State Budget?
The primary intent of Prop. 42 is to invalidate Prop. 40, which would create a one-time tax on the wealth of billionaires. The tax would apply retroactively to billionaires who were California residents on January 1, 2026 and would apply to financial assets like stocks and bonds and other types of assets that would put it in direct conflict with Prop. 42’s prohibition of such taxes — though Prop. 40 would exclude retirement accounts, which is a key focus of Prop. 42. If both measures were to pass and Prop. 42 received more votes, Prop. 40 would likely be invalidated.
But the measure would also have more far-reaching consequences by making it harder for state leaders to raise revenues from wealthy households to effectively meet the needs of Californians and to quickly adapt to changing circumstances.
This would come at a time when California is facing challenges on multiple fronts — the consequences of the steep federal cuts to health care and food assistance enacted in H.R. 1, the sustained high poverty rate, the ongoing housing affordability and homelessness crises, and rising costs of maintaining current services due to inflation and an aging population. Addressing these issues and ensuring California communities can thrive will require the state to substantially raise ongoing revenues.
While Prop. 42 would reduce the options state policymakers have to increase revenues, California voters may still be able to amend the state Constitution in the future to allow a new tax on assets or one that applied retroactively. However, legal challenges are possible and there is no absolute certainty on how courts would rule.
Impacts of Prohibition on Taxing Assets
Currently, the ownership of assets is generally not taxed in California, with the exception of local property taxes on real estate — already subject to strict constitutional limits under Prop. 13 (1978) — and some types of personal property including boats, planes, and business equipment, as well as state vehicle license fees.
While the state does not currently tax the ownership of financial assets, business interests, or other intangible assets, it is not constitutionally barred from doing so. Prop. 42 would enshrine this prohibition in the state Constitution, which would prevent state leaders from creating wealth-based taxes in the future. This would limit the options policymakers have to raise progressive revenue to maintain and improve state services that support Californians in staying healthy, housed, and economically secure.
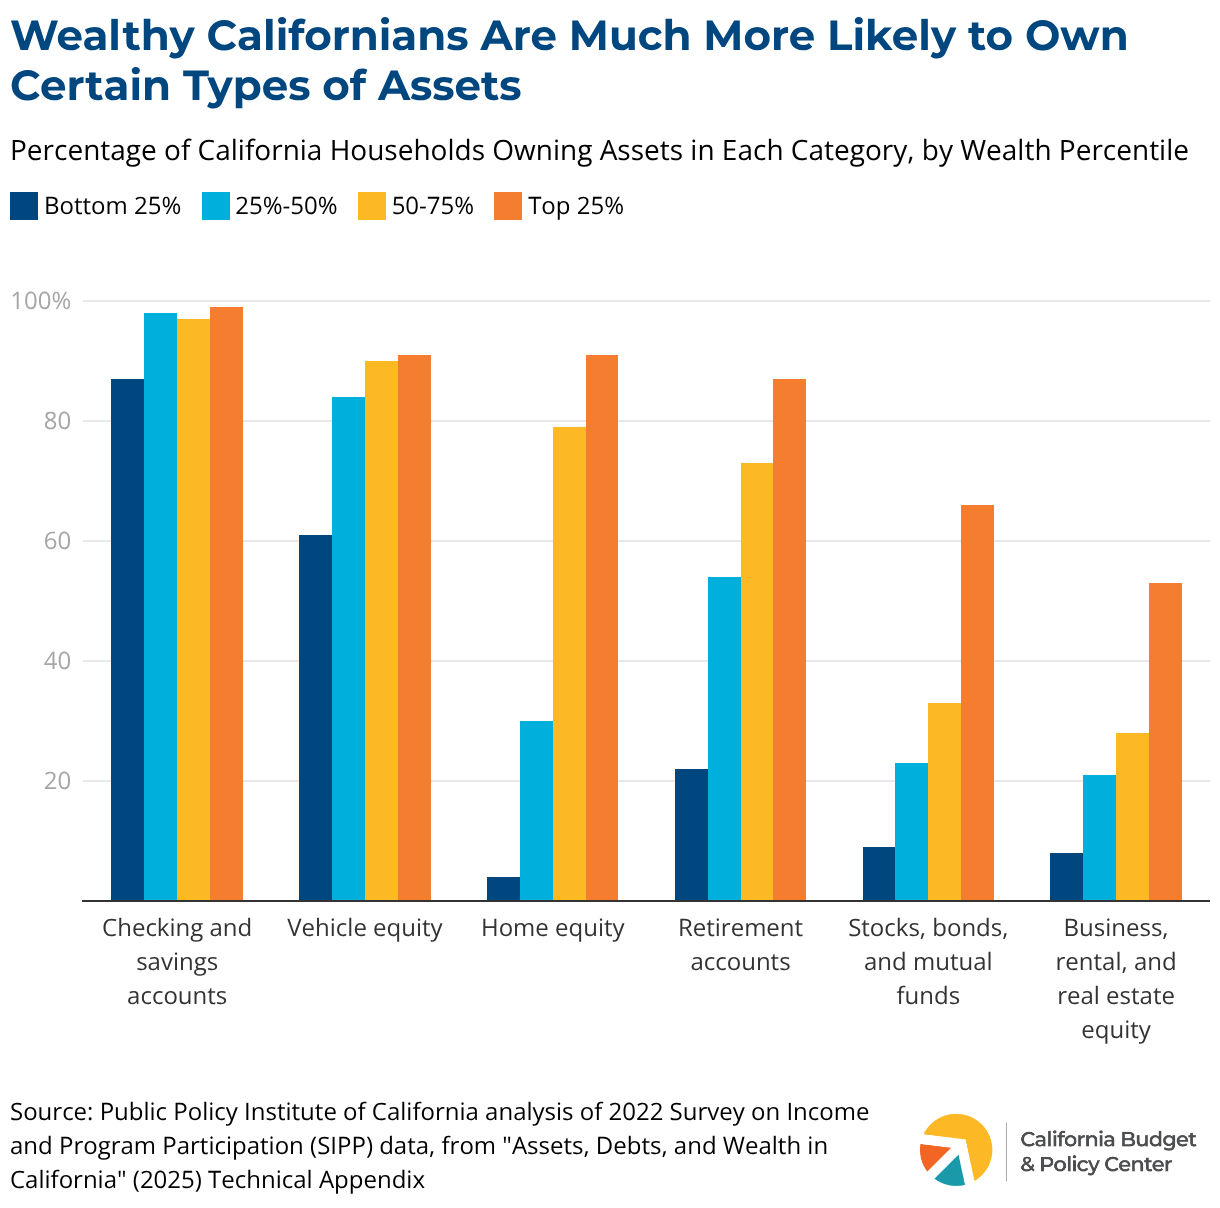
While most Californians hold assets in some form, such as checking or savings accounts, some types of assets are far more likely to be held by wealthy households. For example, about two-thirds of Californians in the top 25% of the wealth distribution hold stocks, bonds, or mutual funds, compared to only 9% of Californians in the bottom 25%, according to an analysis by the Public Policy Institute of California.
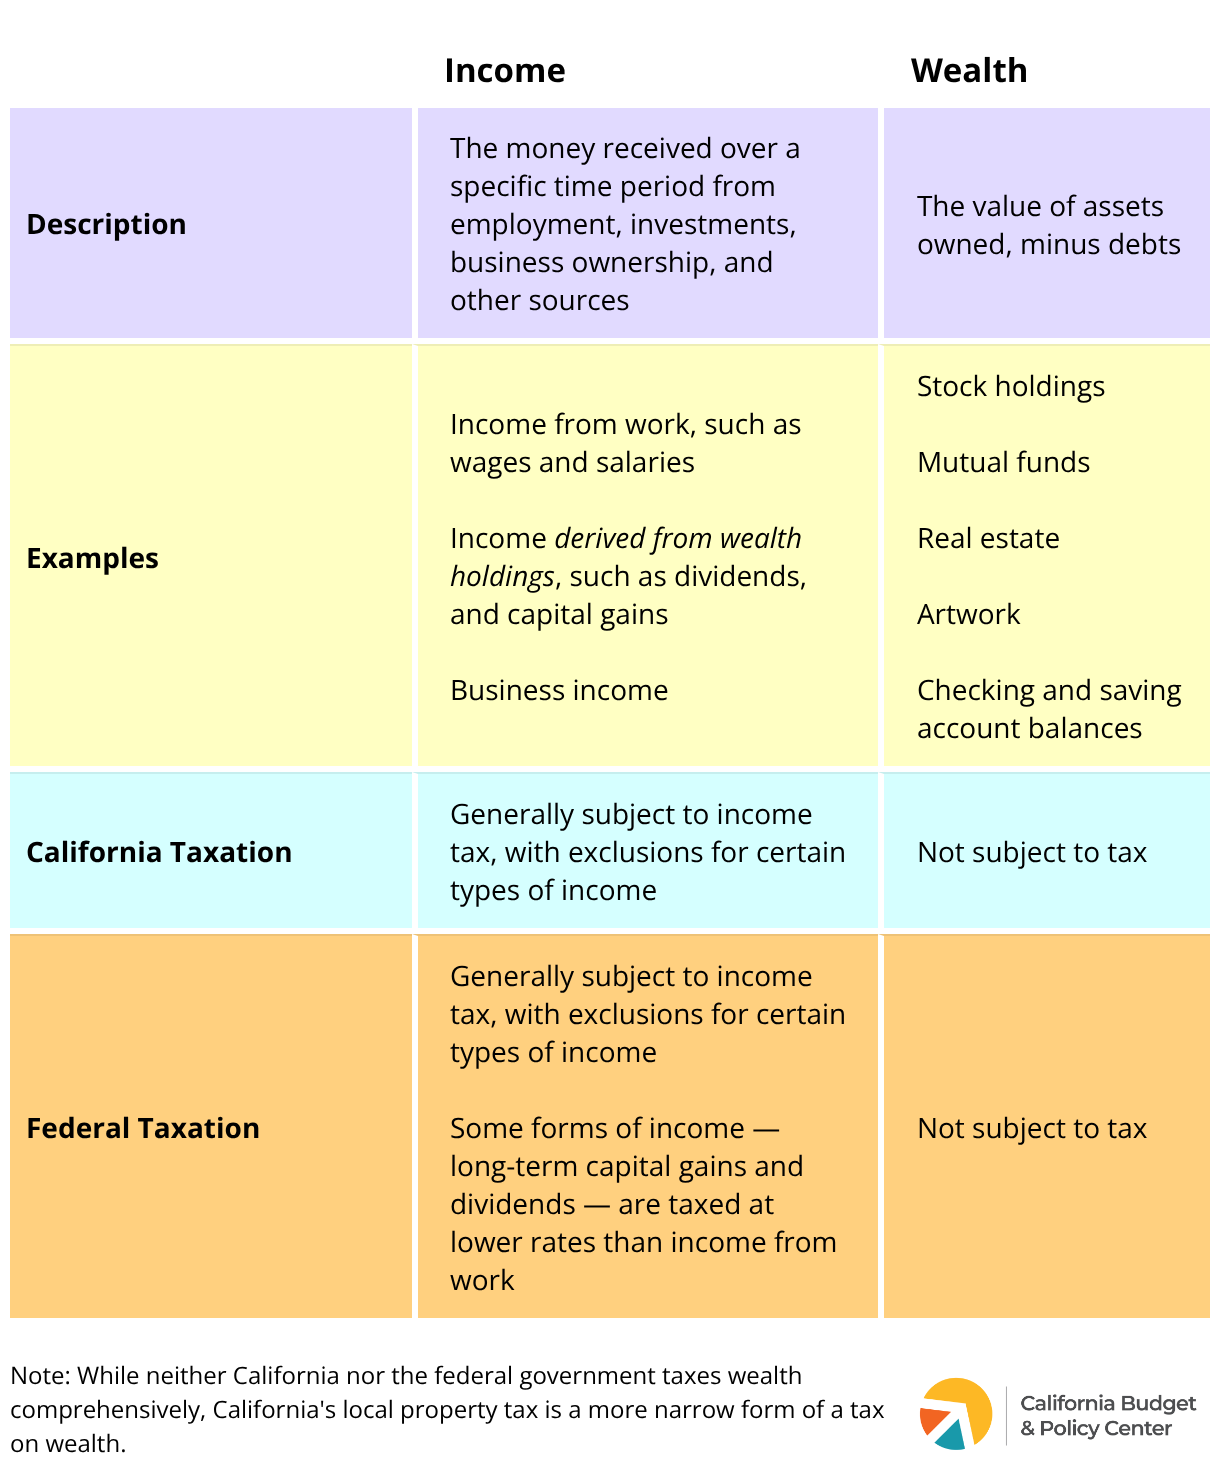
Current federal and state tax policies allow some large wealth increases to never be taxed. California — like the federal government — only taxes the income people receive when they sell their assets, but does not tax the growth in value of assets they hold onto. This growth is known as an unrealized capital gain, and for very wealthy households, unrealized capital gains make up a large share of their total wealth. Some wealthy people may even be able to avoid paying income taxes entirely in some years by not taking a salary, not selling any stocks or other assets, and simply borrowing against their wealth to pay their bills.
Additionally, if someone holds onto assets until their death, their heirs do not have to pay any tax on the gain due to a provision in both federal and state law known as “stepped-up basis,” estimated to cost California around $5 billion each year.
For these reasons, broadly prohibiting state leaders from enacting any new taxes on assets would narrow the options available to ensure that the wealthiest Californians pay their fair share to support the services that benefit residents across the state.
Impacts of Prohibition on Retroactive Taxes
Many federal and state tax law changes have modest retroactivity periods, such as looking back to the beginning of a tax year. This has the benefit of reducing taxpayers’ ability to engage in activities to avoid or evade the tax before it goes into effect, which would reduce the revenue potential. Looking back to the start of the current tax year can also more immediately raise revenues when there are urgent needs.
Broadly prohibiting retroactive taxation would hamstring the ability of state leaders to enact effective and timely tax policy changes that raise revenues needed to meet the needs of Californians.
Who Supports and Opposes Prop. 42?
The top contributor to the Prop. 41 campaign is a group called “Building a Better California,” which is largely funded by Google cofounder Sergey Brin and other billionaires. This group is also opposing Prop. 40 and supporting Prop. 41. The measure is also endorsed by the California Republican Party, the California Chamber of Commerce, the California Taxpayers Association, the California Professional Firefighters, and the State Building & Construction Trades Council of California.
There is no official opposition campaign for Prop. 41, but prominent opponents include the Service Employees International Union – United Health Workers West (SEIU-UHW) — the main proponent of the Prop. 40 billionaire tax measure — as well as other labor groups including the California Federation of Teachers and the California Federation of Labor Unions. The California Democratic Party and the League of Women Voters are also opposed.
Curious About Other Ballot Propositions?
Browse our collection of resources covering California’s statewide ballot measures to help you understand what’s at stake for California this November.
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
key takeaway
Prop. 41 would 1) impose new audit requirements for programs funded with state special taxes and 2) prohibit the collection of new state taxes that are excluded from the state’s spending limit. The primary intent of the measure is to invalidate Prop. 40 — the billionaire tax also appearing on the November ballot — but Prop. 41 could also make it harder for the state to meet the needs of Californians in the future.
What Would Prop. 41 Do?
Prop. 41 would amend the state Constitution to impose new rules related to state taxes. The measure would require “financial and performance audits” of programs receiving revenues from special taxes and would also prevent state taxes from being excluded from California’s spending cap, also known as the “Gann Limit.”
Creates New Audit Requirements for Special Taxes
Prop. 41 would create new pre-election and ongoing audit requirements for programs receiving — or proposed to receive — revenues from state-level special taxes. In contrast to a general tax, which can be used for any purpose, a special tax raises revenue for specific purposes.
Pre-election audits: The State Auditor would be required to perform an audit of any program that would be funded by a special tax proposed through a statewide voter initiative. The audit would be required while the initiative is being circulated for signatures — before it officially qualifies for the ballot — and a summary of the audit findings would be included in the voter information guide. The full audit would also be made available to the public.
Ongoing audits: The State Auditor would be required to audit programs receiving revenues from special taxes enacted by the Legislature or approved by voters through a statewide initiative on or after January 1, 2026. These audits would be required every four years.
The audits would assess programs based on specific criteria outlined in Prop. 41, and would require the State Auditor to recommend how programs could reduce costs by at least 10% annually.
The State Auditor would be reimbursed for the costs of these audits with revenues from the relevant special tax. If, however, a special tax initiative fails to qualify for the ballot or is rejected by voters, the audit costs would be absorbed by the state’s General Fund.
Prohibits Taxes That Are Excluded from the State Spending Limit
Prop. 41 would prevent the state from collecting or enforcing any state tax that is 1) enacted on or after January 1, 2026 and 2) excluded from the state spending cap, also known as the Gann Limit. Currently, the measure would apply only to Prop. 40 if both measures pass and Prop. 41 receives more votes, but it could potentially be applied to other tax policy proposals in the future.
California’s spending limit was established by Prop. 4 (1979) and is based on state spending in 1978-79, annually adjusted for population changes and inflation. Under the state Constitution, if state revenues exceed the limit over two consecutive years, the excess must be split equally between refunds to taxpayers and spending on TK-14 education. In effect, the spending limit restricts the ability of state leaders to raise and spend revenue to meet the most pressing needs of Californians.
Conflicts with Other Measures on the Ballot
The California Constitution states that if provisions of multiple measures on the same ballot conflict, the provisions of the measure receiving the higher number of votes will prevail. Prop. 41 broadly specifies that if another measure on the same ballot either 1) imposes different audit rules on special taxes or 2) contains a tax that is exempted from the state spending limit, the entirety of the other measure would be invalidated if Prop. 41 receives more votes.
Prop. 41 is in direct conflict with Prop. 40. This is because Prop. 40 would create a one-time tax on the wealth of billionaires and exclude the revenues from the state spending limit, which Prop. 41 prohibits.
If both measures were to be approved and Prop. 41 received more votes, Prop. 40 could be invalidated. Alternatively, if both measures pass but Prop. 40 receives more votes, the billionaire tax could be collected, but it is possible that audits would be required of Medi-Cal and other programs receiving Prop. 40 dollars. If both measures pass, there may be litigation regarding the application of conflicting provisions, and the final decision would be made by the courts.
How Would Prop. 41 Affect Californians and the State Budget?
The primary intent of Prop. 41 is to invalidate the Prop. 40 billionaire tax, but it would also create new barriers to raising state revenue and effectively meeting the needs of Californians.
Prop. 41 would also increase state costs related to conducting audits for programs that are often already subject to close scrutiny — reducing funding available to support critical state services. This would come at a time when Californians are already dealing with affordability concerns as well as the consequences of the steep federal cuts to health care and food assistance enacted in H.R. 1, signed by President Trump in 2025.
Impacts of Audit Requirements
The pre-election audit requirement could dissuade voters from approving special tax initiatives that would raise needed revenue to support and improve state services that help Californians stay healthy, housed, and economically secure. A summary of the audit would appear in the voter guide, and voters could interpret it as evidence that the programs to be funded are inefficient or ineffective. For example, because the State Auditor would be required to recommend options to cut program costs by 10%, voters may assume this means the program is inefficient even if that is not the case.
Additionally, the requirement for cost-cutting recommendations could result in service cuts with real human impacts. While policymakers would be under no obligation to implement these recommendations, if they did it could result in cuts to core services rather than simply “inefficient spending.” For example, if a program receiving special tax revenues is already operating efficiently but the Auditor must identify ways that costs could be reduced by 10%, lawmakers may be under pressure to adopt those recommendations — particularly in difficult budget times. Those cuts could lead to fewer Californians being served, reductions in benefit levels, or decreased service quality.
While it is clearly important for tax dollars to be spent efficiently and effectively, many state programs are already subject to occasional or ongoing audits. The State Auditor currently performs audits as a result of existing state laws, legislative requests, and whistleblower tips. Additionally, the “High-Risk” audit program requires the Auditor to periodically review programs or agencies determined to be at high risk for “waste, fraud, abuse, or mismanagement” or those raising concerns related to efficiency or effectiveness.
Prop. 41’s additional audits would increase state costs, reducing the resources available to directly support services for Californians. Moreover, in the case of program audits related to a proposed special tax, the audit costs would be absorbed by the state’s General Fund if the ballot initiative were not enacted, leaving less funding for critical state services like education, health care, and human services.
Impacts of State Spending Limit Provisions
The primary impact of preventing new revenues from being excluded from the spending limit would be the invalidation of the billionaire tax proposed by Prop. 40 — if both measures pass and Prop. 41 receives more votes.
In the future, voters may be able to exclude the revenues from a statewide tax initiative from the spending cap if the initiative amends the Constitution to do so. In fact, previous initiatives have explicitly excluded new tax revenues from the limit, such as tobacco taxes enacted under Prop. 10 (1998) and Prop. 56 (2016). However, legal challenges are possible and there is no certainty on how courts would rule.
State policymakers already lack the authority to exclude new tax revenues from the spending cap without voter approval because the cap is enshrined in the state Constitution.
There are some existing state revenue streams that could potentially be affected by Prop. 41, but there are many complications and uncertainties and any conflicts would ultimately be decided by the courts. For example, some health care financing sources that must be occasionally reauthorized — such as the Managed Care Organization (MCO) tax and the Hospital Quality Assurance fee, which both allow the state to draw down additional federal funding for Medi-Cal — could potentially be impacted by Prop. 41. This, in turn, would jeopardize billions of dollars in federal funding for Medi-Cal at a time when Californians are already experiencing the harms of the deep federal cuts to health care resulting from H.R. 1.
Who Supports and Opposes Prop. 41?
The top contributor to the Prop. 41 campaign is a group called “Building a Better California,” which is largely funded by Google cofounder Sergey Brin and other billionaires. This same group is also opposing Prop. 40 and supporting Prop. 42. Prop. 41 is also endorsed by the California Republican Party, the California Chamber of Commerce, and the California Taxpayers Association.
There is no official campaign against Prop. 41. However, prominent opponents include the Service Employees International Union – United Health Workers West (SEIU–UHW) — the main proponent of the Prop. 40 billionaire tax measure — as well as other labor groups including the California Federation of Teachers and the California Federation of Labor Unions. The California Democratic Party and the League of Women Voters also oppose Prop. 41.
Curious About Other Ballot Propositions?
Browse our collection of resources covering California’s statewide ballot measures to help you understand what’s at stake for California this November.
SACRAMENTO, CA — Statement from Chris Hoene, executive director of the California Budget & Policy Center (Budget Center), a nonpartisan research and analysis nonprofit on the film tax credit and related provisions: “The film industry asked lawmakers to exempt all of its tax credits from the reasonable caps the state places on business tax breaks. … Continued
key takeaway
Proposition 43 on the November ballot would require that at least two-thirds of local voters approve any local initiative that would create, extend, or increase a special tax, starting on January 1, 2027. As communities across California are facing substantial challenges and uncertainties, this measure would make it harder for local voters to raise revenues to support local public services and give outsized power to a small share of voters. Approval of the measure would decrease the likelihood that local governments meet the needs of their residents and could increase hardship in some communities throughout the state.
This measure would require at least two-thirds of local voters to approve any local initiative that would create, extend, or increase a special tax. The measure would apply to initiatives placed on a local ballot on or after January 1, 2027.
This new supermajority vote requirement would apply to special tax voter initiatives raising revenue for many types of local governments, including cities, counties, special districts, and other local or regional government entity.1Under California’s Constitution, all taxes levied by special districts are considered “special taxes,” so Prop. 43’s two-thirds vote requirement would apply to any taxes placed on the ballot by voters to generate revenues for special districts as well as city and county taxes for dedicated purposes.
A tax that is levied by a city or county and that may be spent on any program or service. All non-property taxes that cities and counties may levy can be imposed as general taxes. A general tax may be approved by a simple majority of local voters, regardless of whether it is placed on the ballot by the local government entity or by a local voter initiative.
Local voter initiative process
Gives residents of a city or a county the power to propose changes to local ordinances. This process involves a number of steps, including drafting a ballot measure, circulating petitions, and gathering the required signatures.
Parcel tax
A tax on a parcel of property that is not based on the property value. This tax is generally levied at a flat rate per parcel, but can also be levied on a per-square-foot or per-room basis. Parcel taxes can be levied by cities, counties, school districts, community college districts, and most special districts. Parcel taxes are always considered to be special taxes for the purpose of determining voter-approval requirements.
Simple majority vote
A requirement that a state or local ballot measure receive support from at least half of voters plus one additional voter (50%+1) in order to be approved.
Special tax
Includes1) parcel taxes, 2) city or county taxes (excluding property taxes) dedicated to specific purposes, and 3) taxes (excluding property taxes) levied by special purpose districts — that is, special districts, K-12 school districts, and community college districts.
Supermajority vote
A requirement that a state or local ballot measure receive more than a simple majority vote, such as three-fifths or two-thirds, in order to be approved.
What Are the Current Vote Requirements for Local Revenue Increases in California?
California’s Constitution has a complex set of rules governing how local governments can raise taxes and other types of revenue. These rules were put in place by statewide ballot measures over the past several decades, beginning with Prop. 13 in 1978 and followed by other measures creating additional restrictions on local revenue-raising capacity, including Prop. 62 (1986) and Prop. 218 (1996).
These rules apply to local measures to create new taxes as well as to increase or extend any existing tax.
Tax measures proposed by local governments — such as city councils or county boards of supervisors — must go on the ballot and be approved by voters. Current voter-approval thresholds differ depending on the type of tax that would be raised:
A general tax requires only a simple majority vote to pass, with the revenue available for any program or service.
A special tax requires a two-thirds vote to pass, and includes a tax dedicated to a specific purpose.
Special taxes proposed through the local voter initiative process are subject to different rules. In recent years, a series of court decisions have clarified that the two-thirds vote requirement for special taxes in the state Constitution does not apply to special tax measures placed on the ballot by local voter initiative. Therefore, both general taxes and special taxes proposed by voters can be approved with a simple majority vote.2Several cases involving special tax voter initiatives that were approved with a simple majority vote were appealed to the California Supreme Court, but the Supreme Court denied review of the appellate court decisions, allowing these decisions to stand. A variety of special tax initiatives have been approved over the past several years with a simple majority vote, such as:
San Francisco’s Measure C in November 2018, creating a tax on commercial landlords to raise funds for child care and early education, which passed with 51% of the vote.
Fresno’s Measure P in November 2018, increasing the local sales tax rate to fund community parks, which passed with 52% of the vote.
Los Angeles’ Measure ULA in November 2022, creating a property transfer tax on sales of high-value property to raise funds for affordable housing development and homelessness service, which passed with 58% of the vote.
Madera County’s Measure T in November 2024, renewing a local sales tax rate to fund transportation projects, which passed with 52% of the vote.
Certain types of local taxes are always classified as special taxes for the purposes of voter approval requirements. This includes:
Taxes levied by special-purpose districts, including school districts, community college districts, and special districts.
Parcel taxes, which are taxes on parcels of property that are not based on the property value. These taxes are generally levied at a flat rate per parcel, but can also be levied on a per-square foot or per-room basis.
What Services Do Local Governments in California Provide?
Californians in every community across the state benefit from services provided by local governments. Local services help keep people safe and healthy by providing fire protection, law enforcement, public health services, hospitals and emergency services, road safety, and more. Local governments also provide educational and recreational spaces like public libraries, public parks, and playgrounds.
Californians experiencing economic insecurity, food security, or who don’t have access to private health insurance can access financial assistance, food assistance, and health care because counties are there to administer public health and economic security programs. Cities can support the development of affordable housing to ensure more of their residents can afford a safe place to live.
Counties administer health and human services programs such asMedi-Cal health coverage, CalFresh food assistance, and CalWORKs cash assistance for families. Counties also provide public health, behavioral health, and child welfare services. Additionally, counties are responsible for overseeing the local justice system and courts, administering elections, and providing municipal services like sewer systems and trash pick-up in unincorporated areas.
Cities provide a variety of municipal services such as fire protection, housing and urban planning, parks and recreation, libraries, street repair, water and sewer systems, and law enforcement — although some of these services may be provided by special districts in some areas.
Special districts provide specialized services such as fire protection, water, electricity, parks and recreation, transit, hospitals, and other health care services.
Regional entities such as Joint Powers Authorities and Councils of Government coordinate policy and service provision across regions spanning multiple cities or counties, such as regional transportation authorities.
How Do Local Governments Raise Revenue?
Local governments in California rely on a variety of revenue sources, including transfers from the state and federal governments, allocations of local property taxes, and various other taxes, service charges, assessments, and fees.
Most types of local governments receive some revenues from the local property tax, capped at 1% by Prop. 13 (1978). Property taxes are collected by counties and the revenues are allocated to support city and county governments, school districts, community college districts, and special districts in accordance with formulas established in state law. Local governments and voters cannot increase property taxes beyond the 1% rate, except to finance infrastructure bonds.3Property tax increases to support school infrastructure bonds can generally be approved by 55% of local voters. All other property taxes for infrastructure bonds must be approved by two-thirds of voters.
Curious About Other Ballot Propositions?
Browse our collection of resources covering California’s statewide ballot measures to help you understand what’s at stake for California this November.
Other common types of taxes supporting local services include sales taxes (known as transactions and use taxes at the local level), taxes on hotel stays (known as transient occupancy taxes), property transfer taxes, utility user taxes, and business license taxes.
The revenues that make up local government budgets vary by the type of entity, and the legal authority to raise taxes also differs by government type. Cities and counties have fairly broad authority to raise a variety of taxes — with voter approval — while special districts have more limited authority. These districts are largely limited to parcel taxes — a tax on parcels of land not based on their value — as a source of discretionary revenue, although some can levy district sales taxes and certain other types of taxes.
More than half of county-level revenues statewide come from the state and federal governments and local property taxes. Other types of taxes make up a small share of total county revenues — generally less than 3%. Common types of taxes levied by counties include sales taxes, property transfer taxes, taxes on hotel stays, and utility user taxes.
City-level revenues primarily come from service charges for municipal functions — such as electricity, water, and sewer services — and various taxes. These two categories generally each make up around one-third of total city revenues statewide. Local property tax revenues and sales taxes are the largest sources of tax revenues for cities, each representing about one-quarter of tax revenues. Other major tax revenue sources for cities include taxes on hotel stays, utility user taxes, and business license taxes.
Special district revenues come largely from customer service charges for the service provided by the district, local property taxes, and certain other taxes and assessments, depending on the type of district.4The composition of special district revenues depends on the type of special district. Enterprise districts provide services to customers for a charge and operate similar to businesses, being largely financed by user charges. Examples of enterprise districts include health care districts, airport districts, water districts, and other utility districts. Non-enterprise districts provide benefits to entire communities — such as fire protection and road repair services — and are primarily funded by property taxes and other types of taxes and assessments. As noted above, taxes levied by special districts are always considered special taxes so they require approval of two-thirds of voters in the district, unless they are placed on the ballot by voters.
How Would Proposition 43 Affect California Communities?
Proposition 43 Would Make It More Difficult for Communities to Generate Revenues to Meet Local Needs
California already imposes high barriers to raising local revenues by requiring all special taxes levied by local governments to be approved by two-thirds of voters instead of a simple majority, and by classifying certain types of taxes — parcel taxes and taxes levied by special districts and school districts — as special taxes subject to higher vote requirements. Extending the two-thirds vote requirement to voter-initiated special tax proposals, as Prop. 43 proposes, would decrease the likelihood that these measures would pass, even if a significant majority of local voters support the measure and the services that the new revenues would fund.
In contrast to the high bar for raising taxes, local governments do not need voter approvalto reduce services— and cuts to services often result when localities face revenue shortfalls. Yet, communities also have the option of raising revenues to help close budget gaps. If Prop. 43 passes, counties and cities would still have the ability to raise general taxes with approval from a simple majority of voters to shore up local services. However, local voters’ ability to propose new special taxes to protect or strengthen key services would be limited as local voter initiatives would become much more challenging to pass. Additionally, voters in special districts would face a higher bar to increase revenues to preserve and expand services, regardless of whether the funds would be targeted to specific programs.
Proposition 43’s Constraints on Local Revenues Would Make Things Harder for Communities Already Struggling
Governments across the board have felt the impacts of inflation on the costs of providing public services, and the state’s aging population increasing the cost of providing some services such as health care. The impacts of the 2025 federal budget reconciliation law, H.R. 1 — also known as the “One Big Beautiful Bill Act” — along with the effects of climate change, the labor market and broader economic impacts of arrests and deportations of immigrants, and other federal policy changes such as tariffs, are also creating challenges for localities.
H.R. 1 will deeply harm Californians by cutting funding for essential health care and food assistance programs, primarily Medi-Cal and CalFresh, pushing more people into poverty and widening racial and economic inequities across the state. This is already increasing the level of need in communities as people lose health coverage and food assistance benefits while increasing costs for some local governments. The pressures on local governments will continue to increase substantially in the coming years as additional H.R. 1 policies go into effect.
Counties
Counties will be the most impacted by H.R. 1 and will see higher costs due to a combination of direct funding reductions and cost shifts, workload increases, and increases in uninsured individuals seeking basic care at county hospitals, which counties are legally required to provide. In addition to the direct impacts of H.R. 1, the increase in hardship created by the federal cuts will likely increase the demand for other county services such as housing and homelessness supports, and counties will have difficulty meeting this demand with less funding.
Local Health Districts
Local health care districts — a type of special district that can provide hospital care, ambulance services, health clinics, skilled nursing facilities, and other health-related services — will likely also be strained as individuals lose health coverage. Many of these districts are located in rural or underserved areas.
Public Hospitals
Many California public hospitals — including those operated by counties and local health care districts — have already been facing financial strain in recent years, particularly rural hospitals and others that serve high shares of patients with coverage through Medi-Cal and or Medicare. H.R. 1’s Medi-Cal cuts will compound these challenges. Nationwide, there are concerns about how rural hospitals and clinics will stay afloat as the cuts continue to go into effect. If health care providers cut services or close down, many individuals in those communities would be left without adequate health care.
Cities
While cities will be less directly impacted by H.R. 1, the federal law did rescind some funding related to transportation and climate-related programs. In addition, cities will likely be impacted by some downstream effects of the health care and food assistance cuts. For example, local economies may be impacted by the strains on household budgets, and the need for city services such as affordable housing and homelessness services may increase as more residents are faced with the choice between paying for food and medical care or paying rent.
These challenges would come on top of existing financial pressures such as increasingly frequent climate disasters (such as the devastating January 2025 Los Angeles wildfires) and the increasing cost of providing city services due to inflation and other factors, including rising health care costs driving up expenses for health benefits for city workers and retirees.
Proposition 43 Would Give Disproportionate Power to a Small Share of Voters
Supermajority vote requirements allow a small share of voters to block policies favored by a large majority of voters. For example, Prop. 43 would allow 35% of local voters to block an initiative that 65% of voters support. In other words, a minority of voters could prevent the community from raising revenues to support services that the vast majority of community members say are needed.
Proposition 43 Would Allow Statewide Voters to Restrict Local Control to Raise Revenue
Statewide ballot measures require just a simple majority vote to pass, even if the measure proposes to amend the state Constitution. Prop. 43 would allow a bare majority of statewide voters to impose a supermajority vote requirement on local voters, limiting the ability of local voters to raise revenues to fund public services — even though different communities in the state have different needs and preferences.
Proposition 43 Supporters and Opponents
Prop. 43 is supported by the Howard Jarvis Taxpayers Association and Reform California, a political action committee headed by State Assemblymember Carl DeMaio. It is opposed by Evolve California, a grassroots organization focused on public education funding and Prop. 13 reform, and State Assemblymember Buffy Wicks.
The California Budget & Policy Center is a nonpartisan research and analysis nonprofit and does not endorse or oppose ballot measures. This analysis reflects the institutional position of the Budget Center, developed and reviewed by our policy leadership team.
Kayla Kitson and Scott Graves contributed to this publication.
Under California’s Constitution, all taxes levied by special districts are considered “special taxes,” so Prop. 43’s two-thirds vote requirement would apply to any taxes placed on the ballot by voters to generate revenues for special districts as well as city and county taxes for dedicated purposes. ↩︎
2
Several cases involving special tax voter initiatives that were approved with a simple majority vote were appealed to the California Supreme Court, but the Supreme Court denied review of the appellate court decisions, allowing these decisions to stand. ↩︎
3
Property tax increases to support school infrastructure bonds can generally be approved by 55% of local voters. All other property taxes for infrastructure bonds must be approved by two-thirds of voters. ↩︎
4
The composition of special district revenues depends on the type of special district. Enterprise districts provide services to customers for a charge and operate similar to businesses, being largely financed by user charges. Examples of enterprise districts include health care districts, airport districts, water districts, and other utility districts. Non-enterprise districts provide benefits to entire communities — such as fire protection and road repair services — and are primarily funded by property taxes and other types of taxes and assessments. ↩︎
You may also be interested in the following resources:
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
key takeaway
Prop. 40 would institute a one-time 5% tax on the wealth of billionaires to raise tens of billions in temporary revenue to address the loss of federal funding and other threats to health, nutrition, and education services, largely a result of H.R. 1 — the 2025 budget reconciliation law known as the “One Big Beautiful Bill Act.” Prop. 40 could potentially raise tens of billions in revenue in the short-term to preserve critical services, but may also lead to some income tax revenue losses in future years to the extent that billionaires leave the state to avoid the tax.
California, like many other states, is facing a number of challenges to its ability to meet the needs of its residents, including the impending impacts of the deep federal cuts to public health care and nutrition assistance and the rising costs of providing services due to inflation, an aging population with more complex needs, and the state’s ongoing housing crisis. The federal cuts to Medi-Cal alone are expected to cost the state tens of billions of dollars in lost funding and could lead to around 1.3 million Californians losing health care access by 2029-30. Meaningfully addressing these challenges will require California to raise a substantial amount of revenue.
what is h.r. 1?
H.R. 1, the 2025 budget reconciliation law known as the “One Big Beautiful Bill Act,” signed by President Trump on July 4, 2025, will deeply harm Californians by cutting funding for essential health care and food assistance programs — while providing massive tax breaks to the wealthy and corporations. The spending cuts will disproportionately impact families with low incomes, immigrants, and communities of color, pushing more people into poverty and widening racial and economic inequities across the state.
Even prior to these more recent challenges, California was not generating enough revenue to meet the critical needs of all Californians through the state’s communities, evidenced by the state’s poverty rate remaining the highest in the nation. In addition to the human suffering caused by failing to ensure Californians can regularly access health care, put enough food on the table, and meet their other basic needs, such a failure dampens the state economy by preventing some individuals from fully participating in it and puts fiscal pressures on state and local governments as more households are forced to turn to costly emergency services and systems of last resort.
In the near term, Prop. 40 would likely generate tens of billions in revenue to prevent health coverage losses for Californians and stabilize the state’s health care system, and could provide additional support for nutrition assistance — which is also impacted by federal cuts — and for public education. Because the revenues would be one-time, the state would not be able to maintain these services in the future unless federal funding were fully restored or the state adopted alternative sources to raise this magnitude of revenue.
There is a strong rationale for taxing accumulated wealth — or taxing increases in wealth that currently go untaxed — given the profound wealth inequality and the vast unmet needs that exist in the state and across the country, as well as the ability of some ultrawealthy households to pay very little in income taxes as a share of their wealth.
At the same time, taxing wealth at the state level comes with some risks, particularly the potential for wealthy people to leave the state to avoid the tax, which would result in future state income tax losses if they did not return — putting at risk future funding for critical state services — and potential unknown impacts on the state economy. Prop. 40 attempts to counter that risk by applying the tax to billionaires who were California residents at the beginning of 2026, however it is likely this will be challenged in courts and the outcome is not certain.
In November, California voters will need to weigh the potential benefits of Prop. 40 against its potential tradeoffs.
Who Would Be Subject to the Tax Under Prop. 40 and How Would It Be Calculated?
Prop. 40 would institute a one-time tax on the worldwide wealth of billionaires. For the purposes of the measure, a billionaire subject to the tax could be an individual, a married couple, or a trust with net worth — as defined by the measure — above $1 billion. There are around 250 billionaires in California, with over $2 trillion in total wealth.1Forbes tracks the daily wealth of billionaires with its “Real-Time Billionaires” list, and the California-specific data was compiled in connection with Jasper Boll, Emmanuel Saez, and Gabriel Zucman, California Billionaires: Wealth, Taxes, and Wealth Tax Revenue Estimates (NBER Working Paper 35218, May 2026). Note: Saez is an author of Prop. 40.
The tax rate would be 5% for most billionaires, but the rate would be phased in for those with net worth between $1 billion and $1.1 billion.2Specifically, the 5% rate would be reduced by 0.1 percentage point for each $2 million that the household’s net worth falls below $1.1 billion. Taxpayers would have the option of paying the full amount of the tax with their 2026 tax returns or in installments across five years, with an annual deferral charge.
Net worth is typically calculated as the total value of assets held by an individual, couple, or family minus their total debts. However, Prop. 40 allows some exclusions from the net worth calculation, including:
Real property holdings, which are subject to constitutional tax limitations due to Proposition 13, approved by California voters in 1978;
Tangible personal property — such as vehicles, jewelry, appliances, or business equipment — held outside of California;3Tangible personal property is excluded from the net worth calculation if it is held outside of California for at least 270 days during 2026 unless it was temporarily relocated for the purpose of tax avoidance. and
Certain pensions, retirement accounts, and deferred compensation arrangements.
The measure would apply the tax to billionaires who were California residents on January 1, 2026, and the amounts subject to the tax would be determined based on their net worth on December 31, 2026. There will likely be legal challenges to the application of the tax based on residency prior to the enactment of the tax. Federal and state tax measures often have retroactivity provisions to minimize tax avoidance and courts have upheld many of these laws, although it is unknown how courts would ultimately rule on this measure. The measure specifies that in the case the residency and valuation dates are invalidated by courts, these dates shall be construed to be the earliest dates consistent with law.
Prop. 40 establishes procedures for estimating the value of various types of assets that would be included in net worth for the purpose of the tax. Valuation is simple for some assets, such as holdings of publicly traded stock, which have a known market value at any given time. Other assets, such as shares of private businesses, intellectual property such as copyrights or trademarks, and artwork, are more difficult to value without a sale taking place. The measure has detailed valuation rules and formulas for different types of assets, and both the taxpayer and the state’s Franchise Tax Board — which would be responsible for administering the tax — could obtain certified appraisals in the case of valuation disputes. Additionally, the measure contains provisions intended to minimize the ability of taxpayers to avoid or evade their tax responsibility.4Tax avoidance reflects legal avenues to reducing tax liability, such as redirecting wealth holdings to exempted assets or relocating, whereas tax evasion encompasses illegal tactics to avoid taxes, such as hiding assets in tax havens, underreporting of asset values, or falsely claiming residency outside of the tax jurisdiction.
Example: Potential Impact of Prop. 40 on Mark Zuckerberg
Mark Zuckerberg, cofounder of Facebook, has a net worth of around $200 billion. Assuming he has approximately $200 billion in wealth subject to Prop. 40 on December 31, 2026, when net worth is to be determined for the purpose of the measure, he would owe around $10 billion in tax, which he could pay in five annual installments of $2 billion. His remaining wealth of around $190 billion would still be more than the entire economies of dozens of countries, roughly on par with the Gross Domestic Product of Morocco.
For comparison, Zuckerberg’s net worth increased 175% from 2023 to 2024 according to Forbes data, from $64.4 billion to $177 billion.
What Is the Difference Between Income and Wealth?
Capital Gains: Increases in Wealth
Households holding assets that have increased in value pay federal and state tax on those gains only when they sell those assets. This is known as a realized capital gain.
However, the value of an asset can grow exponentially and go untaxed as long as it is held onto — an unrealized capital gain. While the household doesn’t directly receive the proceeds from the gain until selling the asset, unrealized capital gains represent an increase in the household’s wealth and financial well-being.
For ultra-wealthy households, unrealized capital gains make up a large share of their total wealth.5For example, the Institute on Taxation and Economic Policy estimated that unrealized capital gains represent nearly 70% of total wealth for billionaires. In some cases, ultra-wealthy households — such as corporate founders — can avoid paying income taxes entirely in some years by not taking a salary, not selling any stocks or other assets, and simply borrowing against their wealth to pay their bills. There is evidence of some of the wealthiest Americans engaging in this behavior, detailed in analyses of leaked tax returns by investigative journalists,although recent research suggests that this is not a widespread phenomenon and that overall, wealthy households do have significant taxable income and their incomes allow them to cover their expenses while continuing to invest and grow their wealth.
Additionally, if someone holds onto assets until their death, their heirs do not have to pay any tax on the gain due to a provision in both federal and state law known as “stepped-up basis,” estimated to cost California around $5 billion each year.6Department of Finance, Tax Expenditure Report: 2025-26, p. 24. Note that the estimated annual cost of the provision is not equivalent to the revenue that could be generated from repealing it, and for this provision the revenue gains from repeal would start in the low hundreds of millions and increase with time, potentially reaching $5 billion annually in the future. Essentially, the combination of unrealized capital gains not being taxed and stepped-up basis results in some large wealth increases never being taxed.
How Is Wealth Distributed Across California?
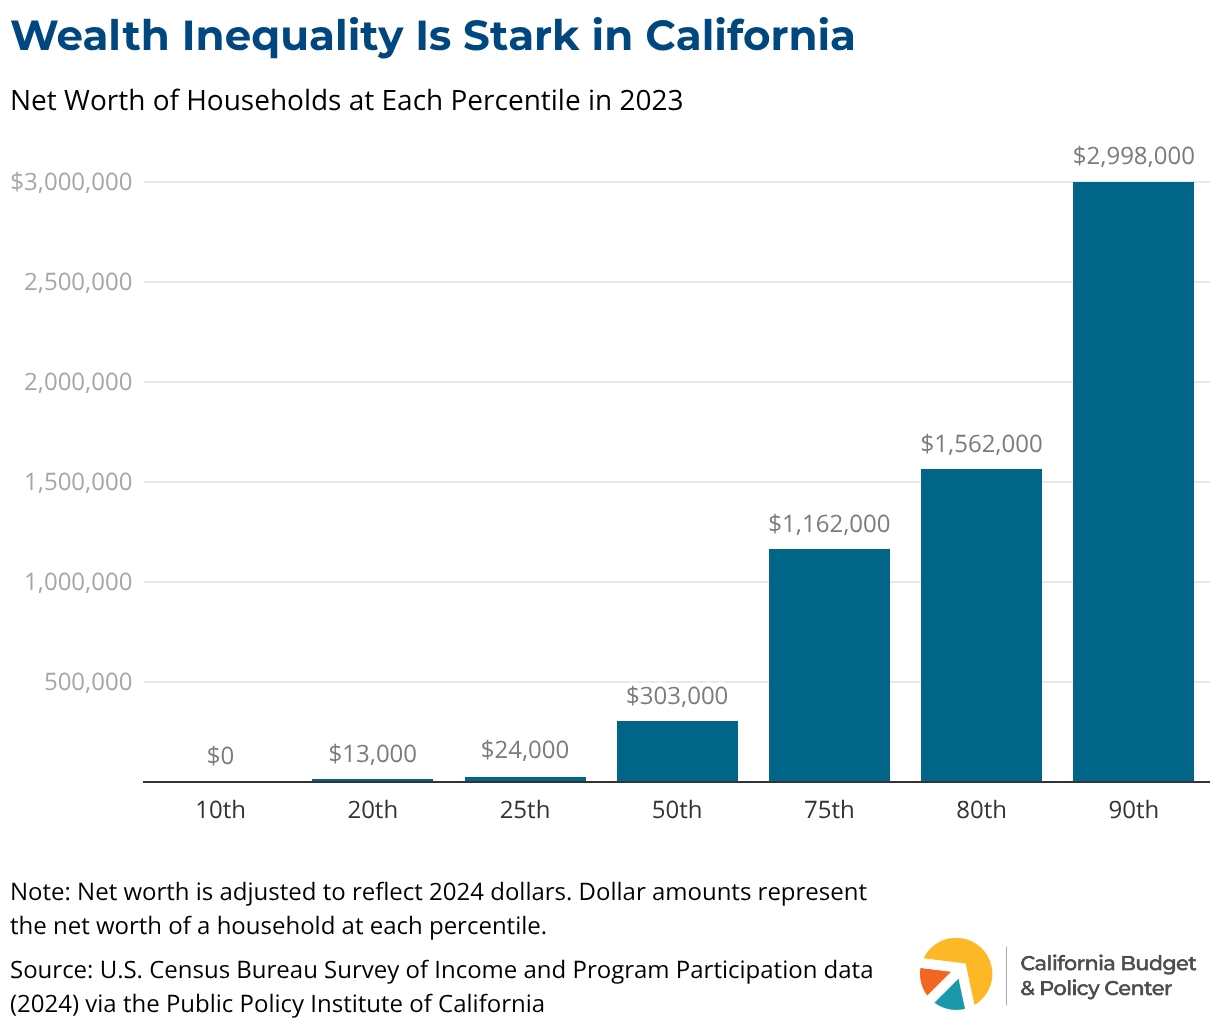
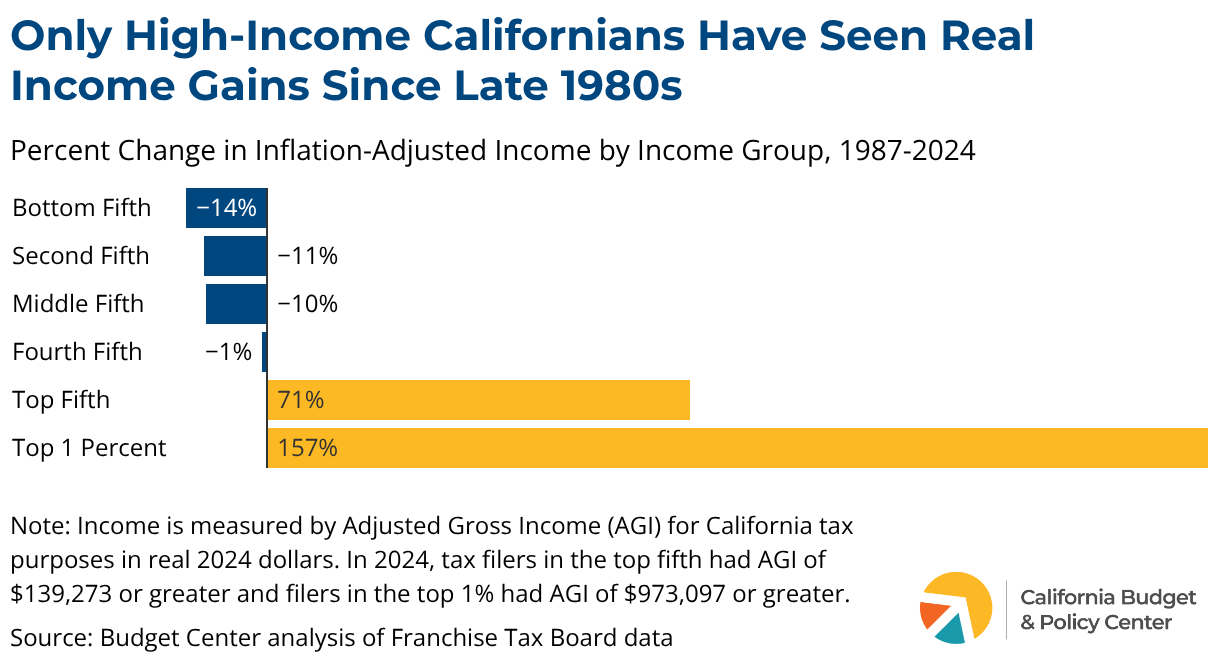
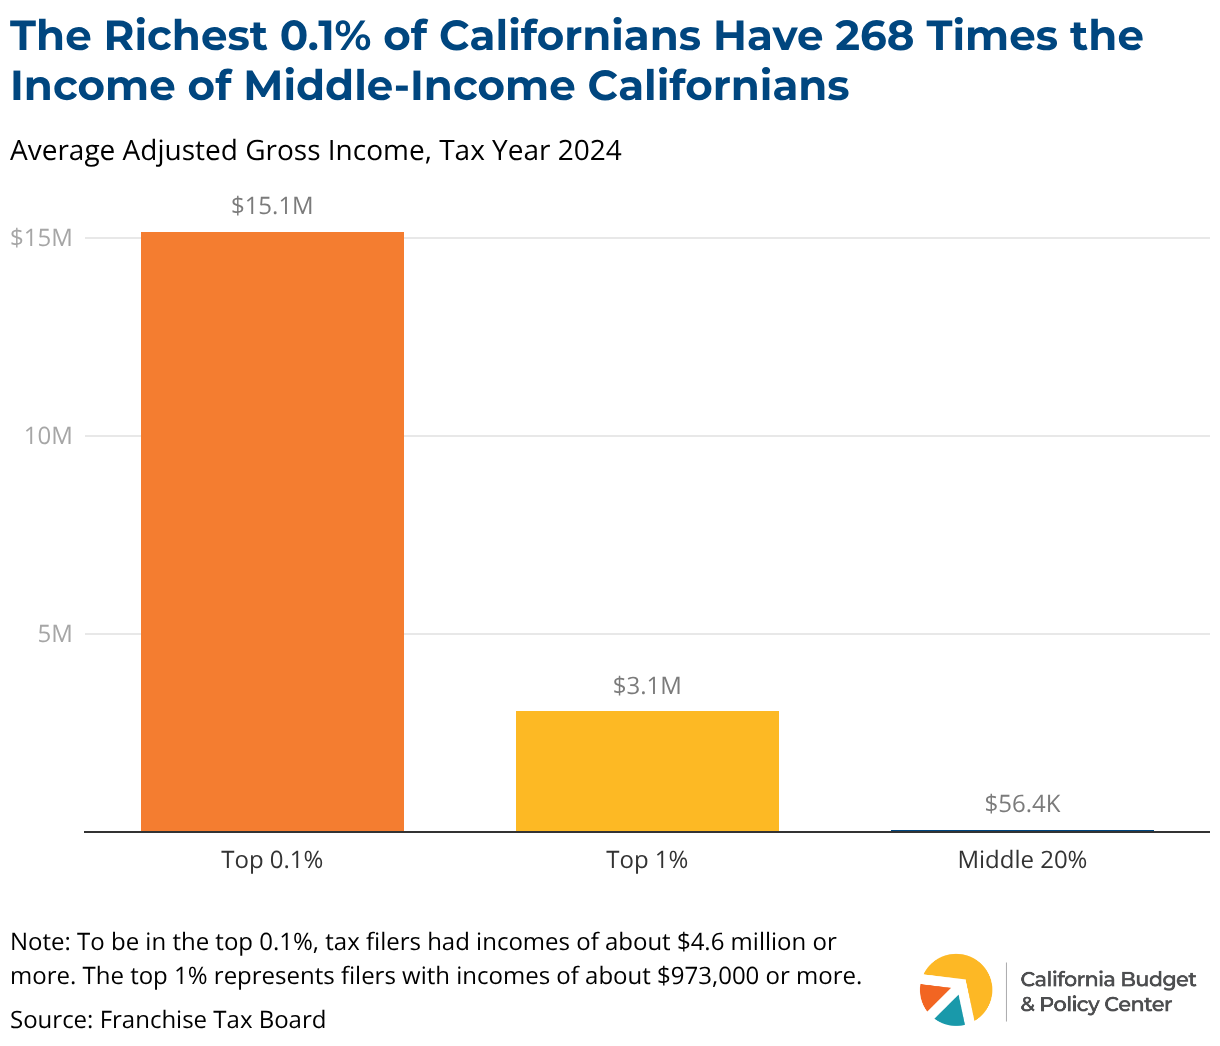
Across the country, the gaps in income and wealth have steadily grown with the top 10% of households seeing substantial growth in both income and wealth accumulation. Similarly, in California, only a tiny fraction of the population benefits from extreme income and wealth.
When focusing on the wealth distribution in the state, the data show an alarming gap between households with high and low wealth. Specifically, the wealthiest 20% of households have a net worth of over $1.5 million, while the bottom 20% of households have a net worth of $13,000 or less. Those who would be subject to the Prop. 40 tax — those with a net worth above $1 billion — have a net worth of over 3,000 times the median household.
Wealth is also unequally distributed across racial and ethnic groups. For example, the median net worth of white households in 2023 was almost ten times the median net worth of Latinx households, reflecting the historical barriers to wealth accumulation these communities have faced. Black, Latinx, and other households of color often have less wealth due to many factors including a lower likelihood of owning stocks, occupational segregation pushing them into lower-payer jobs, and a lack of inherited generational wealth. These factors likely contribute to the large wealth disparities that have persisted throughout history.
How Much Revenue Will Prop. 40 Raise?
There is a high degree of uncertainty in estimating the potential revenue from this measure since it is impossible to accurately predict how billionaires and the courts will respond to the tax. It is likely there will be some avoidance and evasion of the tax, as billionaires may hide or underreport their assets, shift their asset holdings toward those that are exempt from the tax, attempt to sever their ties with California, or engage in other tactics to minimize or eliminate their tax liability.
After attempting to account for these factors, the Legislative Analyst’s Office estimates that the billionaire tax would likely raise “tens of billions” of dollars in the near term. It also suggests there could be some ongoing reductions in state income tax collections in the future — likely less than $1 billion per year — depending on the extent to which billionaires leave the state and no longer pay California tax on their income.
Authors of Prop. 40 estimate that the measure could raise around $100 billion over five years, after assuming that 10% of the potential tax base would be eroded due to avoidance and evasion. They assume a relatively low avoidance and evasion rate due to the one-time nature of the tax and its retroactive residency date as well as the inclusion of provisions in the measure intended to safeguard against the avoidance and evasion strategies seen with wealth taxes implemented in other countries, such as allowing fewer exemptions for certain asset types and applying the tax to trusts as well as individuals.
The large difference between estimates lies mainly in different assumptions about how many billionaires have or will successfully sever their residency ties with California to avoid the tax. The potential for migration and other avoidance efforts related to the measure and their implications are discussed below.
What Would Prop. 40 Funds Pay For?
All the revenue from the Billionaire Tax Act is intended to mitigate the harm from federal and state-level cuts to health care, food assistance, and K-14 public education programs. The measure would create a special fund — the 2026 Billionaire Tax Reserve Fund — to hold the revenue.
Revenues in the fund — after accounting for the costs incurred by the Franchise Tax Board to administer the tax — would be split between two subaccounts, with 90% of revenue going into the Billionaire Tax Health Account and 10% going into the Billionaire Tax Education and Food Assistance Account.
Dollars in the Billionaire Tax Health Account would support health care funding, which could include but is not limited to:
Restoring or addressing any reductions in federal or state funding to health care programs;
Protecting and expanding Medi-Cal and other health coverage programs for low- and moderate-income Californians;
Supporting safety net health care providers serving vulnerable populations; and
Other investments relating to health care access, coverage, benefits, funding, services, and payments to providers.
Dollars in the Billionaire Tax Education and Food Assistance Account would support funding for K-14 and food assistance programs, which could include but is not limited to:
Restoring or addressing any reductions in federal or state funding to public education and food assistance programs;
Making investments to preserve or expand the K-14 education system; and
Expanding food programs like CalFresh, the California Food Assistance Program, CalFood, and the California Universal Meals Program.
Because the measure does not contain specific requirements as to how the dollars within each fund must be spent, beyond being used for “health care funding” and “education-related and food assistance expenditures,” policymakers would have fairly broad authority to determine the allocation of funding within those categories. However, the measure specifies that funds may not be used to replace existing state funds for health care, education, or food assistance.
Additionally, each subaccount has a limit for how much can be appropriated in a fiscal year. The health subaccount has an appropriation limit of $22.5 billion per fiscal year, and the education and food assistance account has a limit of $2.5 billion per fiscal year. The entire amount does not have to be allocated each year and funds can be retained if determined necessary.
Prop. 40 specifies that the revenue generated by the billionaire tax would be excluded from three spending requirements in the state Constitution:
the state spending cap (Prop. 4, the “Gann Limit”), which restricts the usage of revenues above a certain level, based on spending in 1978-79 adjusted for changes in population and income.
How Would Prop. 40 Revenues Impact Californians?
The majority of the revenues from the Billionaire Tax Act would directly support Californians who are harmed by federal and state cuts to the Medi-Cal and CalFresh programs.
H.R.1 is estimated to result in around 1.3 million Californians losing Medi-Cal coverage by 2029-30 and tens of billions of dollars in lost federal funding every year. These provisions target a wide range of populations including, but not limited to, immigrant Californians and low-income adults without dependents. Policy changes impacting these populations include increasing eligibility checks for Medi-Cal, imposing ineffective work reporting requirements, and limiting retroactive coverage for adults. Federal policy changes, including provisions of H.R. 1 and the expiration of enhanced premium tax credits, could also result in around 400,000 to 500,000 fewer Californians receiving health coverage through Covered California — the state’s health insurance marketplace established through the Affordable Care Act. The revenue from Prop. 40 could help mitigate some of the harms of these federal policies, for instance by replacing some lost federal funding and providing counties with additional resources to administer Medi-Cal and help eligible Californians maintain coverage.
This measure could also allocate funding to counteract the harmful enacted provisions from recent state budget packages that further harm Medi-Cal recipients. In combination with the federal cuts, state policy changes like freezing Medi-Cal enrollment for certain undocumented adults, imposing burdensome monthly premiums, reinstating the Medi-Cal asset limit, and denying full-scope Medi-Cal to certain immigrants could nearly double the uninsured rate to 14.7% by 2030.
A smaller proportion of the revenue could also go towards offsetting H.R.1’s harmful cuts to CalFresh. H.R.1 puts more than 3 million households at risk of losing some or all of their food assistance and could cost California between $2.3 billion and $5.1 billion annually. The provisions include applying time limits to previously exempt populations like veterans, older adults, and former foster youth and eliminating CalFresh for tens of thousands of lawfully present immigrants.
The Prop. 40 revenues could also help sustain and support funding for public education which has been facing federal threats such as funding freezes, grant cancellations, and proposed budget cuts. Public education would receive less support under the measure than if the revenues were allocated to the General Fund — due to the Prop. 98 minimum funding guarantee — but that would also mean less funding available for health care and food assistance. Additionally, because the measure does not require any specific share of funding in the Billionaire Tax Education and Food Assistance Account to go to any of the specified allowable uses, it is possible that all of these funds would be used to support food assistance and none for education — or alternatively, all of the funds could go to education and none to food assistance. Again, policymakers would have significant flexibility in allocating the dollars in this fund to specific programs that align with the intended purposes of the fund.
What Are the Concerns About Prop. 40?
Prop. 40 Would Provide One-Time Revenues to Respond to Ongoing Federal Funding Losses
While the revenue that would be generated by Prop. 40 is mainly intended to address the harms of the federal cuts to health care and food assistance resulting from H.R. 1 and other federal threats, the revenue from this one-time tax would only be available for a few years. If the federal government does not reverse those deep cuts within the next several years, the state will again be presented with the choice of cutting services and letting Californians impacted by federal cuts fall through the cracks or finding new alternative revenue sources to help keep them afloat.
The Revenue from Prop. 40 Would Not Be Available to Support Other Core State Services
Because the revenue would be earmarked, state programs and services that help Californians — beyond health care, food assistance, and education — would not receive any of the one-time revenue under Prop. 40. For example, none of the revenue would be available to support other critical needs such as affordable housing and renter supports, homelessness response, subsidized child care, or other safety net programs. As noted above, because the measure does not specify how the funds in the Education and Food Assistance Account would be allocated, it is possible that the funds could be used only for food assistance or only for education, so there is no guarantee that funding is allocated for both of these purposes.
On one hand, there is a clear need for increased health care funding to respond to the dramatic federal cuts that could strip millions of Californians of their health insurance and put immense strain on health clinics and hospitals, particularly in rural areas. This need supports the rationale for dedicating the vast majority of the revenue to health care programs.
On the other hand, Californians facing barriers to economic security have many critical needs, and the state has long underinvested in meeting those needs. New revenues are essential to protect and expand vital state services — including services beyond what Prop. 40 revenues are allowed to fund. If the revenues from a new tax on wealth went into the state’s General Fund, policymakers would have the flexibility to deliberate and decide how to allocate funding to address the most pressing and changing needs of Californians.
There Are Uncertain Impacts of a State-Level Wealth Tax on the State’s Longer-Term Budget and Economy
Imposing a state tax on wealth for a small share of the population is a novel and untested approach in the United States, and novel approaches always come with some risks. Concerns have often been raised about the potential impacts of such a tax on the behavior of the ultra-wealthy: the extent to which they will engage in tax avoidance behaviors that have consequences for the state. The majority of these concerns focus on the risk that billionaires will leave the state to avoid the tax, which would lead to some loss of future income tax revenues from those households if they do not return later. A related concern often raised is how these potential migration impacts could affect the state’s economy if wealthy business founders/owners choose to relocate some of their business activities or if future company founders opt to start businesses in another state for fear of a future wealth tax.
While a significant outmigration of billionaires could reduce the one-time revenue yield from the billionaire tax, the bigger concern for the state is the potential impact on ongoing state income tax revenues, which could put a strain on the state budget in the future. The outcome here is also uncertain. The income taxes paid by billionaires are very small relative to their overall wealth, and some billionaires can essentially avoid income taxes entirely in some years by not selling any assets or receiving a salary. For example, researchers — including an author of Prop. 40 — examined public data reported to the US Securities and Exchange Commission and found that Google founders Larry Page and Sergey Brin did not sell stock, receive dividends, or take any compensation related to Alphabet (Google’s parent company) in 2019, 2020, or 2023, so they likely would not have paid any income taxes related to their Alphabet holdings or involvement. Additionally, it is not clear that migration and income tax losses would be permanent in response to a one-time tax.
Prop. 40 aims to address the potential concerns about migration by applying the wealth tax to billionaires who were California residents as of January 1, 2026. This retroactive residency date is likely to be challenged in court. However, if it is upheld, any billionaire leaving after this date would not be able to avoid the tax. Additionally, even billionaires who announced moves out of California before this date may not have sufficiently severed their residency with the state for tax purposes, as the state’s Franchise Tax Board considers many factors when verifying residency status beyond simply whether a filer claims to be resident of another state or has purchased property in another state.
There is no way to accurately predict how billionaires would respond to the tax — or the prospect of being subject to the tax, as there is uncertainty about whether the measure will be approved by voters and whether the retroactive residency date will be upheld. There is a body of research on how income and wealth tax policies may impact interstate and international mobility of taxpayers, but the findings vary widely depending on the geographical scope, the type and magnitude of the tax change, the population impacted, the data available, and the research methodology.7For a summary of research focused on the mobility of high-income and high-wealth households in response to income and wealth taxes, see Fernando Rodrigo Sauco, “Millionaires on the Run? Taxation of the Rich and Induced Mobility: A Literature Review,” Hacienda Pública Española/Review of Public Economics 253, no. 2 (June 2025): 91-127.
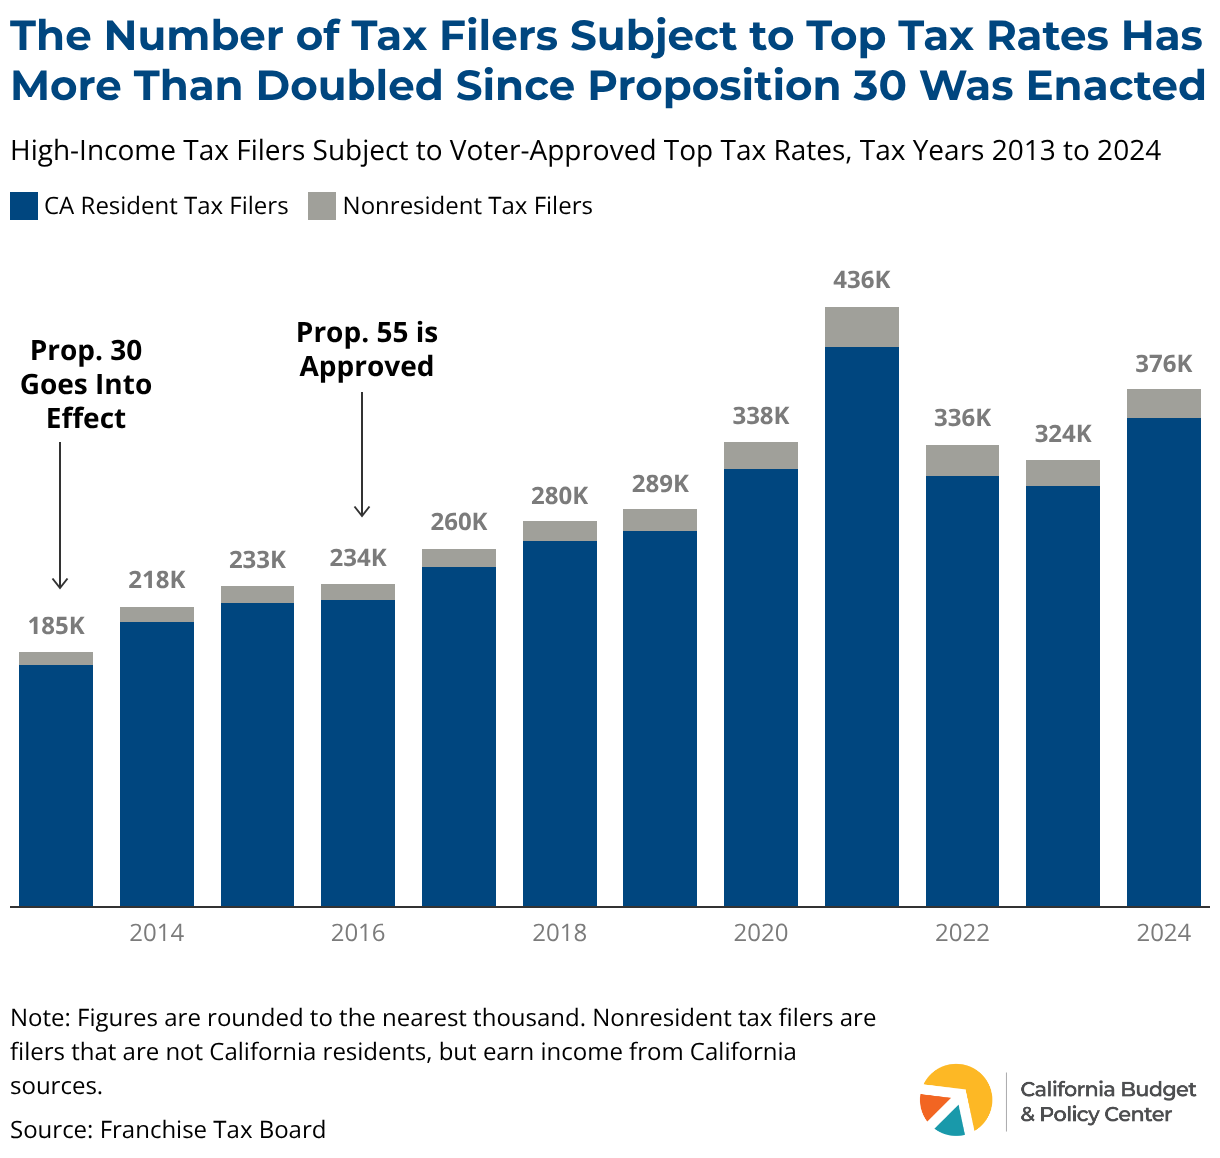
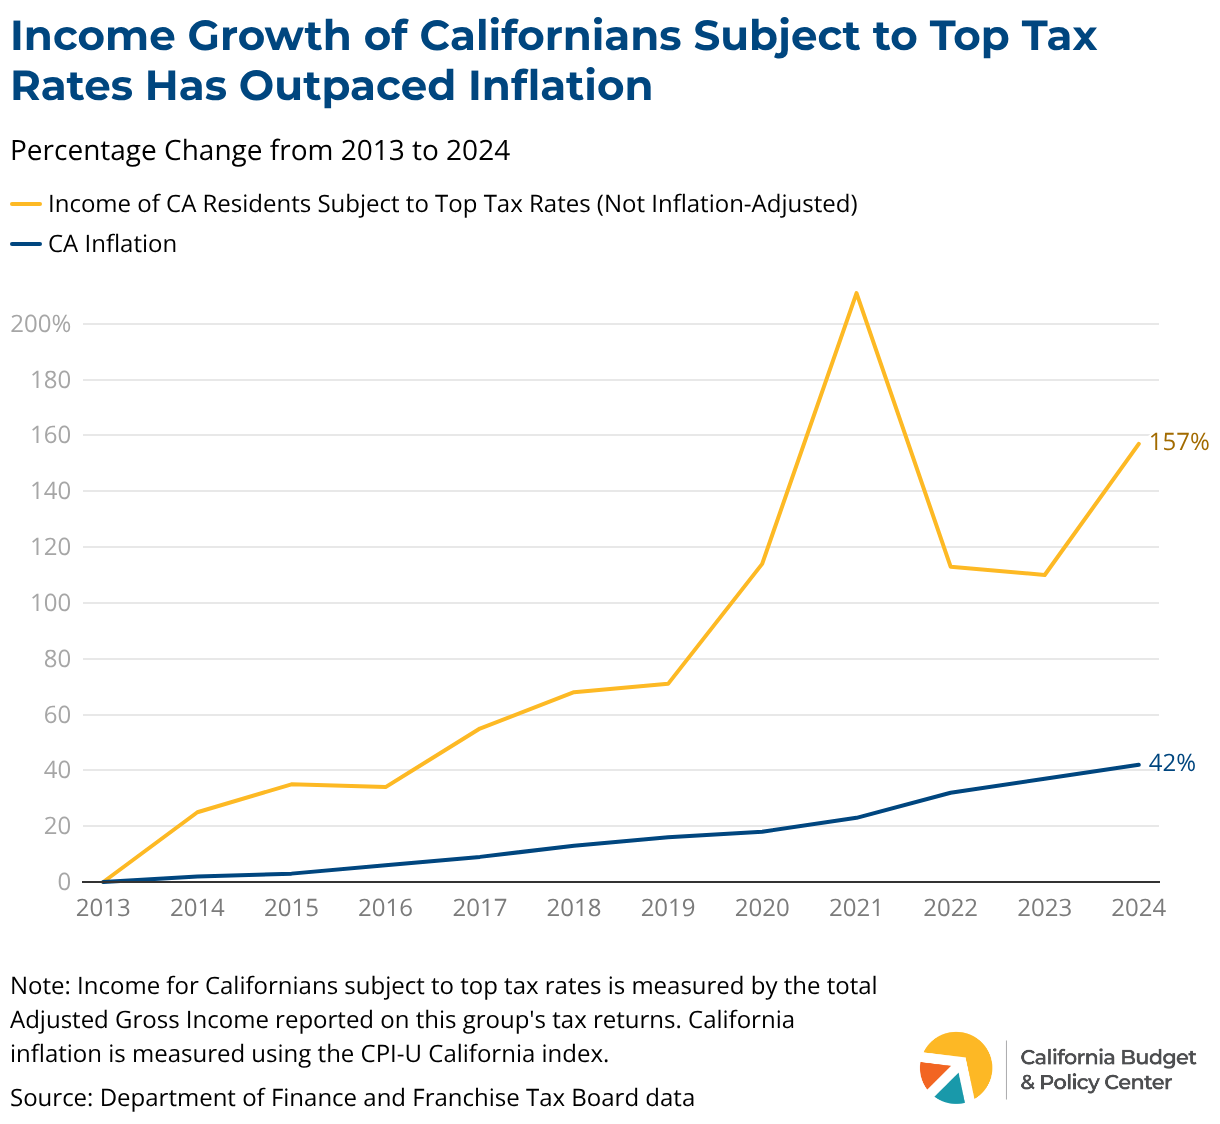
Research on the impacts of state-level income taxes on interstate migration has generally found very minor effects on the numbers of high-income people in a state relative to the state’s total population of high-income people.8While some studies have found statistically significant effects of taxes on migration rates among high-income tax filers, this translates to small changes in the stock of high-income people in a state. For example, Young et al. (2016) examined federal tax return data for all tax filers with incomes of at least $1 million across all states for 1999 to 2011 and estimated that a one percentage point increase in the income tax rates is associated with an 8% reduction in the net migration flows into the state — people moving in minus people moving out — but this only translates to only a 0.1% change in the population of millionaires. They also find that while millionaires are somewhat more sensitive to tax rates than the general population, they are also less likely to move between states overall. Rauh and Shyu (2024) examined the impacts of California’s income tax increases on high-income households enacted by Prop. 30 (2012) and estimated that the the tax increase was associated with a one-time increase in the outmigration rate of top-tax bracket filers of 0.8% — translating to around 535 out of the nearly 67,000 tax filers in the new top tax bracket. Notably, since the enactment of these top tax rates established by Prop. 30 and extended by Prop. 55 (2016), the numbers of tax filers with incomes placing them in these top tax brackets has grown significantly, along with the incomes of this group and the state revenue collections from the top rates. Additionally, there is evidence that state differences in tax rates have more significant effects on the choice of location among movers than on the probability of moving. For example, a study by Young and Lurie (2025) suggests millionaires in higher-tax states were no more likely to move than the general public in response to a 2017 federal tax change that impacted higher-income taxpayers in higher-tax states, but those that did move were more likely to move to lower-tax states. While taxes may be one factor in where people decide to live, they are one of many, and they may not outweigh other factors such as professional and family considerations, public amenities, weather, and lifestyle preferences. Indeed, survey data from the US Census Bureau show that the vast majority of people moving between states move for job or family reasons. Some research also finds that high-income people are generally less likely to move between states than the general population and are more embedded in their communities due to family, social, and business connections — they are more likely to be married, have children, and own businesses.9Young and Lurie (2025) did find an elevated migration of millionaires out of higher-tax states during the COVID pandemic when in-person social and business networks were disrupted, but this effect had generally subsided by the beginning of 2023.
However, the impact of a wealth tax on California billionaires may be different than the impact of income taxes on high-income households. There are no direct parallels to draw on, as no state has enacted this type of tax, and most wealth taxes in other countries have been imposed at the national level and applied to a broader segment of the population. These other wealth taxes have had substantial differences in design — including the tax rates, exemptions for specific types of assets, and the wealth thresholds above which the tax applies — as well as enforcement capacity. All of these factors can influence the impact of the tax, so the findings on migration and other avoidance behaviors are not uniform across studies of different wealth taxes and may not be directly relevant to the potential impact of a California billionaire tax.
Several countries, mainly in Europe, have levied taxes on their residents’ net worth in the past, but most have since repealed them. Among high-income countries — members of the Organization for Economic Cooperation and Development (OECD) — four currently impose taxes on wealth: Colombia, Norway, Spain, and Switzerland. This is down from 12 OECD countries with wealth taxes in 1990. A few other countries still have fairly comprehensive taxes on wealth — including Argentina (althougFor example, the Spain wealth tax study did find higher responses for people in higher wealth tax brackets, and a study on the impact of state-level estate taxes — essentially a one-time wealth tax levied when someone dies — on the state residence of US billionaires in the Forbes 400 found this population to be quite sensitive to the presence of an estate tax. However, this finding may not extend to a one-time wealth tax given that people are more likely to be mobile after retirement and may factor estate planning into their location decisions — and the estate tax study did find a stronger response for older billionaires.h this tax is being phased down), Bolivia, Uruguay — and additional countries including Belgium and Italy have taxes on the value of narrower categories of assets.10Washington State Department of Revenue, Wealth Tax Study Report(November 2024); PwC, Worldwide Tax Summaries: Net wealth/worth tax rates (Accessed July 6, 2026). Italy levies a 0.2% tax on foreign financial assets, and Belgium levies a 0.15% tax on securities accounts of at least 1 million euros.
Studies on wealth taxes in Spain and Switzerland — the only countries that have subnational wealth tax regimes instead of uniform national wealth taxes — found migration responses related to variation in tax rates between regions. The studies estimate that a one percentage point change in a wealth tax rate was associated with a change of around 8% to 10% in the population impacted by the tax. If billionaires in California had a similar response, a 5% wealth tax could result in substantial outmigration.
However, there are some caveats to extrapolating these findings — beyond the retroactive residency provision in Prop. 40 that may render billionaire outmigration after January 1, 2026 moot for the purpose of the tax. The subdivisions of Spain and Switzerland are much smaller than California, the taxes are ongoing instead of one-time, they are present across most or all regions of the countries, and they apply to a much broader population than billionaires — these factors could pull in opposite directions with regard to the applicability of these findings. It is also likely that some of the reported residence changes are fraudulent. Researchers found some suggestive evidence that false residency changes — such as a taxpayer claiming that a second home is their primary home — are responsible for some of the effect in Spain. The prevalence of this phenomenon could be limited with adequate enforcement.
There is a possibility that wealthier people are more likely to move in response to taxes, which would have implications for a tax specifically targeted to billionaires.
For example, the Spain wealth tax study did find higher responses for people in higher wealth tax brackets, and a study on the impact of state-level estate taxes — essentially a one-time wealth tax levied when someone dies — on the state residence of US billionaires in the Forbes 400 found this population to be quite sensitive to the presence of an estate tax.11Note that this finding is specific to the ultra-wealthy Forbes 400 group, so it cannot be generalized to a broader group of wealthy households. Previous research examining the effect of estate and inheritance taxes on state migration rates of older adults and the locations of wealthy older adults estimated insignificant or modest effects. However, this finding may not extend to a one-time wealth tax given that people are more likely to be mobile after retirement and may factor estate planning into their location decisions — and the estate tax study did find a stronger response for older billionaires.
There is limited research on the overall economic impacts of wealth taxes. One recent study on now-repealed national-level wealth taxes in Sweden and Denmark — looking at the effects of tax reductions and repeals — estimated that a one percentage point increase in top wealth tax rates decreases the number of wealthy taxpayers in the country by about 2%, and because the wealthy are disproportionately business owners, there are some broader economic impacts. However, the estimated effects were very modest, as a large portion of business activity lost due to the outmigration of business owners is absorbed by other remaining businesses. Again, the differences in geography, nature of the tax changes studied (tax cuts versus tax increases), and the fact that these were recurring rather than one-time taxes mean that these findings may not be generalizable to a one-time state-level tax.
Research on one-time or temporary wealth taxes is limited. Several countries in Europe enacted national-level, short-term wealth taxes in the wake of WWI and WWII, and some levied narrow temporary taxes targeting wealth holdings after the Great Recession, with varying levels of success depending on the circumstances. The vast differences in historical context, geographic focus, and design elements — such as tax rates, payment periods, exemption levels, and assets targeted — make these experiences not particularly relevant comparisons for the Prop. 40 proposal, and there has not been empirical research on the migration or general economic impacts of these temporary taxes.
In sum, although existing research can provide some insights into the potential impacts of a one-time California billionaire wealth tax, there are many unknowns given the unique nature of the proposal. Additionally, the findings from research on tax policy impacts may not always identify causality or precisely measure effects due to the many potential confounding factors. Finally, even if effects are precisely measured, the research attempts to isolate the effects of tax policies holding all else equal, when in the real world there are a variety of factors influencing location decisions beyond taxes. Ultimately, California voters will need to decide if the benefits of the revenue generated by a tax on billionaires outweigh the concerns about the uncertain future fiscal and economic effects.
How Do Props. 41 and 42 Conflict With Prop. 40 on the November Ballot?
Two other constitutional amendment measures appearing on the November ballot, Prop. 41 and Prop. 42, contain provisions that conflict with Prop. 40 and could invalidate it in part or in full if they receive more votes. These measures could also make it harder to raise state revenues in the future to invest in the well-being of Californians, which could result in cuts to essential services that Californians want and need.
What is Proposition 41?
Prop. 41 would:
Require the State Auditor to conduct audits of programs that would receive revenue from new or higher special taxes, which are taxes that are dedicated to specific purposes rather than going into the state’s General Fund. This would include ongoing audits — every four years — of programs receiving funds from special taxes enacted on January 1, 2026 or later by either the Legislature or state voters. Additionally, pre-election audits would be required for programs that would receive revenues from a new or increased special tax that would appear on the statewide ballot. The pre-ballot and ongoing audits would be required to, among other things, contain recommendations on how the programs could reduce its costs by at least 10% annually. Policymakers would be under no obligation to implement these recommendations, but if they did, it could result in cuts to core services rather than simply “inefficient spending.”
Prohibit revenues raised by special taxes enacted since January 1, 2026 from being excluded from the state’s spending cap, also known as the “Gann Limit.” The measure also specifies that if another measure on the same ballot imposes a tax and exempts its revenues from the Gann Limit, the entirety of the other measure would be invalidated if Prop. 41 receives more votes. However, this would not prevent voters from approving future amendments to the state Constitution that would exclude certain tax revenues from the Gann Limit.
Because Prop. 40 would exclude the revenue generated by the billionaire tax from the Gann Limit, this is in direct conflict with Prop. 41. If both measures are approved, but Prop. 41 receives more votes, Prop. 40 could be invalidated. Alternatively, if both measures pass but Prop. 40 receives more votes, the billionaire tax could be collected, but it is possible that audits would be required of Medi-Cal and other programs receiving Prop. 40 dollars. If both measures pass, there may be litigation regarding the application of conflicting provisions, and the final decision would be made by the courts.
What is Proposition 42?
Prop. 42 would:
Prohibit the imposition of any new tax on the ownership of financial assets (such as bank accounts, stocks, bonds, or mutual funds), retirement accounts, interests in businesses, intellectual property, and other personal property (such as vehicles, jewelry, artwork, and other movable, physical property). Essentially, this would limit the taxation of assets to real estate assets, which are already subject to constitutional tax limitations under Prop. 13. However, if this measure is passed, it would not prevent voters from amending the state Constitution to tax any of these assets in the future, but state policymakers would not be able to enact taxes on any of the assets covered by Prop. 42 without voter approval.
Prohibit the imposition of new retroactive taxes, and in particular taxes based on residency prior to the effective date of the new tax — except in cases where the revenues would be used to respond to a governor-declared emergency and the tax does not apply retroactively for more than one year before the effective date. Once again, the approval of Prop. 42 would not impact the ability of voters to approve retroactive taxes in the future, but would impact state policymakers’ ability to do so. As noted above, many tax laws do have limited retroactivity periods — such as dating back to the beginning of a tax year — for several reasons, including preventing tax avoidance.
Both of these provisions conflict with Prop. 40, as the billionaire tax would apply to financial assets, business interests, and other personal property, and it would be retroactively based on the taxpayer’s residence as of January 1, 2026. If both measures pass and Prop. 42 receives more votes, Prop. 40 could be invalidated. If Prop. 40 receives more votes, the wealth tax could be collected, but Prop. 42’s tax restrictions would likely apply to future legislative tax proposals. Again, conflicts may ultimately be decided in courts if both measures pass.
The Bottom Line on Prop. 40
Prop. 40 is a bold proposal that would create a first-in-the-nation tax on wealth, raising significant — temporary — revenue by taxing the fortunes of California’s more than 250 billionaires. Proponents argue this unprecedented measure is needed to help offset deep federal cuts and protect health care, food assistance, and education for all Californians. Because a wealth tax is untested at a state level in the United States, it carries real uncertainty: courts may strike down the measure or portions of it, conflicting measures could lead to years of litigation, and no one can say how the location decisions of billionaires might change and what that would mean for California’s long-term finances.
California voters will need to decide if the benefits of the revenue generated by a tax on billionaires outweigh the concerns about the uncertain future fiscal and economic effects of the billionaires tax.
Prop. 40 Supporters and Opponents
Prop. 40 is sponsored by Service Employees International Union — United Healthcare Workers West (SEIU-UHW), a local union representing health care workers. It has been endorsed by labor organizations including AFSCME California and Teamsters California, organizations including Our Revolution and California Democratic Socialists of America, and policymakers including US Senator Bernie Sanders, US Representative Ro Khanna, and State Superintendent of Public Instruction and former gubernatorial candidate Tony Thurmond.
Prop. 40 is opposed by labor organizations including the California Teachers Association and the State Building and Construction Trades Council of California, organizations including the California Business Roundtable, the California Medical Association, Planned Parenthood Affiliates of California, policymakers including Governor Gavin Newsom and US Representative Kevin Kiley, and gubernatorial candidates Xavier Becerra and Steve Hilton.
The California Budget & Policy Center is a nonpartisan research and analysis nonprofit and does not endorse or oppose ballot measures. This analysis reflects the institutional position of the Budget Center, developed and reviewed by our policy leadership team.
Kayla Kitson and Nishi Nair contributed to this publication.
Forbes tracks the daily wealth of billionaires with its “Real-Time Billionaires” list, and the California-specific data was compiled in connection with Jasper Boll, Emmanuel Saez, and Gabriel Zucman, California Billionaires: Wealth, Taxes, and Wealth Tax Revenue Estimates (NBER Working Paper 35218, May 2026). Note: Saez is an author of Prop. 40. ↩︎
2
Specifically, the 5% rate would be reduced by 0.1 percentage point for each $2 million that the household’s net worth falls below $1.1 billion. ↩︎
3
Tangible personal property is excluded from the net worth calculation if it is held outside of California for at least 270 days during 2026 unless it was temporarily relocated for the purpose of tax avoidance. ↩︎
4
Tax avoidance reflects legal avenues to reducing tax liability, such as redirecting wealth holdings to exempted assets or relocating, whereas tax evasion encompasses illegal tactics to avoid taxes, such as hiding assets in tax havens, underreporting of asset values, or falsely claiming residency outside of the tax jurisdiction. ↩︎
Department of Finance, Tax Expenditure Report: 2025-26, p. 24. Note that the estimated annual cost of the provision is not equivalent to the revenue that could be generated from repealing it, and for this provision the revenue gains from repeal would start in the low hundreds of millions and increase with time, potentially reaching $5 billion annually in the future. ↩︎
While some studies have found statistically significant effects of taxes on migration rates among high-income tax filers, this translates to small changes in the stock of high-income people in a state. For example, Young et al. (2016) examined federal tax return data for all tax filers with incomes of at least $1 million across all states for 1999 to 2011 and estimated that a one percentage point increase in the income tax rates is associated with an 8% reduction in the net migration flows into the state — people moving in minus people moving out — but this only translates to only a 0.1% change in the population of millionaires. They also find that while millionaires are somewhat more sensitive to tax rates than the general population, they are also less likely to move between states overall. Rauh and Shyu (2024) examined the impacts of California’s income tax increases on high-income households enacted by Prop. 30 (2012) and estimated that the the tax increase was associated with a one-time increase in the outmigration rate of top-tax bracket filers of 0.8% — translating to around 535 out of the nearly 67,000 tax filers in the new top tax bracket. Notably, since the enactment of these top tax rates established by Prop. 30 and extended by Prop. 55 (2016), the numbers of tax filers with incomes placing them in these top tax brackets has grown significantly, along with the incomes of this group and the state revenue collections from the top rates. Additionally, there is evidence that state differences in tax rates have more significant effects on the choice of location among movers than on the probability of moving. For example, a study by Young and Lurie (2025) suggests millionaires in higher-tax states were no more likely to move than the general public in response to a 2017 federal tax change that impacted higher-income taxpayers in higher-tax states, but those that did move were more likely to move to lower-tax states. ↩︎
9
Young and Lurie (2025) did find an elevated migration of millionaires out of higher-tax states during the COVID pandemic when in-person social and business networks were disrupted, but this effect had generally subsided by the beginning of 2023. ↩︎
Note that this finding is specific to the ultra-wealthy Forbes 400 group, so it cannot be generalized to a broader group of wealthy households. Previous research examining the effect of estate and inheritance taxes on state migration rates of older adults and the locations of wealthy older adults estimated insignificant or modest effects. ↩︎
You may also be interested in the following resources:
SACRAMENTO, CA — A new publication released today by the California Budget & Policy Center (Budget Center) examines how California’s voter-approved top income tax rates have helped fund schools, health care, and other essential state services over the past decade and what’s at stake as Proposition 3, which will be on the November ballot, asks … Continued
key takeaway
Proposition 3 will appear on the November 2026 statewide ballot, asking California voters whether to make permanent the higher-income tax rates on the state’s highest earners. These top tax rates were first enacted by voters in 2012 and renewed in 2016 to help fund schools, health care, and other supports for working families. Without action, the current rates are set to expire after 2030, reducing state revenues by billions of dollars annually and threatening funding for schools and state programs and services that support Californians every day.
Prop. 3 would make permanent the rates put in place since 2012, preserving a key element of progressivity (requiring households with higher incomes to pay higher tax rates) in the state’s revenue structure that funds critical investments that improve the quality of life for all Californians. The measure would not raise taxes or change existing income tax rates; it simply removes the expiration date on current tax rates for the state’s highest earners. Revenues would continue to support the entire state General Fund budget by helping meet the TK-14 constitutional funding guarantee and freeing up revenue for other programs and services, just as they have since 2012.
Background on Prop. 30 and Prop. 55
In 2012, after the state faced significant revenue losses as a result of the Great Recession, California voters approved Proposition 30, which added new income tax brackets for the state’s highest earners (10.3%, 11.3%, and 12.3%, depending on household income) and included a temporary sales tax increase. Both the income tax rates and the sales tax increase were temporary, with the sales tax set to expire in 2016 and the income tax rates in 2018. Proposition 30 also created the Education Protection Account, a state account in the General Fund that receives and disburses revenues from the top income tax rates.
what is the education protection account (epa)?
Proposition 30 (2012) established the Education Protection Account, a state account where revenues from the top income tax rates are deposited. Of the funds in the account, 89% are distributed to schools and 11% to community colleges. This revenue is treated as General Fund revenue, subject to constitutional requirements including Prop. 98 (1988), the state’s minimum funding guarantee for TK-14 education, and Prop. 2 (2014), which established rules for building state budget reserves and paying down state debts. The revenue deposited into the EPA increases the Prop. 98 guarantee and is used to help meet the guarantee, freeing up General Fund revenue for other state budget priorities.
In 2016, voters approved Proposition 55, which extended the income tax rates for another 12 years (to 2030), while allowing the sales tax to expire as scheduled. Prop. 55 also added a constitutional formula intended to increase funding for the Medi-Cal program when revenues exceed a certain threshold. This specific formula has never directed funds to Medi-Cal, and the current measure would allow it to expire. However, top tax rate revenues do support the Medi-Cal budget indirectly through the General Fund capacity generated by Prop. 55.
Since their initial enactment in 2012, these higher tax rates have generated around $120 billion for schools and other essential services. In recent years, the higher rates have generated around $10 billion annually. These revenues now form a core component of the state budget, supporting the TK-14 education budget, strengthening General Fund capacity to support other vital programs and services, and building reserves.
Who Pays the Voter-Approved Top Tax Rates?
The voter-approved top tax rates only impact the highest-income Californians.
These rates only apply to the top 2% of California tax filers. In tax year 2025, these top rates only applied to people with incomes above around $371,000 for single tax filers and about $743,000 for married couples filing jointly. These thresholds increase annually with inflation.
Without Voter-Approved Tax Rates, the Top 1% Would Receive Another Tax Cut
The top-earning 1% of Californians would receive a major tax cut if Prop. 55 rates are not extended. If the voter-approved top tax rates are allowed to expire, the vast majority of tax filers in the top 1% by income would receive an average annual tax cut of nearly $59,000, according to estimates from the Institute on Taxation and Economic Policy. This top 1% group would get about 98% of the total tax cuts. The remaining tax cuts would go to some households in the next 4% of highest-income filers.1Not all households in the top 5% or top 1% would receive tax cuts from the expiration of the top tax rates for several reasons. First, filers are subject to the top tax rates if their taxable income — that is, income after accounting for allowed exemptions and deductions — exceeds the thresholds established by Prop. 30 and Prop. 50. In contrast, the thresholds for the top 5% and top 1% used by the Institute on Taxation and Economic Policy for this analysis are based on total income before exemptions and deductions. So tax filers in the top 1% by total income may have taxable incomes under the threshold for the top rates. Second, some high-income filers that use specific tax preferences may be subject to an “alternative minimum tax,” which could be triggered if their regular tax bill were reduced. And finally, because thresholds for these rates vary by household type, a married couple filing a joint tax return with a total income of $500,000 falls into the top 5% of all tax filers, but their total income — even before accounting for exemptions and deductions — is below the threshold for the Prop. 55 taxes of around $743,000, for example. Around 15% of this group would receive a tax cut, averaging more than $2,000 annually. Californians in all other income groups would see no change to their taxes.
California’s tax system would be more regressive if the Prop. 55 tax rates expire. A regressive tax system is one in which lower-income households pay larger shares of their income in taxes than higher-income households. In contrast, in a progressive tax system, higher-income people pay higher shares of their income in taxes. California’s tax system is more progressive than many other state tax systems, in large part due to these voter-approved top tax rates that are up for renewal under Prop. 3.
When you add up the various state and local taxes that Californians pay — including the sales tax, property tax, and other types of taxes — the highest-income 1% currently pay about 12% of their income in taxes on average. That’s barely more than the 11.7% paid by Californians in the lowest 20% by income. If the top rates were not in effect, the top 1% would pay only about 10.7% of their income in state and local taxes — lower than what the bottom fifth of Californians pay.
Top Earners’ Incomes Have Soared
The number of Californians with incomes high enough to be subject to the voter-approved top tax rates has more than doubled, reflecting soaring incomes among top earners. Around 185,000 tax filers, including more than 175,000 California resident filers, had incomes above the thresholds for Prop. 30’s top tax rates in 2013, the first year the rates were in effect. By 2024 (the latest available data), the number had reached nearly 376,000, including around 355,000 California residents.2“Tax filer” represents a tax filing unit — the primary filer as well as any spouses and dependents included on the tax return. A tax filing unit can be an individual, a couple, or a family, and in some cases can include unrelated dependents. This increase is due to the incomes of these high-income households growing much faster than inflation over this period.
Californians subject to the top tax rates have seen their incomes grow dramatically over the past several decades, while most Californians have lost ground or experienced income declinesafter adjusting for inflation. The top 1% of Californians saw their inflation-adjustedincomes increase more than 2.5 times (157%) between 1987 and 2024, while those in the bottom 80% saw decreases in real income over that time.
To be in the top 1%, a tax filer had an income of at least $973,097 in 2024. On average, this group reported more than $3 million per tax return in 2024 — about 54 times the income of the middle fifth of Californians, who earned around $56,000 on average. In even starker contrast, the top 0.1% had an average income of over $15 million — 268 times that of the middle fifth of Californians. In other words, someone in the top 1% can earn in just under one week what the average middle-income Californian earns in an entire year, and someone in the top 0.1% can earn that amount in just over a day.
What Have the Top Income Tax Rates Accomplished?
Since the passage of Prop. 30 in 2012, the top tax rates have generated about $120 billion in state revenue.3This figure reflects revenues from the top tax rates allocated to TK-14 education from the Education Protection Account (EPA) through the 2024-25 fiscal year. On average, this revenue has represented about 5.5% of total General Fund revenues. The funds raised by the top tax rates approved by voters through Prop. 30 and Prop. 55 have been a major revenue source for the state, supporting critical services including education, health care, and economic security programs. This revenue has also helped the state to build up budget reserves to be better prepared for downturns when revenues decline or come in lower than expected.
The annual revenue raised by the top tax rates has increased in line with overall state revenues. These revenues are sensitive to stock market fluctuations, as a large share of the income of high-income households comes from earnings on investments such as dividends and capital gains. For example, Prop. 55 revenues peaked at more than $16 billion when the stock market surged in 2021 and then subsequently fell in line with the stock market decline in the following years, before growing to nearly $12 billion in 2024. The sensitivity of these revenues to economic conditions makes it all the more important that state leaders have the capacity to save revenues during high-revenue years in the state’s budget reserves for future downturns, as required under Prop. 2 of 2014 — which may be modified to require additional savings in some strong-revenue years if voters approve changes to the existing measure with Prop. 2 on the November 2026 ballot.
Top tax rate revenues provide critical support for schools and community colleges. Top tax rate revenues serve two purposes for the TK-14 education budget: 1) increase the Prop. 98 minimum guarantee’s annual calculation and 2) provide the revenues needed to meet the guarantee. Because top tax rate revenues count as General Fund revenues, they directly affect how the annual Prop. 98 level is calculated. In years when the General Fund experiences strong growth, the guarantee is set as a share (about 40%) of General Fund revenues, establishing a higher floor.4The minimum guarantee is determined using one of three formulas: 1) approximately 40% of General Fund revenue, 2) the prior year level adjusted for K-12 attendance growth and growth in per capita personal income, or 3) the prior year level adjusted for K-12 attendance growth and per capita General Fund revenue growth. In other years, the guarantee builds on the prior year’s level, carrying forward the growth built when revenues were strong. Regardless of how the guarantee is calculated, the effect of the top tax rate revenue is cumulative. As shown in the chart below, the guarantee has grown on an ongoing basis since 2012-13, with part of this growth attributable to the top tax rates.
what is proposition 98?
Prop. 98 is a constitutional amendment adopted by California voters in 1988 that establishes an annual minimum funding level for TK-14 education each fiscal year, commonly referred to as the minimum guarantee. Prop. 98 funding comes from a combination of state General Fund revenue and local property taxes. Prop. 98 spending supports TK-12 schools, community colleges, county offices of education, the state preschool program, and state agencies that provide direct TK-14 instructional programs. While Prop. 98 establishes a required minimum funding level for programs falling under the guarantee as a whole, it does not protect individual programs from reduction or elimination.
In addition to raising the guarantee’s calculation, Prop. 55 revenues directly help meet the guarantee. Revenues from the top tax rates are used to meet the Prop. 98 obligation, which frees up General Fund dollars that would otherwise be needed to meet the guarantee. These freed-up dollars are used to support non-TK-14 programs, build state reserves, and pay down debts. Since 2012-13, when these revenues began to flow to schools and community colleges, Prop. 55 revenues have provided about $120 billion to help meet the TK-14 budget.5While the top tax rate revenues have provided approximately $120 billion to the TK-14 budget through the EPA, because these revenues also reduce the General Fund dollars to meet the guarantee, the overall education funding impact is approximately 40% of total revenues.
The chart below shows the growth in the minimum guarantee, and the share provided by the top tax rate revenues, adjusted to 2024 dollars. Throughout this period, top tax rate revenues have enabled the state to implement key educational programs. For example, in the 2013-14 school year, policymakers began implementing a major school finance reform to more equitably allocate dollars to school districts based on student need.
Top tax rate revenues have also created more General Fund capacity to support critical economic security, housing, and health programs.
By helping meet the TK-14 constitutional funding guarantee, these revenues reduce General Fund dollars needed for that obligation, freeing up resources for other budget priorities, including:
California’s Earned Income Tax Credit, which boosts incomes for workers who earn little from their jobs, was initially established in 2015, and was expanded to more Californians in 2017 and 2018.
In 2021, policymakers launched a multi-year plan to fund an increase of 200,000 child care slots, reaching about 152,000 in 2026-27, making progress in expanding access to children and families with low incomes.
In 2019, the state created the Homeless Housing, Assistance and Prevention (HHAP) program, which provides funding to localities to finance solutions tailored to their needs and has shown positive outcomes, including reducing youth homelessness.
Policymakers restored several Medi-Cal benefits between 2014 and 2019 that had been cut due to budget shortfalls during the Great Recession, including adult dental benefits, podiatry, optometry, audiology, and speech therapy services.
Prop. 30 and Prop. 55 have increased the state’s capacity to save for a rainy day and pay down debts.
The revenues from the top tax rates have helped put the state in a better position to weather difficult economic times by increasing deposits into state budget reserves and helping to pay down budgetary debt.6Prop. 2 (2026), if approved, would make additional changes to require state leaders to increase deposits into the rainy day fund in some high-revenue years. Voters approved Prop. 2 in 2014, which requires the state to set aside a certain share of General Fund revenues each year in order to build the state’s rainy day fund (the Budget Stabilization Account) and pay down state budgetary debts. Under these rules, the state must set aside 1.5% of General Fund revenues each year, half of which is deposited into the rainy day fund while the other half must be used to pay down state debts.7Starting in 2030-31, the entire amount will be deposited into the rainy day fund, although policymakers will retain the option to use up to one-half to pay down debts. Additionally, the state is required to set aside additional revenues in years when revenues from taxes on capital gains exceed 8% of total General Fund tax revenues.
Since Prop. 2, California has been able to build up substantial reserves, aided by the revenues generated by Prop. 30 and Prop. 55. The balance is projected to be more than $15 billion for fiscal year 2026-27 under the enacted budget. In addition to the required 1.5% set-aside of revenues, Prop. 30 and Prop. 55 have likely resulted in larger capital gains-related set-asides, as high-income people subject to the top tax rates receive more of their income in the form of capital gains (proceeds from selling assets such as stock holdings).
Prop. 2 also created a new budget reserve to support schools and community colleges, the Public School System Stabilization Account (PSSSA). Deposits into this reserve are required only if certain budget conditions are met, typically when revenue growth is strong — particularly revenue from capital gains. Thus, the top tax rates help to boost deposits into this reserve to support TK-14 education when revenues fall short.
In recent years, the PSSSA has provided one-time resources to sustain education programs. For example, in the 2023-24 fiscal year, the state was not able to meet the minimum guarantee and the full balance ($8.4 billion) was withdrawn to help sustain existing programs. At the end of 2026-27, the mandatory deposits in this account are projected to total $8.7 billion, with a full balance of $9.4 billion.
Why Renewing the Top Tax Rates Matters for California
As the revenues from the current top tax rates have become a critical source of funding for education, health care, and other state services, their expiration after 2030 would likely lead to significant budget shortfalls. If Prop. 3 does not pass — and state leaders or voters do not approve alternative revenues — funding for essential state services would be put in jeopardy. This is especially concerning given that state officials already project ongoing budget deficits in upcoming years, as the cost of existing state services is growing due to inflation and a changing population, and revenue growth is not keeping up. Those projected deficits, compounded by federal cuts resulting from H.R. 1, the 2025 federal budget reconciliation law known as the “One Big Beautiful Bill Act,” would put significant pressure on the state budget and the programs it supports.
In recent years, the top tax rates have contributed around $10 billion annually to the state budget, and the Legislative Analyst’s Office projects that making these rates permanent would bring in between $5 billion and $15 billion annually in the future — depending on the economy and stock market performance. The loss of $5 billion to $15 billion could mean:
Reduced General Fund resources to protect and strengthen services that keep Californians healthy, housed, and economically secure. In recent years, more than two-thirds of state spending growth from available revenues has gone simply to sustaining existing levels of services, including keeping pace with rising costs and growing caseloads in programs like Medi-Cal, In-Home Supportive Services, and child care. The loss of Prop. 55 revenues would worsen existing deficit projections, making it harder for the state to maintain even current levels of services, potentially leading to programmatic cuts to essential programs.
The loss of a key revenue stream and increased pressure to meet the Prop. 98 minimum guarantee. In the near term, without the revenues from the top tax rates, the state would need to replace billions in funding for TK-12 education from other General Fund sources to meet the guarantee, potentially resulting in cuts to other services like health care and child care.8As noted in a text box above (“What Is the Education Protection Account?”), the revenues from the top tax rates both 1) increase the Prop. 98 guarantee and 2) are used to help meet the guarantee, freeing up General Fund revenue for other state budget priorities. If the top tax rates are not extended, the revenues that they generate would be eliminated after the 2030 tax year. This would impact the level of the Prop. 98 guarantee while also creating a hole in the Prop. 98 budget that would have to be filled with other General Fund revenue. In the long run, the loss of this dedicated revenue stream would result in the Prop. 98 guarantee being lower than if the top tax rates were extended — by around 40% of the total revenue loss. In other words, TK-14 education would receive less funding over time than it would if voters extended the top rates.
A reduced capacity to save and prepare for economic downturns. Without the additional revenues from the current top tax rates, deposits into the state’s rainy day fund and debt repayments required by Prop. 2 would be lower. This would leave the state less resilient when the next recession arrives, making critical state services more vulnerable to cuts.
Diminished ability to respond to anticipated federal cuts. The 2025 budget reconciliation package, H.R.1, includes significant cuts to health care and food assistance. Cuts to health care could total tens of billions each year. On top of that, cuts to food assistance could cost the state more than $5 billion annually. Currently, the state budget does not have the General Fund capacity to fully address these cuts, and the loss of top tax rates would only increase the millions of Californians at risk of losing these critical services.
The California Budget & Policy Center is a nonpartisan research and analysis nonprofit and does not endorse or oppose ballot measures. This analysis reflects the institutional position of the Budget Center, developed and reviewed by our policy leadership team.
Kayla Kitson and Erik Saucedo contributed to this publication.
Not all households in the top 5% or top 1% would receive tax cuts from the expiration of the top tax rates for several reasons. First, filers are subject to the top tax rates if their taxable income — that is, income after accounting for allowed exemptions and deductions — exceeds the thresholds established by Prop. 30 and Prop. 50. In contrast, the thresholds for the top 5% and top 1% used by the Institute on Taxation and Economic Policy for this analysis are based on total income before exemptions and deductions. So tax filers in the top 1% by total income may have taxable incomes under the threshold for the top rates. Second, some high-income filers that use specific tax preferences may be subject to an “alternative minimum tax,” which could be triggered if their regular tax bill were reduced. And finally, because thresholds for these rates vary by household type, a married couple filing a joint tax return with a total income of $500,000 falls into the top 5% of all tax filers, but their total income — even before accounting for exemptions and deductions — is below the threshold for the Prop. 55 taxes of around $743,000, for example. ↩︎
2
“Tax filer” represents a tax filing unit — the primary filer as well as any spouses and dependents included on the tax return. A tax filing unit can be an individual, a couple, or a family, and in some cases can include unrelated dependents. ↩︎
3
This figure reflects revenues from the top tax rates allocated to TK-14 education from the Education Protection Account (EPA) through the 2024-25 fiscal year. ↩︎
4
The minimum guarantee is determined using one of three formulas: 1) approximately 40% of General Fund revenue, 2) the prior year level adjusted for K-12 attendance growth and growth in per capita personal income, or 3) the prior year level adjusted for K-12 attendance growth and per capita General Fund revenue growth. ↩︎
5
While the top tax rate revenues have provided approximately $120 billion to the TK-14 budget through the EPA, because these revenues also reduce the General Fund dollars to meet the guarantee, the overall education funding impact is approximately 40% of total revenues. ↩︎
6
Prop. 2 (2026), if approved, would make additional changes to require state leaders to increase deposits into the rainy day fund in some high-revenue years. ↩︎
7
Starting in 2030-31, the entire amount will be deposited into the rainy day fund, although policymakers will retain the option to use up to one-half to pay down debts. ↩︎
8
As noted in a text box above (“What Is the Education Protection Account?”), the revenues from the top tax rates both 1) increase the Prop. 98 guarantee and 2) are used to help meet the guarantee, freeing up General Fund revenue for other state budget priorities. If the top tax rates are not extended, the revenues that they generate would be eliminated after the 2030 tax year. This would impact the level of the Prop. 98 guarantee while also creating a hole in the Prop. 98 budget that would have to be filled with other General Fund revenue. ↩︎
You may also be interested in the following resources:
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
Every Californian deserves quality education, health care, well-paying jobs, and the resources to build a secure future — and sustained public investment is how we get there. Recent experience shows that such investments are possible with voter-approved, progressive reforms that strengthen and expand California’s revenue base.
In 2012, California voters asked the state’s highest earners — the top 2% of Californians — to contribute a little more and use that money to invest in the services California’s communities need.
Proposition 30, approved by voters in 2012, temporarily raised income tax rates on just the top 2% of Californians. Four years later, voters chose to keep those rates in place through 2030 by passing Prop. 55. These tax rates have generated significant state revenue, securing investments in education and other important services.
The tax rate on the top 2% of Californians generates $9 to $10 billion per year, supporting investments in education, tax credits for Californians with low incomes, and strengthening the state’s finances.
What investments did the additional revenue secure?
California has used Prop 30/55 revenues to increase investments in education, increase access to health care, expand tax credits to Californians with low incomes, and strengthen state reserves, among other investments. The rate increases, along with a rising economy, made it possible for the state to increase education spending. During this period, the state implemented a major school finance reform and launched other initiatives such as the Universal Meals Program.
The top tax rates are set to expire in 2030, and voters will likely have an opportunity in November 2026 to renew this top tax rate to ensure the investments Californians make in schools, health care, and support for working families can continue.
There was a problem processing your signup. Please try again. Or contact us
Please check your email to confirm your signup.
This website uses cookies to analyze site traffic and to allow users to complete forms on the site. The California Budget & Policy Center does not share, trade, sell, or otherwise disclose personal information. By using our website you agree to our Privacy Policy.